


EN
Does Debt Paydown Change The Bull Case For Weatherford International Stock (WFRD)?
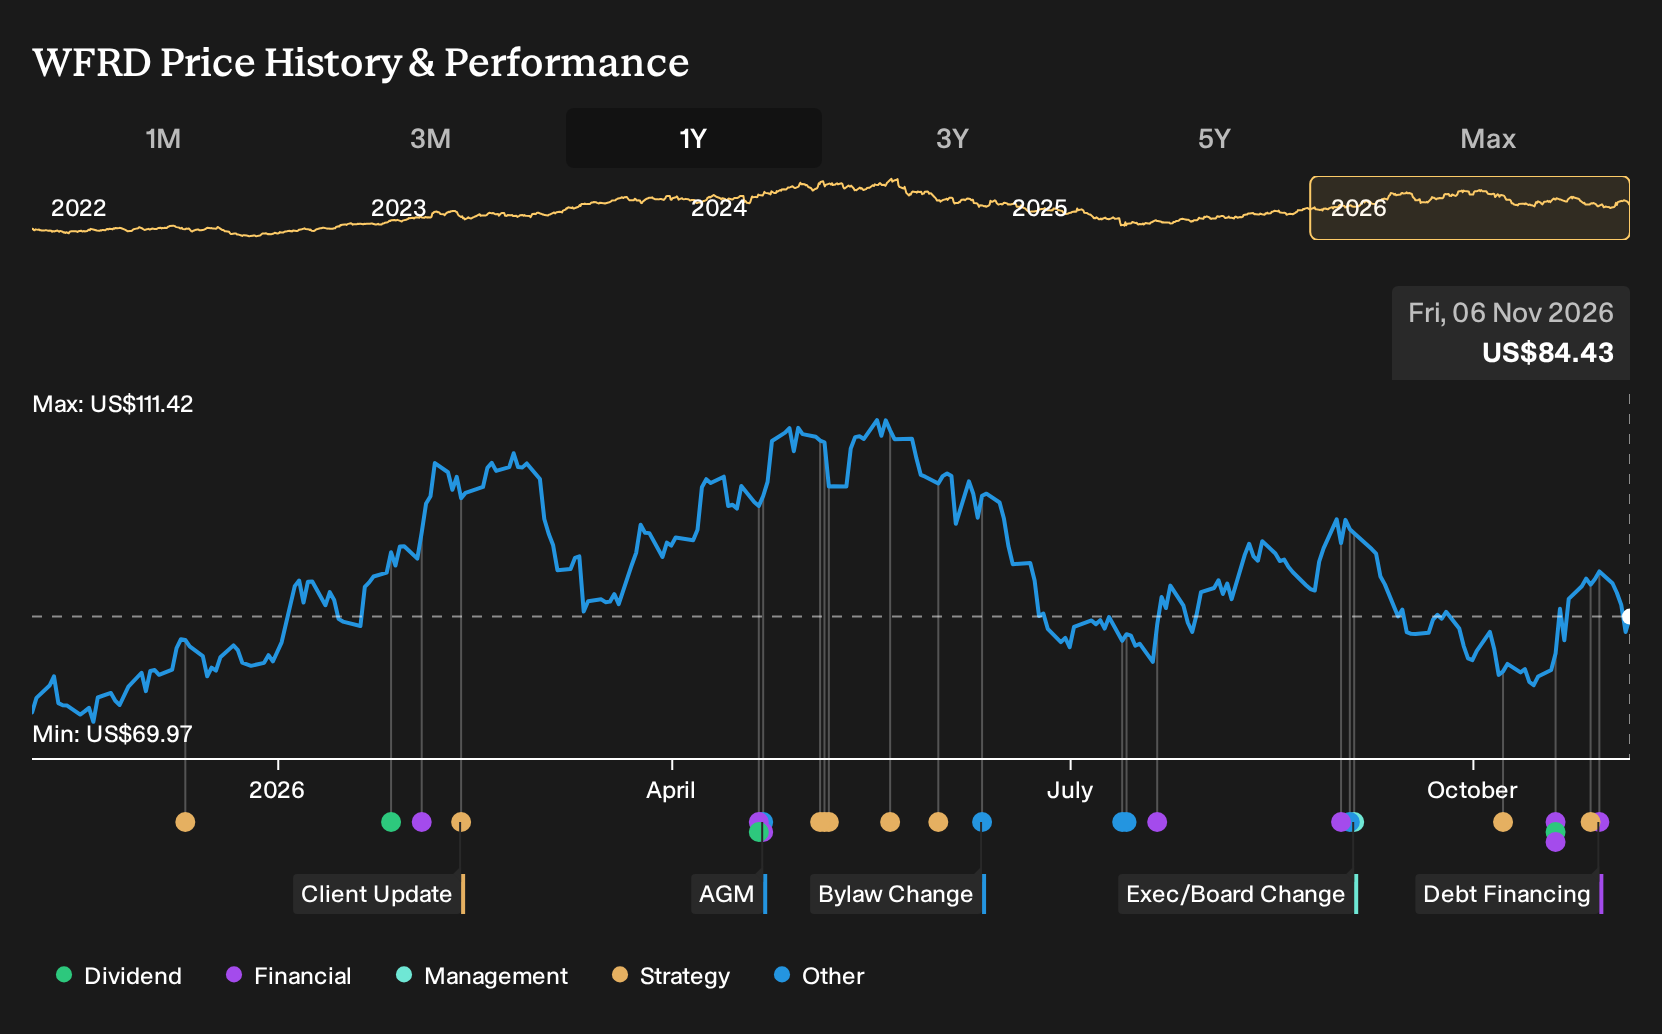
- Weatherford International redeemed all US$236 million of its 8.625% senior notes due 2030 using cash on hand, which reduces gross debt and cuts annual cash interest expense by about US$20 million, while extending its debt maturity runway to roughly seven years.
- Weatherford International also disclosed an integrated services role on Eni’s Junín-5 project in Venezuela, which ties the equipment and services provider into a large development where it can apply its full well lifecycle offering across drilling, workovers and production support.
- We will look at how Weatherford International's debt redemption reshapes the investment narrative and interacts with its technology led service ambitions.
Compare Weatherford International's balance sheet move with other operators tightening their funding profile through our hand picked list of solid balance sheet and fundamentals (24 results) to see how capital discipline varies across the sector.
Weatherford International Investment Narrative Recap
To own Weatherford International, you need to believe the shift toward higher margin, technology heavy services can offset regional disruptions and contract roll offs. The most important near term catalyst is execution on that mix shift while holding free cash flow conversion near recent guidance ranges. The debt redemption helps, but does not change that core bet.
The biggest current risk sits in geopolitical and project friction in the Middle East and the Saudi LSTK roll off, which can weigh on revenue and margins if activity stays soft. Redeeming the 8.625% notes trims interest costs and extends maturities, which supports resilience if those issues persist.
The Junín 5 integrated services role in Venezuela is the announcement that lines up most directly with the current catalyst set. It puts Weatherford International’s full well lifecycle offer to work in a large development, from drilling through workovers and production support, which fits the tilt toward technology led, capital light services.
Execution on Junín 5 now becomes a reference point for future integrated tenders. Operational delivery, safety, and cash collection on this project will matter, especially given past disruptions in other regions. For you as a shareholder, the key question is whether contracts like this can meaningfully backfill Middle East project softness without adding new operational or country risk surprises.
What The Analyst Framework Assumes For Weatherford International
Weatherford International's narrative projects US$5.3 billion revenue and US$581.6 million earnings by 2029. Analysts are assuming 3.8% yearly revenue growth and an earnings increase of about US$215.6 million from current earnings of US$366.0 million.
Discover why Weatherford International's fair value indicates a 34% potential upside to its current price, which could materialize more quickly than many investors anticipate.
Exploring Other Perspectives
One alternate angle on Weatherford International focuses less on Middle East disruption and more on slower revenue momentum. The most cautious analysts were modelling about US$5.3b of revenue and US$607.8m of earnings by 2029 before this debt redemption and Junín 5 contract, building a far more restrained story. Use those lower forecasts as a reference point and explore how your own expectations differ, since this new information could shift both bullish and bearish narratives over time.
Explore 5 other Weatherford International fair value estimates, including one that suggests it could be worth just $93.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Weatherford International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weatherford International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weatherford International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Weatherford International?
Once you have an opinion on Weatherford International, it can help to compare that view with other opportunities that share similar qualities or address different portfolio needs. The Simply Wall St screener provides a structured way to do that, without relying on headlines or hype.
- For investors hunting for mispriced quality, review the 39 high quality undervalued stocks that combine solid fundamentals with appealing valuations.
- If capital preservation matters most to you, check out the 29 resilient stocks with low risk scores that show stronger resilience on our risk scoring.
- For those who want tomorrow’s potential compounders before they are widely followed, scan through the 19 high quality undiscovered gems and decide which stories you want to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com