


EN
Six Flags Shares In Focus After Narrower Losses In Earnings Report
- Six Flags Entertainment reported third quarter sales of US$195.55 million and revenue of US$1,173.08 million, with net loss and loss per share from continuing operations narrower than the same period last year.
- Across the first nine months of the year, the business recorded lower revenue and a smaller overall loss. This suggests that ongoing cost and portfolio actions are flowing through the income statement even as top line pressure remains.
- We will look at how Six Flags Entertainment's investment narrative is affected by lower revenue alongside a smaller net loss.
Scan beyond Six Flags Entertainment and compare this update with a hand picked 39 high quality undervalued stocks that are also juggling revenue pressure with improving loss profiles.
Six Flags Entertainment Investment Narrative Recap
To own Six Flags Entertainment, you need to believe that a leaner, more efficient park operator with more recurring season pass revenue can eventually turn recurring losses into steady cash generation. The latest quarter keeps that story intact. Revenue for both the quarter and year to date is under pressure, yet the loss has narrowed meaningfully, which points to cost work and portfolio changes taking hold.
The short term pivot still hinges on execution around Cedar Fair merger synergies and digital tools that aim to lift guest spend without hurting attendance. The biggest near term risk stays the same: high leverage and ongoing legal and regulatory exposure from the recent fatal accident leave little room for operational missteps if revenue softness persists.
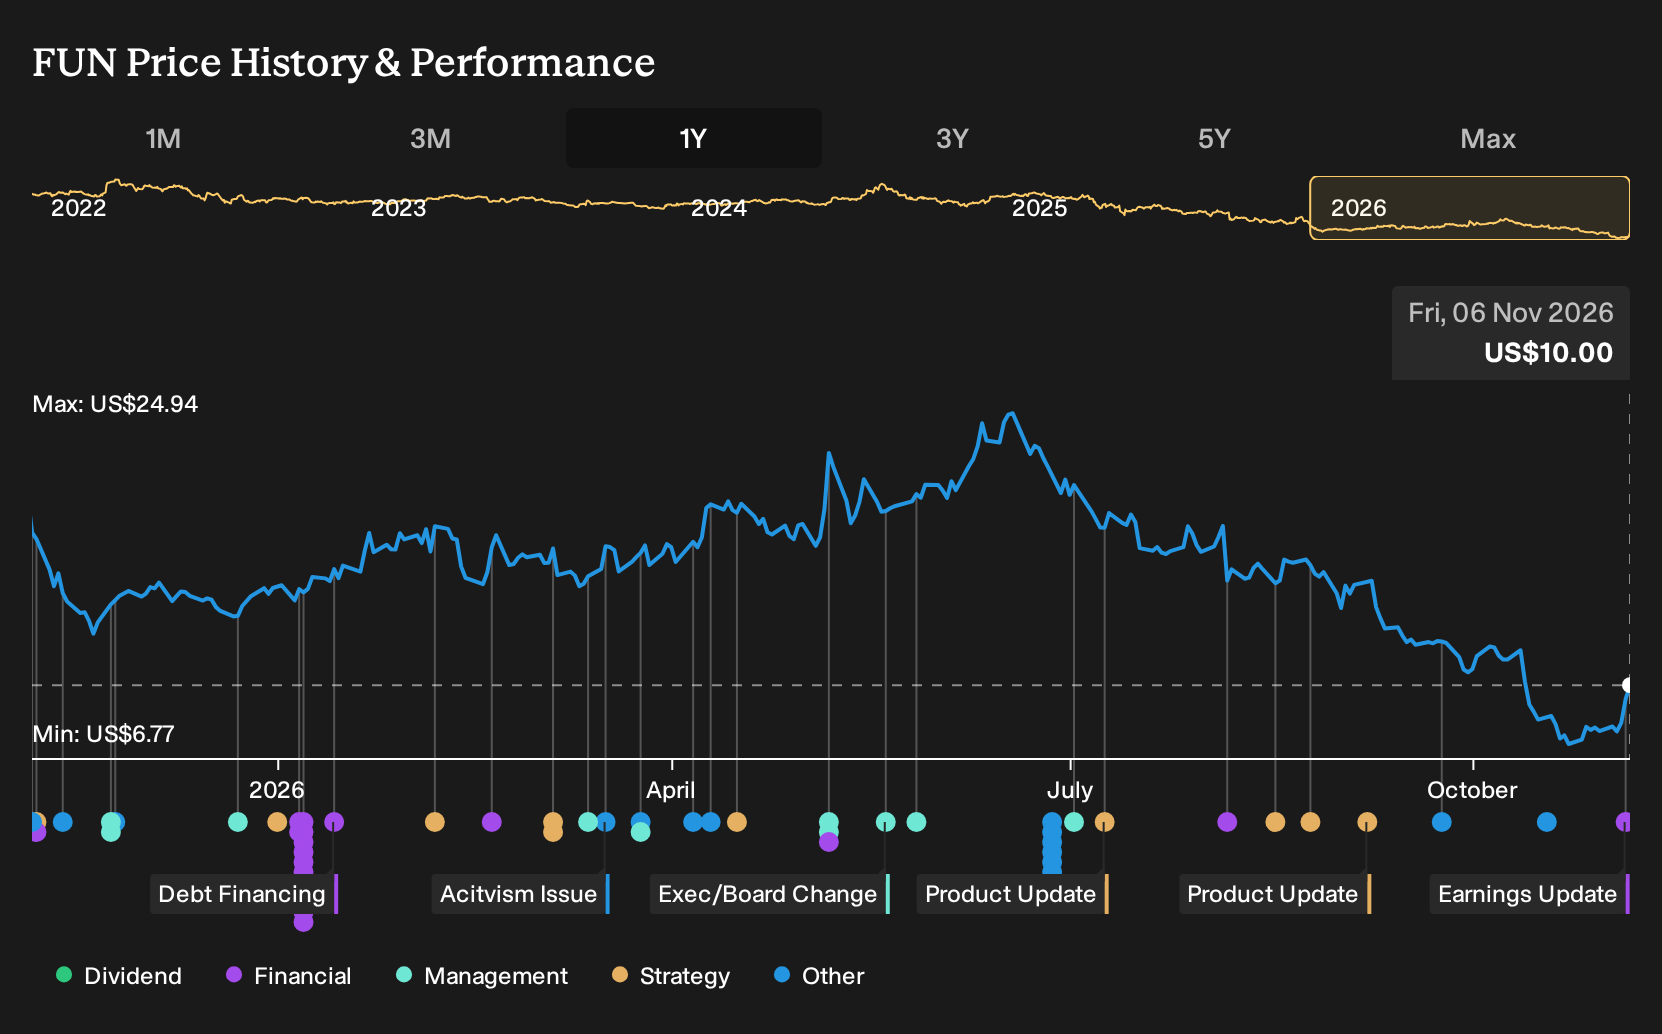
The most relevant update here is the third quarter and nine month earnings release on 5 November 2026. Sales and total revenue were lower than a year ago across both periods, yet the reported net loss and loss per share from continuing operations were materially smaller. That combination matters for a business carrying around US$4.9b of net debt and working with a relatively new leadership team.
For your thesis, the narrower loss hints that cost discipline, portfolio simplification and early Cedar Fair consolidation efforts are reaching the income statement, even while top line pressure remains. Against that, the firm is still unprofitable, facing safety related scrutiny after the Goliath incident and operating with volatile equity performance. The next few quarters of earnings will be important checkpoints on whether operational improvements can outpace those risks.
Six Flags Entertainment's current earnings are a loss of US$1.8b, while analysts collectively expect earnings to reach US$66.6 million by 2029. This implies an earnings increase of roughly US$1.87b, and they are also assuming fairly flat revenue over that period, with revenue of about US$3.1b by 2029.
Uncover why Six Flags Entertainment's fair value indicates a 70% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Six Flags Entertainment analysts were leaning heavily on faster cost savings as the key upside, estimating about US$3.2b of revenue and US$143.6 million of earnings by 2029. You can now weigh those pre earnings expectations against the latest loss reduction and decide which storyline feels closer to your own view.
Explore 5 other Six Flags Entertainment fair value estimates, including one that suggests a potential upside of up to 374% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider conducting your own research and going with your instincts.
- A great starting point for your Six Flags Entertainment research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Six Flags Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Six Flags Entertainment's overall financial health at a glance.
Looking For More Investment Ideas Beyond Six Flags Entertainment?
If the Six Flags Entertainment story has you rethinking where risk and reward feel worthwhile, broaden your watchlist with stocks that fit different profiles on value, quality and balance sheet strength using the Simply Wall St Screener.
- For investors who want potential mispricings with solid fundamentals, start with a curated 39 high quality undervalued stocks that may warrant a closer look.
- If resilience and lower volatility matter more to you than headline growth, filter for candidates in our 29 resilient stocks with low risk scores to see which businesses align with that preference.
- When you prefer companies that already carry strong financial footing, scan through the list of solid balance sheet and fundamentals (24 results) to spot ideas that begin with sturdier foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com