


EN
Valaris (VAL) Earnings Hit Sentiment, Is The Offshore Upside Already Priced In?
Valaris earnings jolt puts recent share move in focus
Valaris (VAL) just posted third quarter results that kept revenue broadly flat at US$593.6 million while net income and earnings per share dropped sharply from the same period a year earlier.
The earnings drop has arrived after a volatile stretch for Valaris, with the share price falling 24.25% over the past week, even as the year to date share price return sits at 52.96% and the 1 year total shareholder return is 46.61%. This suggests strong longer term gains but fading near term momentum around the US$79.77 level.
Scan beyond Valaris and see how other oil and gas contractors are reacting to earnings shocks with our curated list of 39 high quality undervalued stocks in the sector.
After a 24% slide in a week and a share price above the US$69 analyst target, the gap between Valaris market value and several intrinsic estimates has widened. Where does fair value really sit now?
Most Popular Narrative: 18% Overvalued
Valaris closed at $79.77 against a most-followed fair value estimate of $67.43, which frames the current debate around how much future offshore upside is already embedded in the price.
The pending Transocean combination is positioned around a multiyear up cycle in offshore drilling, with forecasts of a very large increase in deepwater project sanctioning by 2027 and expectations that seventh generation drillship utilisation exits 2026 around 90%. This optimism can keep investors capitalising that anticipated tightness generously into Valaris cash flow and net margins before those future contracts are actually awarded and worked.
See why 31 investors see Valaris as 18% overvalued.
Result: Fair Value of $67.43 (OVERVALUED)
Still, the narrative around Valaris can be challenged if the Transocean merger underdelivers on its promised US$200m in savings, or if offshore drilling demand softens.
Find out about the key risks to this Valaris narrative.
Another View: Valaris on earnings multiples
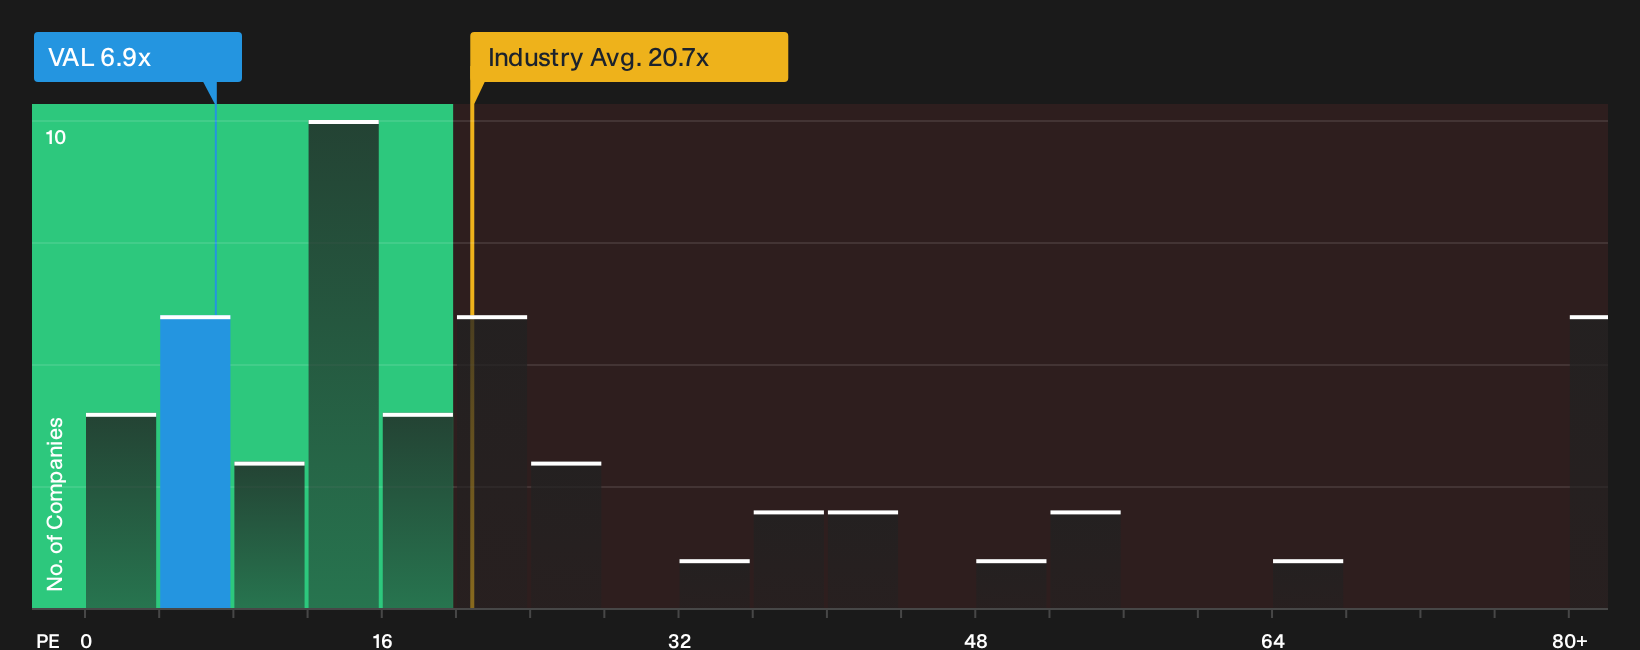
The DCF workup flags Valaris as good value, yet the earnings multiple paints a different picture. The stock trades on a P/E of 6.9x versus 20.7x for the US Energy Services group and 55.1x for peers, while the fair ratio sits at 8.6x. Is the discount a cushion or a signal that expectations need adjusting?
For a closer look at how that earnings gap could close or widen, and what the numbers imply if the market moves toward the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these around Valaris only matter if you turn them into your own decision. Move quickly, review both sides of the story, and weigh up the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Valaris?
You have already done the hard work by digging into Valaris, so do not stop short when other opportunities could be sitting in plain sight.
- Target stability first and cut down portfolio stress by focusing on 29 resilient stocks with low risk scores that score well on resilience and downside protection.
- Hunt for value where quality and price still line up and scan our 39 high quality undervalued stocks before the crowd closes the gap.
- Strengthen your core holdings with companies that carry healthier finances using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com