


EN
Why Did LandBridge (LB) Stock Climb After Its Latest Update?
Why LandBridge Stock Is Back in Focus
LandBridge (LB) just dropped fresh third quarter results, pairing higher revenue and net income with an affirmed quarterly dividend, and that mix is what pulled the stock back onto investor screens this week.
At a share price of $65.10 after a 1 day share price return of 5.2%, LandBridge is still digesting a tough stretch that includes a 7 day share price return down 22.1% and a 30 day share price return down 24.1%. The year to date share price return of 34.3% contrasts with a 1 year total shareholder return down 5.3%, pointing to strong recent momentum after a weaker earlier run as investors reassess the earnings pickup and confirmed dividend.
Compare LandBridge's earnings fueled move with other companies showing strong fundamentals and price dislocations by scanning our hand picked 39 high quality undervalued stocks.
LandBridge just posted stronger revenue and profit, but the share price is still well below recent highs. The key question for investors now is whether there is still meaningful upside ahead or if most of the easy rerating already occurred before earnings were released.
Most Popular Narrative: 25.5% Undervalued
Against LandBridge's last close at $65.10, the most followed narrative pegs fair value at $87.43, so the current pullback sits against a thesis that still sees material upside based on future cash flows discounted at 8.56%.
LandBridge's capital-light model and focus on long-term, fee-based contracts (for example, triple-net leases and surface use royalties now making up 94% of revenue) enhance free cash flow generation and lead to greater earnings resiliency, even in periods of commodity price weakness, positively affecting both EBITDA margins and cash flow stability.
See why 20 investors see LandBridge as 26% undervalued.
Result: Fair Value of $87.43 (UNDERVALUED)
Still, the LandBridge story depends on projects and geography that can cut both ways, since Permian concentration and delayed renewable or data center revenue could upset those optimistic assumptions.
Find out about the key risks to this LandBridge narrative.
Another View On LandBridge's Valuation
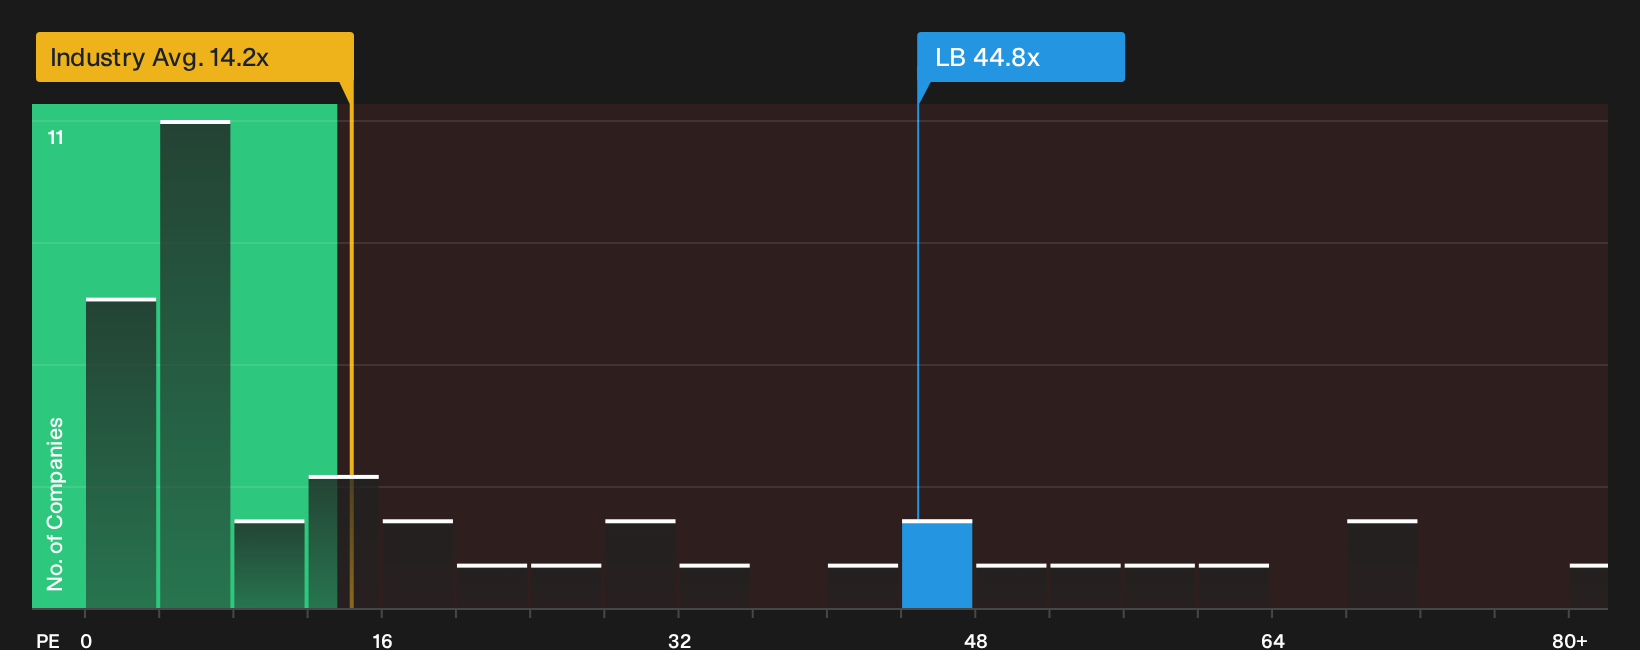
DCF suggests LandBridge trades at a steep discount, with the stock at $65.10 and an estimated future cash flow value of $116.42, roughly 44% higher. A P/E lens tells a different story, though. The shares trade on 44.8x earnings, far above the US Real Estate sector on 14.2x and peers on 31x. That level sits close to a fair ratio of 46.1x. Is the gap a genuine mispricing or simply rich expectations reflected in the multiple?
Investors who want to see how that earnings multiple compares with what the cash flow math suggests can review how the SWS DCF model treats LandBridge in more detail in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals across LandBridge can feel confusing, so treat this as your prompt to move quickly. Dig into the numbers and pressure test the bullish and bearish angles against your own expectations with 4 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond LandBridge?
You have fresh context on LandBridge. Now widen the lens and line up a few more candidates so you are not relying on a single story.
Use the Simply Wall Street Screener to quickly surface other opportunities with different profiles and risk levels before the next wave of results moves the market.
- Target resilient balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that can complement a higher risk holding like LandBridge.
- Hunt for pricing gaps where quality and valuation intersect by reviewing our focused 39 high quality undervalued stocks that flags companies with stronger fundamentals than their share prices suggest.
- Boost your income ideas by checking a concentrated 8 dividend fortresses that filters for higher yields supported by more robust financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com