


EN
Why Objective Bears Were Right Before A 62% Drop
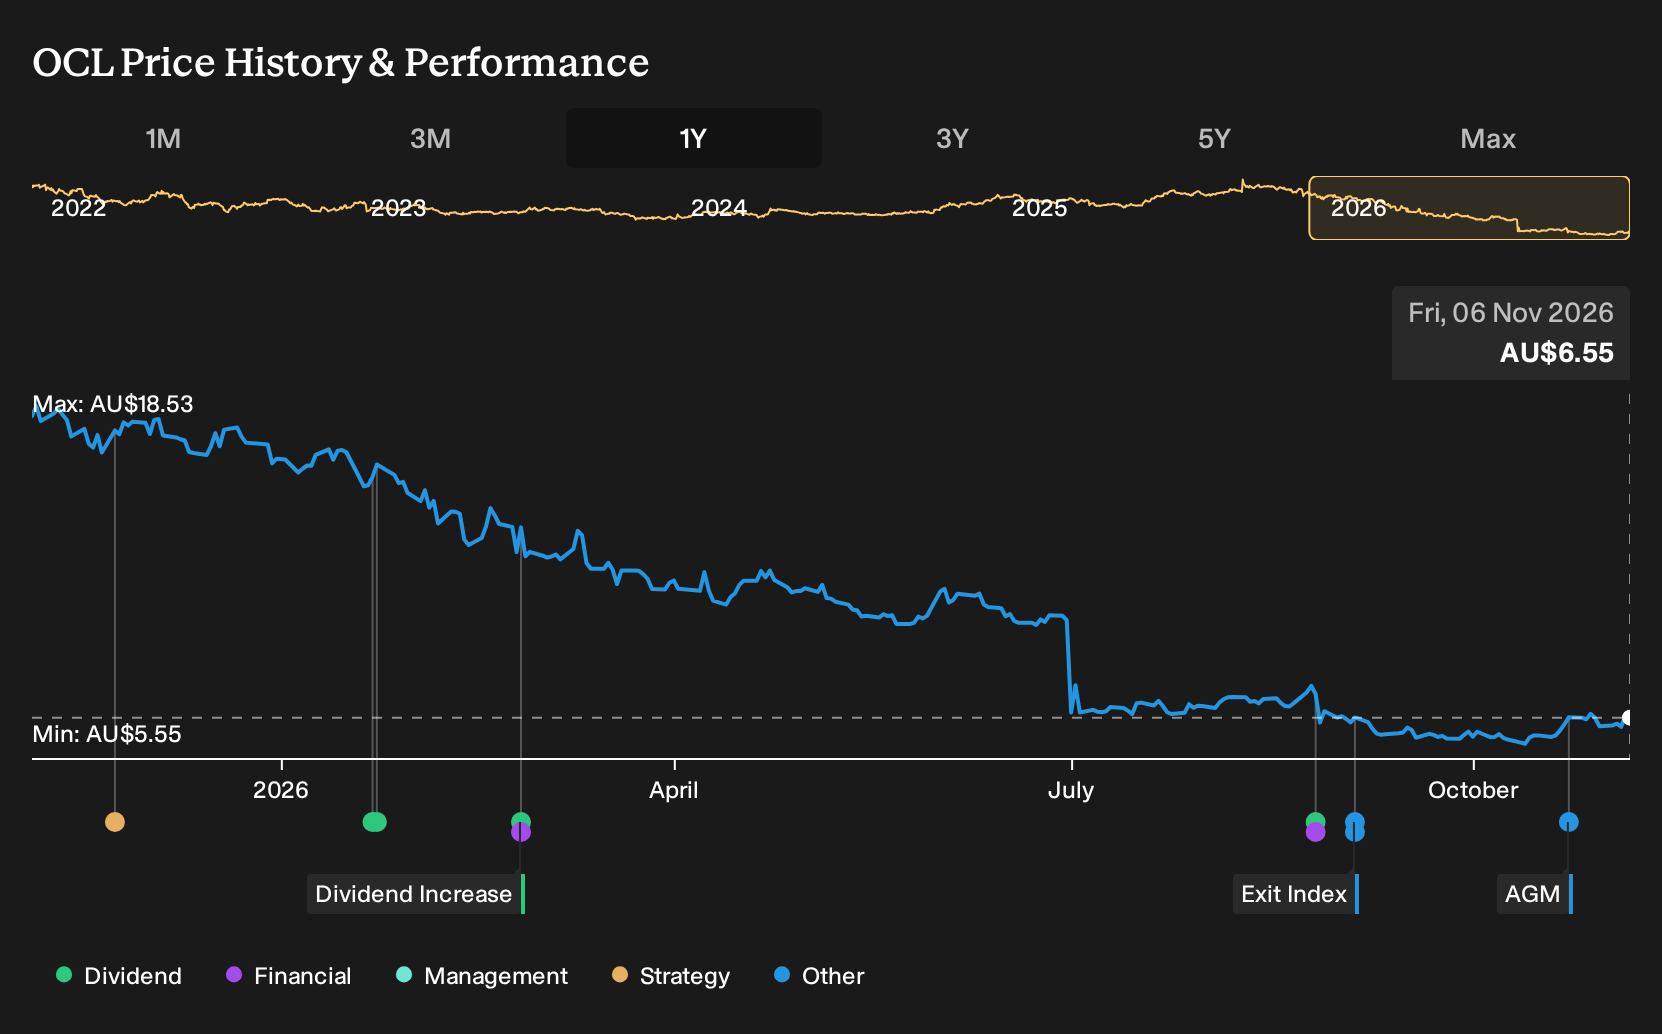
If you had backed Objective on 6 November 2025 and simply held on, the outcome would have been brutal. Holding Objective over the past year would have meant a 62.4% loss, including dividends. That result lands after a surprise decision by the Australian Department of Defence not to renew a 25 year ECM support agreement and a sharp reset in market expectations. If the original thesis rested on sticky public sector ties, what did it miss about contract renewal risk and growth sensitivity to one big client relationship?
The easy part of this move is behind Objective. Zero in on 4 high quality undervalued stocks for companies trading below our estimates.
The Two Objective Stories Investors Had To Weigh
The shares cost A$18.53 at the start of the period, and the live debate was about how far Objective’s subscription pivot and public sector focus could carry it.
On the bullish side, one Narrative pointed to a Fair Value of A$20.5 that reflected what the upside might look like if near full cloud migration, strong AI features, and recurring revenue growth supported higher margins and a premium P/E multiple.
The bearish view anchored on a Fair Value of A$7 that captured concern about heavier regulation, economic fragility, and pressure on government IT budgets that could weigh on revenue growth and margins.
What The Facts Did To The Objective Argument
The Australian Department of Defence walking away from Objective’s 25 year ECM support program directly challenged the bullish story about ultra sticky government ties. At the same time, H2 2026 revenue of A$67.982m and net income of A$18.486m, alongside a lower 27.2% margin, suggested the business still produced profit but with pressure on profitability.
The lesson is simple. When a thesis leans on key accounts, you need to watch customer concentration, contract expiry dates, and the direction of recurring revenue and margin in later results.
Objective After A 62% Fall, What The Price Now Implies
Objective now trades at A$6.55, well below where it started one year ago. The selected Narrative still places Fair Value above the current price and pins its argument on essential software, subscription revenue and a strong balance sheet.
The key question for you is straightforward. A buyer today must believe government customers remain sticky enough and diversified enough that the Defence loss proves painful but not thesis breaking.
"When a regulator issues a licence, when a council approves a development application, when a department publishes policy, Objective''s software is probably running underneath. Nobody brags about owning the company that digitises building approvals in Brisbane. That''s the appeal."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Objective’s Contracts
Objective lives in regulated workflows. Your next step could sit one layer out.
Those same public bodies increasingly rely on broad cloud and AI platforms to run everyday work, secure data, and manage collaboration.
Another large provider builds the underlying software suites, developer tools, and AI assistants that many organisations already use across documents, code, and customer workflows.
Its model leans on subscriptions tied to seats, then adds usage based AI and developer services on top.
That mix keeps raising a practical question. How far can heavier AI and cloud use reshape what software clients pay for and depend on next?
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 19% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com