


EN
Disability Claims Surge Could Be A Game Changer For Unum Group (UNM)
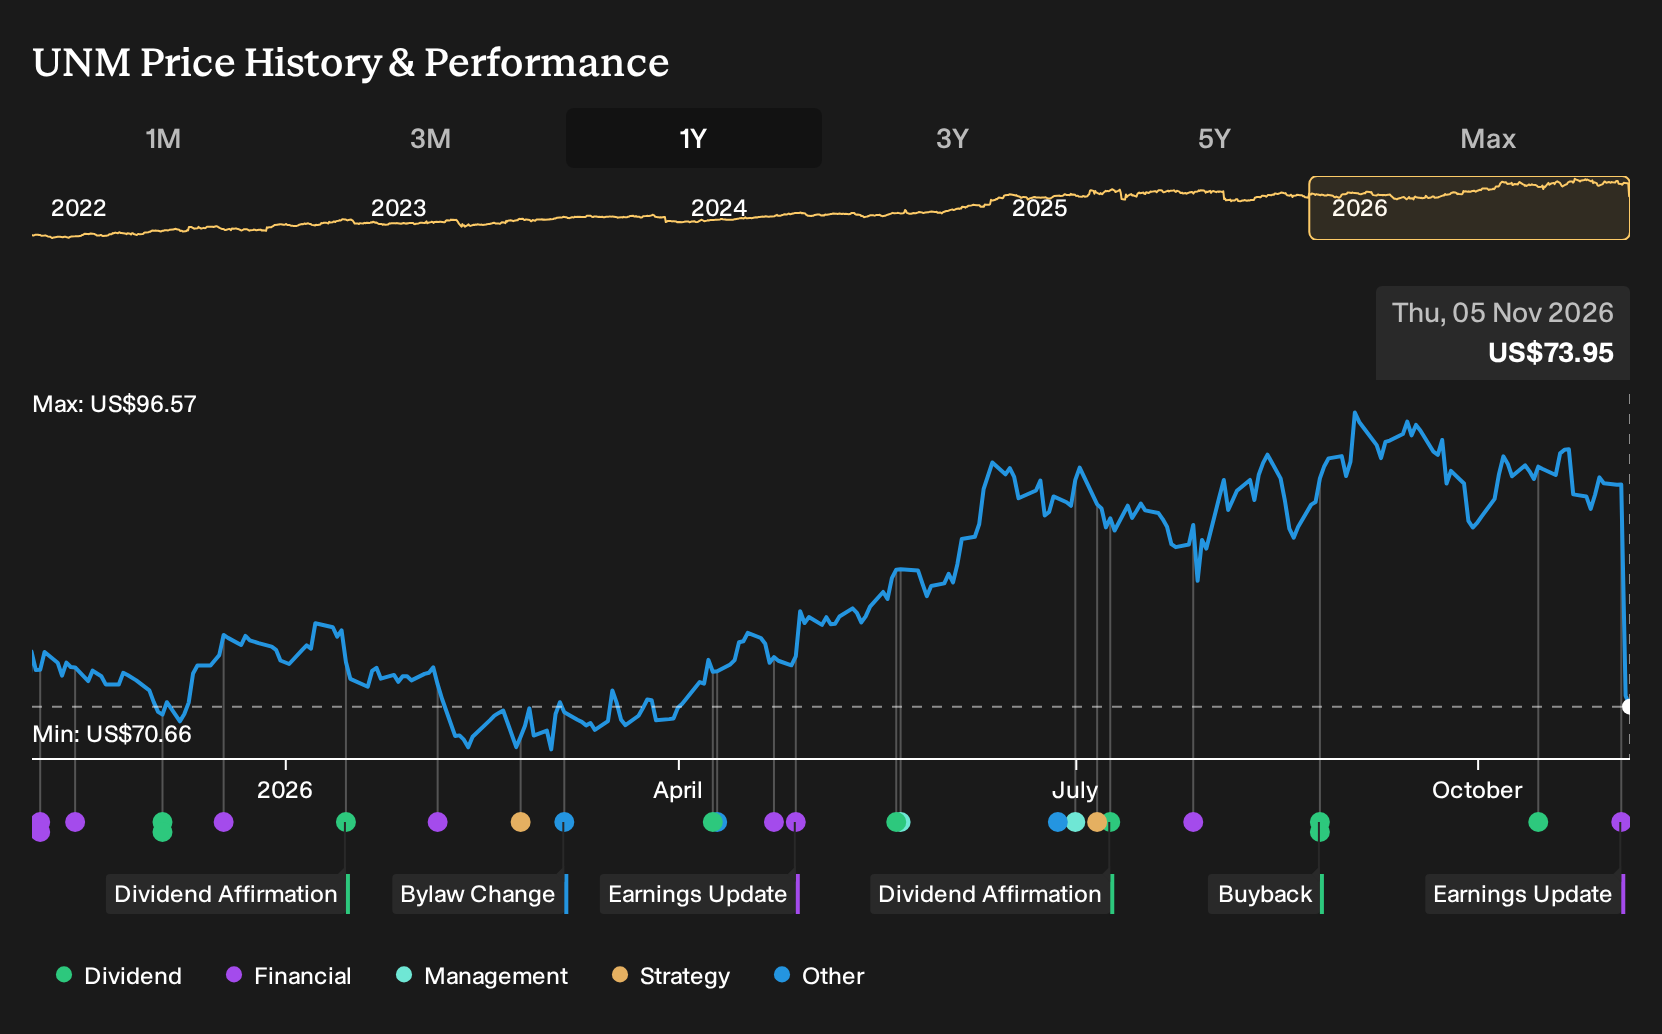
- Unum Group reported third quarter 2026 revenue of US$2,547.5 million and a net loss of US$419.7 million, reversing net income a year earlier and leading to lower full year earnings guidance.
- The earnings hit was tied to a 10% rise in US long term disability claims and pressure in UK group income protection, even as the long term care reinsurance deal with Fortitude Re reshaped Unum Group’s risk profile and reduced statutory reserves.
- We will now assess how Unum Group's investment narrative is affected by the surge in long term disability claims and the revised outlook.
Compare Unum Group's claim driven earnings reset with other insurers facing similar pressures by scanning our hand picked list of 29 resilient stocks with low risk scores.
Unum Group Investment Narrative Recap
To hold Unum Group through this, you need to believe the core employee benefits engine can offset pressure from higher disability and income protection claims. The immediate swing factor is whether US long term disability submissions and UK group income protection large losses can be contained through pricing, underwriting and claims management without eroding employer demand.
The biggest near term risk is that elevated benefit ratios in group disability, paid family and medical leave and UK protection persist, which would keep margins and net income under strain. Any progress on repricing, retention and digital tools like HR Connect and Total Leave becomes critical to stabilising earnings from here.
The Fortitude Re long term care reinsurance deal is the announcement that matters most for this earnings reset. Unum Group has ceded about US$3.8b of statutory reserves and reduced more than US$7b of statutory reserves in total, which reshapes how capital is tied up in the older long term care block.
This transaction narrows the focus toward group benefits and frees capacity for the digital and distribution initiatives investors already watch as key catalysts. The reinsured Closed Block still carries execution and reserving risk, but with less capital intensity, attention can shift more squarely to whether core disability, life and Colonial Life can earn attractive returns.
Unum Group's narrative projects US$13.1b revenue and US$1.6b earnings by 2029. This rests on revenue staying broadly flat while earnings rise by about US$897.3m from US$702.7m today.
Discover how Unum Group's fair value indicates a 33% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$102 to US$164 per share, so private investors are applying very different earnings paths to Unum Group. That split sits against fresh disability claim pressure and the Fortitude Re deal, which together shape how you might weigh upside against future profit volatility.
Explore another Unum Group fair value estimate, including one that suggests as much as 114% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Unum Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Unum Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unum Group's overall financial health at a glance.
Looking for more investment ideas beyond Unum Group?
If the claim trends and capital moves at Unum Group have you rethinking concentration risk, it can help to line up a few alternatives on your watchlist using the Simply Wall St Screener.
- If you want potential mispricings with solid fundamentals to review next, start with a focused set of 41 high quality undervalued stocks that already combine quality and price discipline in one place.
- For readers who prefer financial resilience over excitement, filter for balance sheets that look robust by scanning a curated list of solid balance sheet and fundamentals (24 results).
- If you are hunting for less crowded opportunities, broaden your research with a hand picked pool of 19 high quality undiscovered gems that could merit a closer look before they hit more radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com