


EN
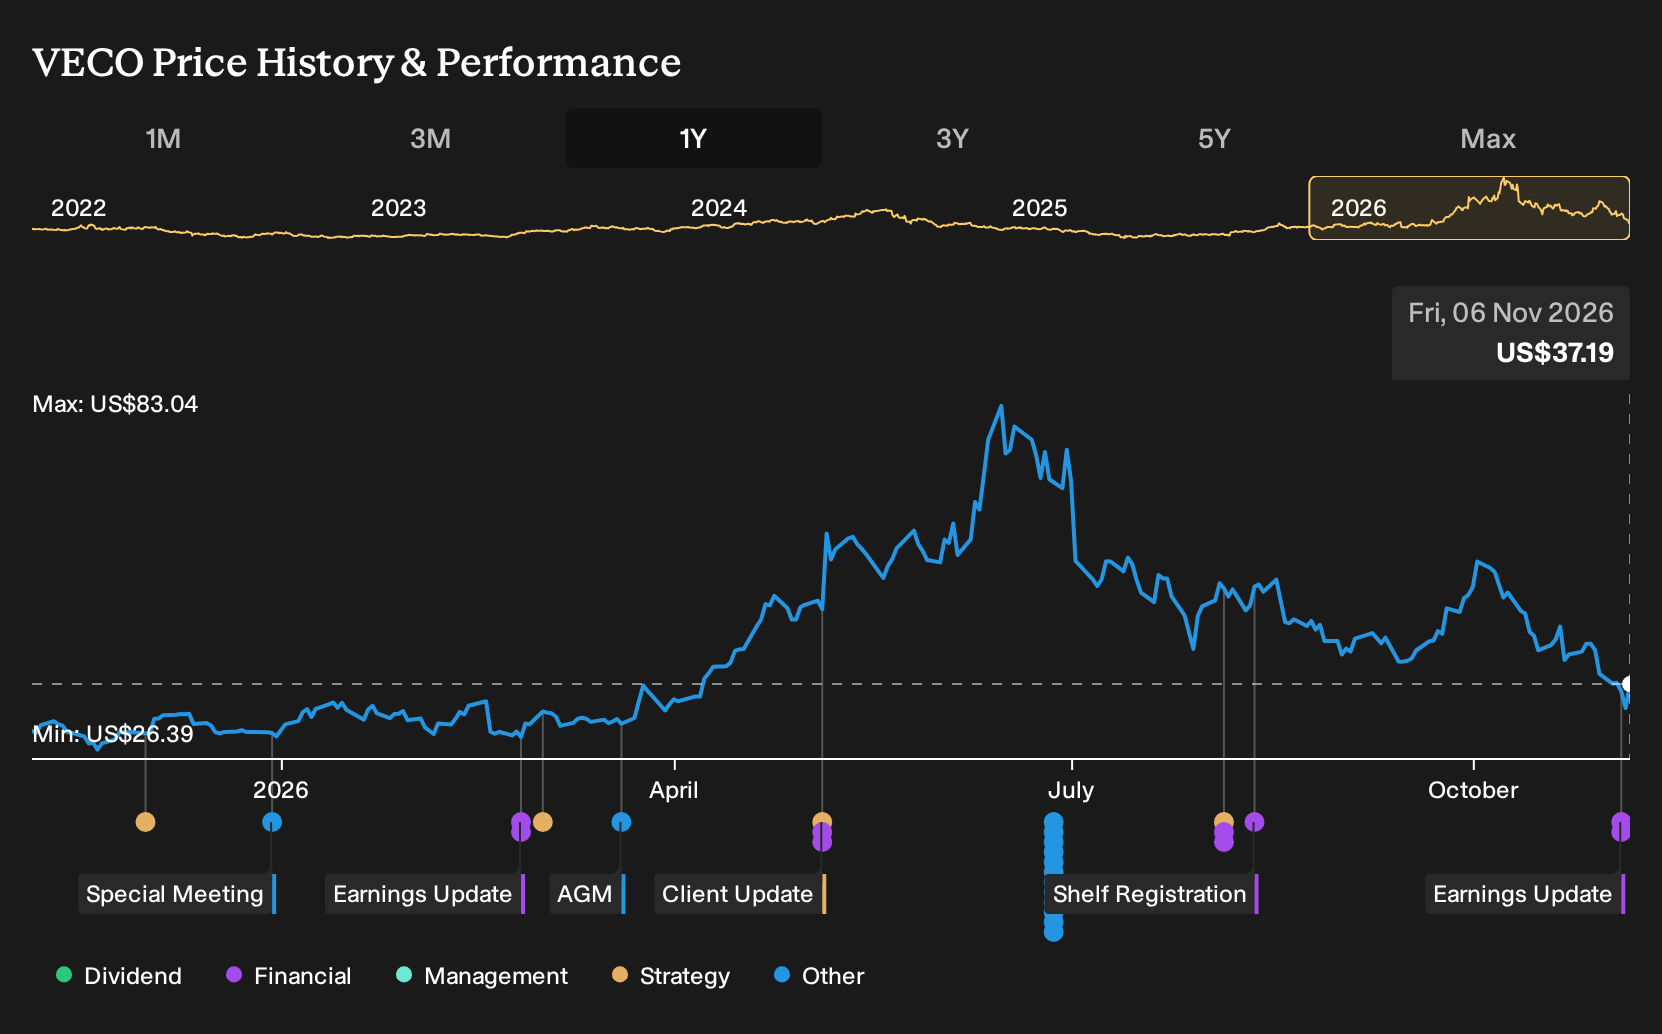
Why Veeco Instruments (VECO) Is Up 11.8% And What's Next
- Veeco Instruments reported third quarter 2026 revenue of US$209.38 million and net income of US$13.64 million, while issuing guidance for fourth quarter and full year 2026 revenue and earnings per share ranges and outlining expected operating income and net income levels.
- The business paired mixed quarterly earnings versus prior analyst expectations with a strong AI and advanced packaging driven order book and capacity expansion plan. Management also outlined a path that could potentially lead to revenue above US$1 billion in 2027, supported by semiconductor, silicon photonics and compound semiconductor demand.
- The focus now shifts to how Veeco Instruments' AI and advanced packaging capacity buildout could reshape its broader investment narrative.
Scan past Veeco Instruments and see how other AI infrastructure and advanced packaging plays stack up in our hand picked 52 AI infrastructure stocks list.
Veeco Instruments Investment Narrative Recap
To own Veeco Instruments, you need to be comfortable with a story built around AI infrastructure, advanced packaging and silicon photonics tooling, backed by a plan to more than double manufacturing capacity by 2027. The recent quarter showed higher sales and profit compared with a year ago, but margins remain a clear pressure point.
The key short term catalyst is execution on the current order book and on the capacity build, while absorbing roughly US$10 million of extra operating expense and about 75 basis points of gross margin headwind in 2026. The biggest risk is that demand or pricing fails to fill that larger footprint, which could leave earnings more sensitive to any slowdown or export control disruption.
The most relevant update for this quarter is Veeco Instruments' guidance for the fourth quarter and full year 2026. Management outlined expected Q4 revenue of US$230 million to US$260 million, with GAAP diluted EPS of US$0.34 to US$0.53, and operating income between US$24 million and US$39 million. This frames how quickly they think the model can scale from today’s level.
For the full year 2026, Veeco Instruments now targets revenue of US$790 million to US$820 million and GAAP diluted EPS of US$0.72 to US$0.92, with net income of US$48 million to US$62 million. For you as an investor, this guidance sits right next to the capacity expansion and Axcelis merger plan and it provides a concrete check point for whether the AI and advanced packaging thesis is tracking or starting to strain margins and returns.
Veeco Instruments' narrative projects US$1.5b revenue and US$367.0 million earnings by 2029. This aligns with analyst assumptions for 29.1% yearly revenue growth and an earnings increase of about US$344 million from US$23.2 million today.
Uncover why Veeco Instruments' fair value indicates a 65% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Veeco Instruments puts far more weight on execution risk around the capacity ramp. Some of the lowest analysts were pencilling in only about US$1.2b of revenue and US$216.5 million of earnings by 2029 before this earnings release. That is a much more cautious story. Use this quarter’s guidance as an opportunity to compare those assumptions with your own and consider how opinions might change from here.
Explore 4 other Veeco Instruments fair value estimates, including one that suggests it could be worth just $50.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Veeco Instruments research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Veeco Instruments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veeco Instruments' overall financial health at a glance.
Looking for more ideas beyond Veeco Instruments?
If you want to stress test your view on Veeco Instruments against other opportunities, it helps to see how different types of stocks line up on quality, valuation and resilience. The Simply Wall St Screener can be a useful way to compare what you own with what you could own next.
- If resilience and capital preservation matter most to you, start by scanning a set of 29 resilient stocks with low risk scores that score well on overall stability.
- If you prefer to focus on quality at a reasonable price, line up potential candidates using our 41 high quality undervalued stocks and see which ones fit your checklist.
- If balance sheet strength is your priority, filter for companies with robust finances using this list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com