


EN
5N Plus (TSX:VNP) Could Be 26% Undervalued As Margin Pressure Hits Earnings
5N Plus (TSX:VNP) just released third quarter 2026 results that combined higher sales with tighter profitability, as strong Specialty Semiconductors demand met rising costs and contract timing issues impacting margins.
The latest Q3 announcement appears to have reignited interest in 5N Plus, with the share price climbing 9.4% on the day and 29.31% over the past week, while the year-to-date share price return of 86.28% and a very large 5-year total shareholder return indicate that long-term momentum remains firmly positive.
Scan beyond 5N Plus and see how other materials players with momentum and contract-backed demand stack up in our hand-picked 7 high quality undiscovered gems.
Bulls see 5N Plus as a contract-backed growth story that just had a margin wobble, while bears see a hot stock exposed to rising costs. Which side does the current valuation really support?
Most Popular Narrative: 26% Undervalued
On the narrative view, 5N Plus screens as undervalued, with a fair value of roughly CA$45.43 against the last close of CA$33.53. This puts the recent price action into sharper context.
The expanded long term supply agreement with the strategic U.S. solar customer, which increased contracted terrestrial renewable volumes by 33% for 2025 to 2026 with a further 25% lift through 2028, supports continued growth in semiconductor compound revenue and the potential for higher absolute earnings as these contracts are fulfilled.
See why 24 investors see 5N Plus as 26% undervalued.
Result: Fair Value of CA$45.43 (UNDERVALUED)
Still, the 5N Plus story depends on cleaner execution, since persistent input cost pressure or ongoing production hiccups could chip away at the bullish narrative.
Find out about the key risks to this 5N Plus narrative.
Another Angle On 5N Plus: Rich Earnings Multiple
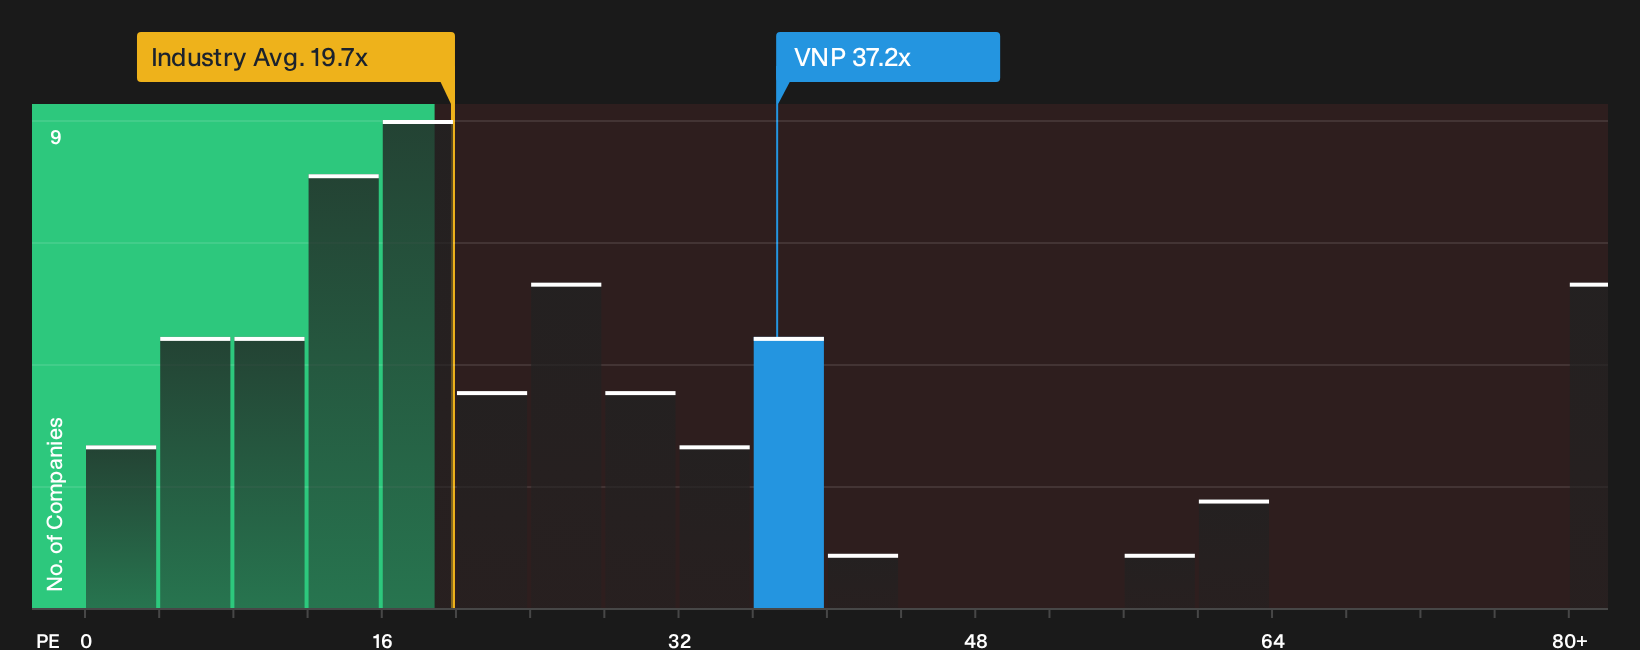
While the narrative and analyst targets frame 5N Plus as undervalued, its current P/E of 37.3x tells a different story. The stock trades well above both the peer average of 13.9x and the wider North American Chemicals group at 19.7x, and even above a fair ratio of 17.7x. That gap suggests investors are already paying a premium for growth and execution, so you need to decide whether this pricing leaves enough room for error.
If you want to see how this earnings multiple stacks up in more detail and what the fair ratio gap could mean for future pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on 5N Plus after these results. If you want to move quickly and reach your own view on both the upside and the concerns, start by weighing the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond 5N Plus?
If you want even stronger context around 5N Plus, widen your lens and compare it with other high conviction ideas across quality, income, and value.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (5 results) so you can focus on sturdier businesses when markets turn.
- Prioritise a stream of income alongside potential price returns by checking companies in the 3 dividend fortresses that meet your yield comfort zone.
- Hunt for mispriced quality before the crowd does by reviewing the 6 high quality undervalued stocks and see which opportunities might deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com