


EN
Delek Logistics Partners (DKL) Declares Q3 Distribution Following A Fairly Priced Valuation View
Delek Logistics Partners (DKL) has declared its third quarter 2026 cash distribution of $1.14 per common limited partner unit, or $4.56 on an annualized basis, keeping income front and center for unitholders.
At a share price of $51.77, Delek Logistics Partners has seen the 7 day share price return fall 7.69% and the 90 day share price return decline 8.78%. However, the year to date share price return is 10.15% and the 1 year total shareholder return sits at 25.9%, hinting at fading short term momentum alongside stronger income driven long term gains.
Scan income-focused opportunities that echo Delek Logistics Partners' distribution story with a curated set of 8 dividend fortresses designed for investors who prioritize steady cash payouts.
Delek Logistics Partners keeps writing an income story that many investors like. After the recent pullback, the real question is whether that cash flow is already fully reflected in today’s unit price.
Most Popular Narrative: 2.6% Undervalued
The most followed narrative on Delek Logistics Partners pegs fair value at about $53.17 per unit, only slightly above the recent $51.77 close. This frames today’s income story as tightly priced rather than deeply mispriced.
The 2026 growth capital program of about US$180 million to US$190 million, which management expects to yield up to US$75 million of run rate EBITDA with most of that impact in 2027, points to additional earnings and cash flow contribution beyond what is currently in reported results.
The shift in EBITDA mix toward third party customers, with management reiterating an outlook of roughly 80% of 2026 run rate EBITDA from non sponsor counterparties, can diversify revenue, influence the partnership's risk profile and support a more independent earnings and cash flow base.
See why 4 investors see Delek Logistics Partners as 3% undervalued.
Result: Fair Value of $53.17 (UNDERVALUED)
Still, two pressure points could flip that story: earnings missing analyst expectations, and leverage staying above management’s 3.5x target for longer than planned.
Find out about the key risks to this Delek Logistics Partners narrative.
Another View: Delek Logistics Partners On Earnings Multiples
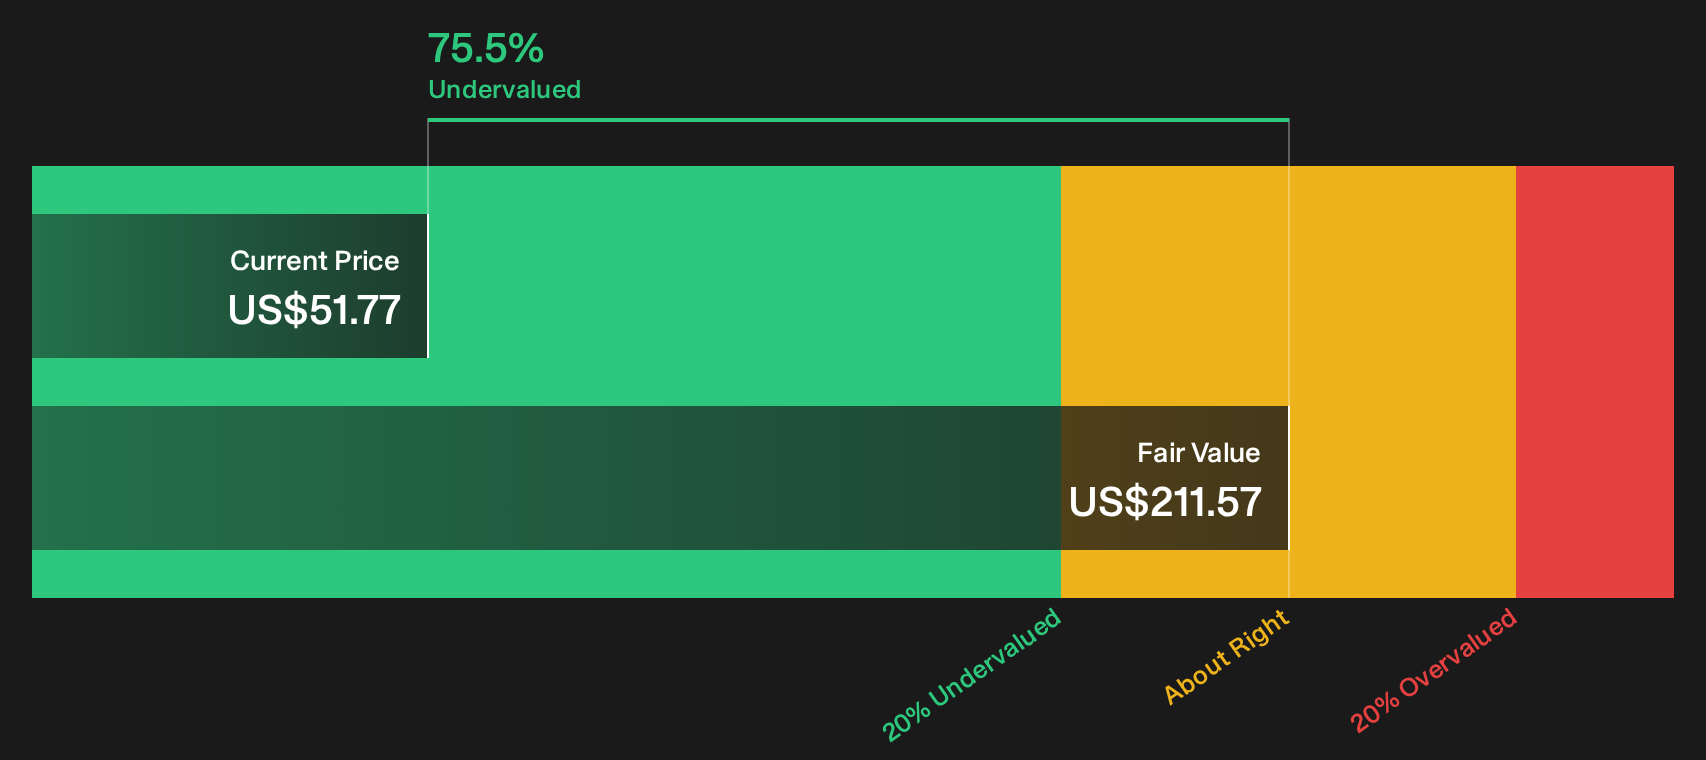
The SWS DCF model points to a large gap, with Delek Logistics Partners valued at $211.57 per unit on future cash flows compared with the current $51.77 price. That indicates deep undervaluation using this method and raises a simple question for you: is that spread an opportunity or just optimistic modelling?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
You have read a mix of optimism and concern around Delek Logistics Partners, and the balance between them will not stay static for long. Review the numbers, weigh the risks and rewards for yourself, and then dig into the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Delek Logistics Partners?
If Delek Logistics Partners has sharpened your focus on income and value, do not stop here. Your next strong idea could be one screener away.
- Target steady cash flow by reviewing a curated set of income opportunities in the 8 dividend fortresses built for investors who care about reliable payouts.
- Hunt for mispriced quality by scanning the 41 high quality undervalued stocks that highlight companies combining fundamentals with room for potential re rating.
- Prioritize resilience first and excitement second by filtering through 29 resilient stocks with low risk scores that focus on businesses with sturdier overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com