


EN
How Investors Are Reacting To Hudbay Minerals (TSX:HBM) Ahead Of Earnings
- Hudbay Minerals is preparing to report quarterly results on 12 November 2026, with analysts expecting higher earnings and revenue compared with a year earlier. Recent estimate revisions and past earnings variability are keeping attention on operating execution and costs.
- The final investment decision on the Copper World project in Arizona alongside Mitsubishi, together with brownfield work at Constancia, Copper Mountain and Snow Lake, highlights how Hudbay Minerals is attempting to build future copper output while managing fuel, consumables and labour pressures that have already pushed some site costs above guidance.
- We will now look at how Hudbay Minerals' investment narrative could shift as investors weigh mixed earnings expectations against upcoming results.
Hudbay Minerals Investment Narrative Recap
To own Hudbay Minerals, you need to be comfortable with a copper focused miner that is actively building future output while wrestling with near term cost and execution issues. The recent share price drop ahead of the 12 November earnings release keeps the short term focus firmly on whether management can keep site costs and labour under control while delivering the production it has guided to.
The biggest operational risk right now sits in persistent fuel, consumables and labour pressures that have already pushed some cash costs above guidance, especially in Peru and British Columbia. If those inputs stay elevated without offsetting metal prices or higher by product gold volumes, earnings could feel it. The upcoming quarterly report is the key near term catalyst because it will show how those pressures are flowing through cash costs, margins and free cash generation.
The Copper World final investment decision with Mitsubishi is the announcement that matters most in this context because it locks in a long dated growth project just as investors are questioning shorter term earnings momentum. Engineering is largely complete and first output is targeted for the second half of 2029. This is not an immediate volume swing, but it does frame where Hudbay Minerals is trying to take its copper profile.
For you, the key question is how that long term build out interacts with the near term earnings setup that has turned more cautious, with a negative Earnings ESP and only one beat in the last four quarters. A larger, U.S. anchored copper portfolio can change the revenue mix and production base over time. The payoff depends on keeping Copper World capital intensity in check, managing permitting phases cleanly and using existing free cash flow and the current balance sheet to fund the build without putting pressure on financial flexibility.
What The Current Forecasts Assume For Hudbay Minerals
Hudbay Minerals' narrative projects $3.6 billion revenue and $878.1 million earnings by 2029. This rests on 13.7% yearly revenue growth and an earnings increase of about $200 million from $678.2 million today.
Uncover how Hudbay Minerals' fair value indicates a 54% potential upside to its current price. This opportunity could narrow quickly if sentiment shifts.
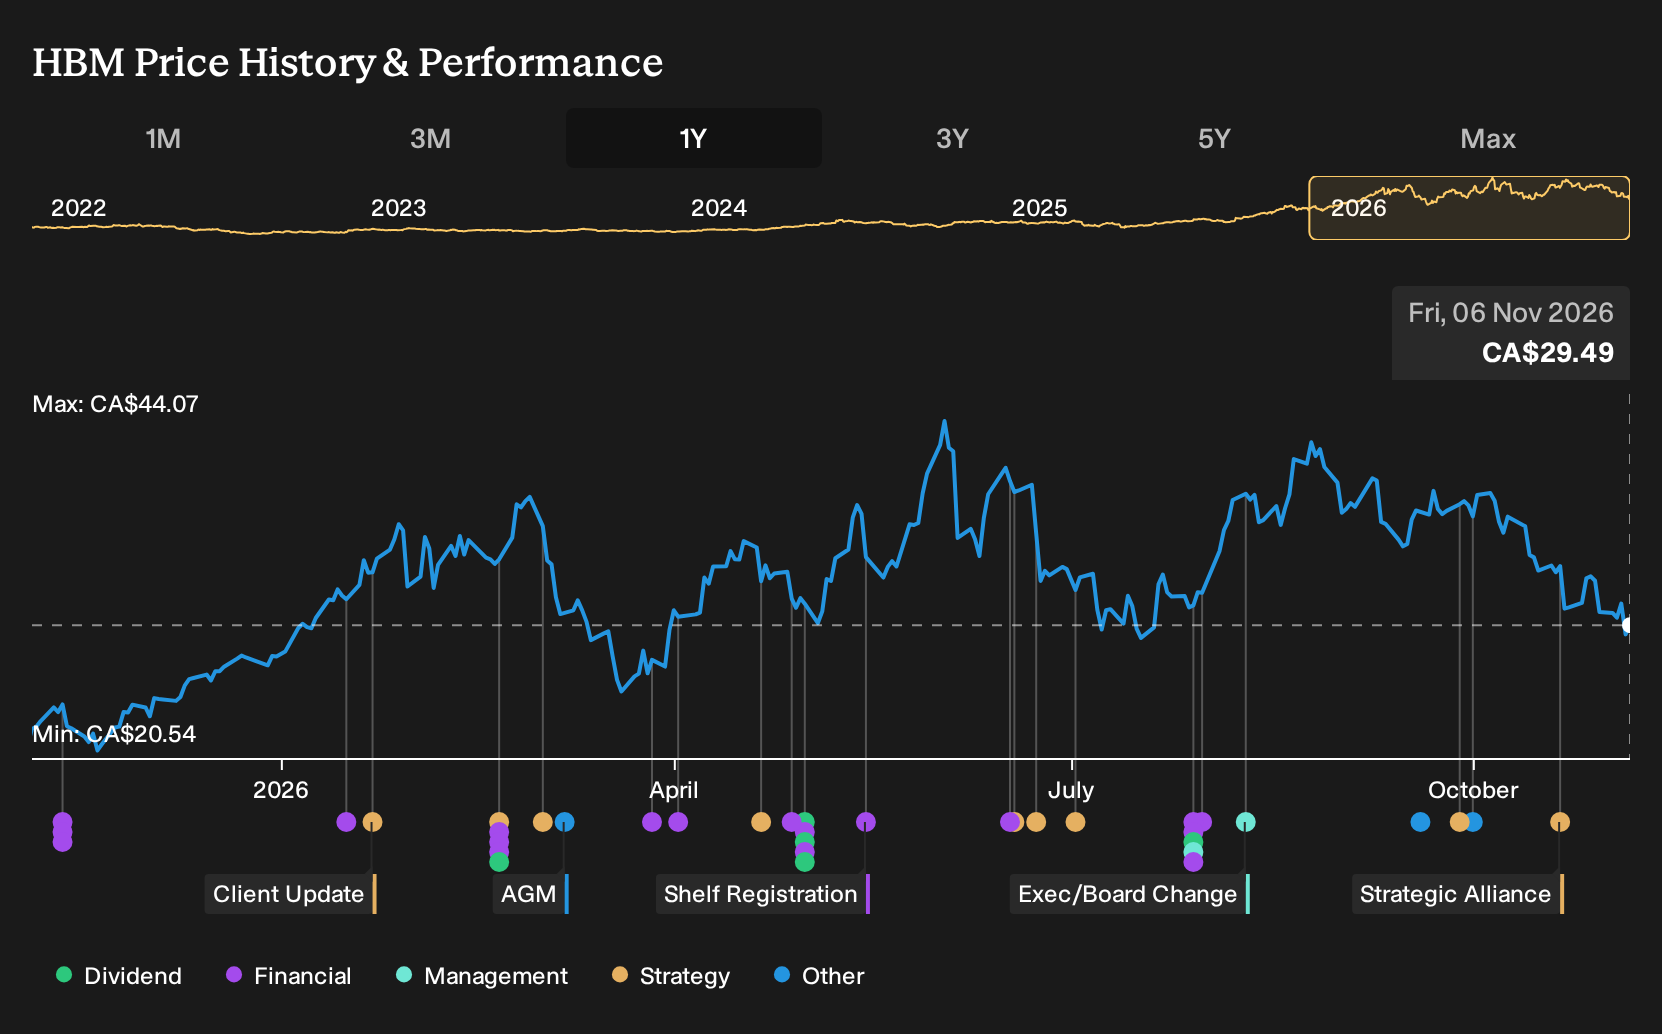
Exploring Other Perspectives
For Hudbay Minerals, the real tension point is earnings power. The most cautious analysts were pencilling in revenue of about $3.1b and only $452.8m of earnings by 2029, far below the $878.1m consensus path. That more pessimistic script could shift after the Copper World decision and the upcoming 12 November results, so treat this as a live debate and explore both sides.
Explore 4 other Hudbay Minerals fair value estimates, including one that suggests up to 59% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Hudbay Minerals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hudbay Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hudbay Minerals' overall financial health at a glance.
Looking For More Ideas Beyond Hudbay Minerals?
If Hudbay Minerals has you thinking about how copper exposure fits into your broader portfolio, it can help to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals, scan through 6 high quality undervalued stocks that already combine earnings power with balance sheets that are not stretched.
- If capital preservation matters more to you than chasing every swing, focus on 9 resilient stocks with low risk scores that score well on volatility and financial risk metrics.
- For readers aiming to complement copper exposure with steadier income, check out 3 dividend fortresses that may suit a more income focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com