


EN
Canadian Natural Resources (TSX:CNQ) Stock Price Slumps On Q3 Earnings Squeeze
Canadian Natural Resources came into this Q3 2026 earnings release with its stock near CA$68.50 and a 7 day slide of roughly 13%. The market has been treating the ticker like a value story trading on a low P/E multiple. Then the latest quarter landed with heavy profit compression.
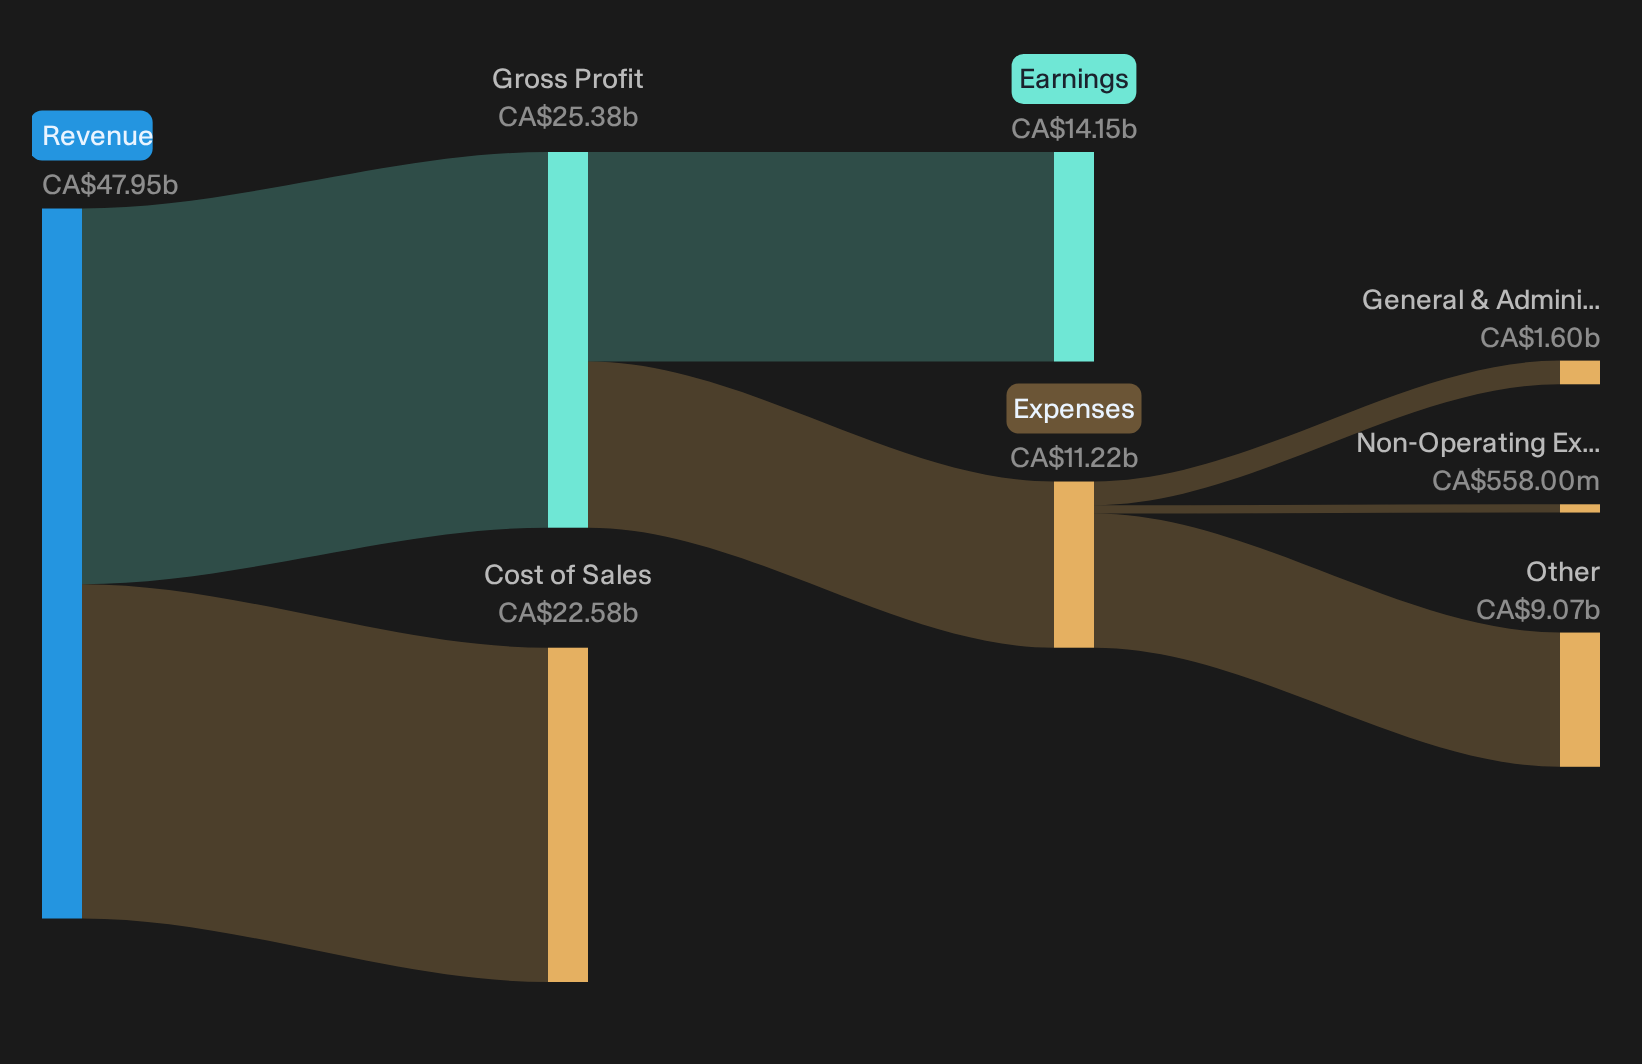
Basic earnings per share dropped to about CA$1.46 and net income slid to roughly CA$3.0b as lower total revenue met a high capital base. The price reaction looks like a blunt verdict on that squeeze, even as production and cash returns remain central to the long term thesis.
Like the income line but worried that Canadian Natural Resources is being treated as a simple value trap after this profit squeeze? Balance that thesis by screening for solid cash generation and strong balance sheets using the list of solid balance sheet and fundamentals stocks (5 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): CA$12,793m vs. CA$9,516m (up roughly 34%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): CA$2,997m vs. CA$600m (up sharply, around 5x)
- Basic EPS (Q3 2026 vs Q3 2025): CA$1.46 vs. CA$0.29 (up sharply, around 5x)
- Total Oil Equivalent Production (Q3 2026 vs Q3 2025): 122.09 MMboe vs. 127.40 MMboe (down about 4%)
Prefer clean visuals over scrolling through another wall of earnings tables for Canadian Natural Resources. See the full picture of the business, including how analysts frame the outlook after this profit compression, in our interactive company report for Canadian Natural Resources.
Canadian Natural’s Growth Projects Face a Reality Check
The bullish story rests heavily on visible thermal growth at Canadian Natural Resources and the idea that these projects steadily lift volumes and cash flow.
"Regulatory approval for the 70,000 barrel per day Pike 2 SAGD project, together with the 30,000 barrel per day Jackfish brownfield expansion and strong performance from the first Pike 1 pad, creates a visible queue of thermal growth projects that can add incremental volumes and support future cash flow growth."
Q3 results largely support this claim. Thermal in situ output hit a record ~300,000 bbl/d and Jackfish ran about 23,000 bbl/d above nameplate. Pike 1 pads produced ~46,500 bbl/d with a steam oil ratio of ~1.7x, which suggests the growth projects are not just approved on paper but are already contributing meaningfully to operating scale and efficiency.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Canadian Natural Results Versus Policy Risk Fears
The policy risk argument says future oilsands growth projects at Canadian Natural Resources could stall out under tougher carbon rules and regulatory delays.
"Deferral of the approximately $8.25b Jackpine Mine expansion because of unresolved regulatory policy on carbon and methane points to potential delays or cancellations of large growth projects. This could cap long term production growth and limit revenue expansion."
Q3 shows that concern is not resolved. Management still references Jackpine as paused and ties progress to government agreements and fiscal clarity. Record thermal in situ output and strong Horizon execution offset some of that growth anxiety, yet the key milestone is unchanged. Jackpine remains deferred, so the bearish policy overhang stays intact this quarter.
Hunt For Mispriced Cash Generators
Canadian Natural Resources just reminded investors how quickly a story can hinge on one compressed quarter. The real opportunity sits in spotting stocks that could be mispriced before sentiment catches up.
- Company 1 - 29% below our estimate - targets rapid paybacks from new boutiques while nudging shoppers toward higher margin digital channels.
- Company 2 - 34% below our estimate - folds acquired engineering teams into long duration infrastructure and water programs using shared digital and AI delivery hubs.
- Company 3 - 49% below our estimate - channels mine cash flows into new pits and underground projects supported by recent near site discoveries.
That is three of the list. See the full list of 6 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com