


EN
Innodata (INOD) Q3 Revenue Hit $95.62 Million
- Innodata (NasdaqGM: INOD) reported record year over year revenue growth for Q3 2026, topping analyst expectations.
- Management raised full year 2026 guidance following the quarterly update, signaling higher anticipated revenue for the period.
- The company announced new customer wins, including programs with a major hyperscaler and a fresh federal contract in AI and data services.
- The record Q3 2026 revenue jump, guidance hike, and new contracts are only part of the Innodata story. We have also spotted 1 warning sign worth knowing about at Innodata.
The stronger Q3 update highlights how AI infrastructure demand is evolving, which makes it worth exploring 52 AI infrastructure stocks.
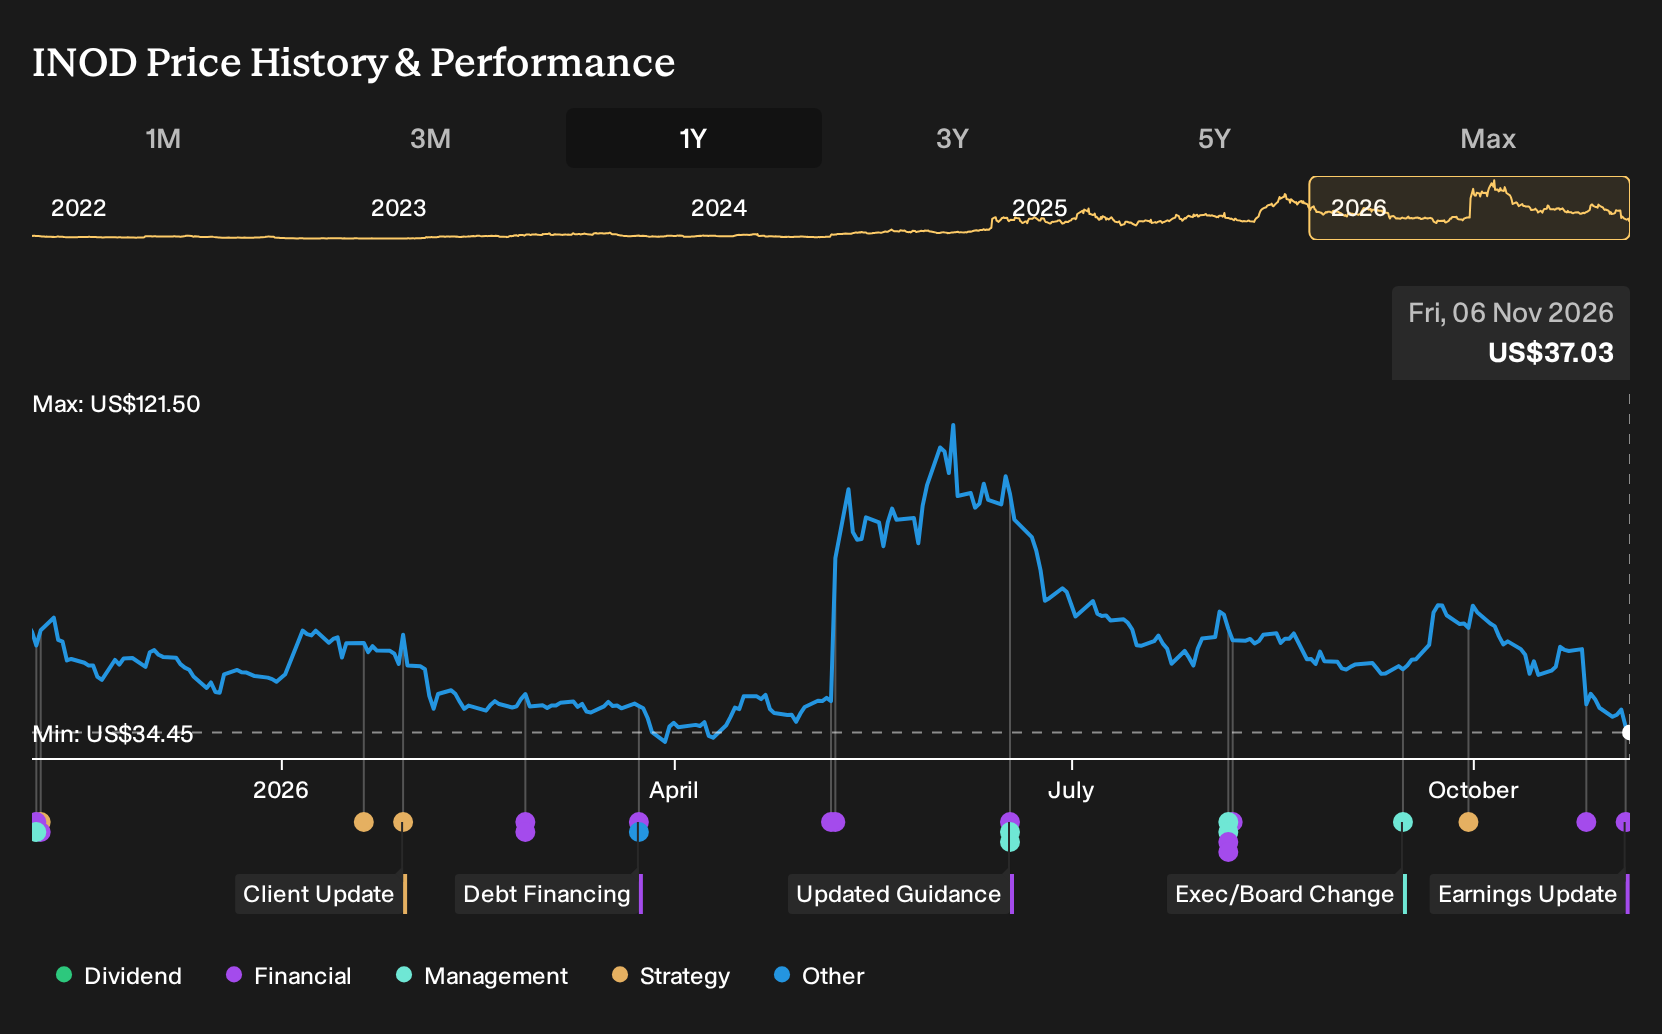
Innodata operates as a data engineering specialist within the Professional Services industry, supplying AI and data services across the US and several European markets. New work with a hyperscaler and a federal customer positions its offering squarely inside large scale digital infrastructure projects.
See which insiders are buying and selling Innodata following this latest news.
How strong was Innodata’s latest quarter in simple terms?
In Q3 2026, Innodata reported sales of US$95.62 million, compared with US$62.55 million a year earlier, and net income of US$10.33 million versus US$8.34 million. Basic EPS from continuing operations was US$0.30, while diluted EPS came in at US$0.29, compared with US$0.26 and US$0.24 respectively last year.
Does this Q3 news change the Innodata Narrative investors have been using?
The update leans into the existing Narrative rather than replacing it. Record revenue, higher full year guidance and new hyperscaler and federal programs sit squarely in the “AI infrastructure spend” and trust and safety catalysts that analysts already highlight, while the still premium P/E and customer concentration risks from that Narrative remain relevant for sentiment.
See how these catalysts shape Innodata's path to a $123 fair value.
What should investors watch next to see if this Innodata momentum is real?
The clearest early signal is whether the new hyperscaler and federal wins show up as sustained sales and earnings in the next few quarters, not just a one off spike. Numbers to watch are revenue and net income for Q4 2026 and the nine month trend, plus any further changes to management guidance.
The Innodata signal most holders miss sits quietly in the cash numbers
Shareholders often focus on headlines and quarterly beats while ignoring what the company’s own cash generation suggests about the value of the entire business compared with today’s share price. Find out exactly what Innodata is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com