


EN
Skeena Resources (TSX:SKE) Eskay Creek Progress Keeps Valuation Debate In Focus
Fresh interest in Skeena Resources (TSX:SKE) is tied to the Eskay Creek gold silver project, where investors are watching construction progress and funding plans that influence how the market values the miner.
Recent trading suggests momentum in Skeena Resources is building again, with a 1-day share price return of 5.88% and a 7-day share price return of 16.46%. The 1-year total shareholder return of 89.31% and very large 3-year total shareholder return hint that investors have been steadily repricing execution risk at Eskay Creek rather than reacting only to short bursts of news.
Scan how the Eskay Creek story compares with other precious metal developers by running your filters across our hand picked 33 elite gold producer stocks aligned with similar construction and funding catalysts.
The latest surge has already reset expectations around Eskay Creek, yet a CA$43.58 share price and ongoing funding work leave a simple tension: Has Skeena Resources already banked most of the upside, or not yet?
Preferred Price-to-Book of 32x for Skeena Resources: Is it justified?
Skeena Resources changes hands at a P/B ratio of 32x while the last close sits at CA$43.58. That is far richer than both peers and the broader Canadian metals and mining group, which signals that the market is already attaching a premium to Eskay Creek and the wider portfolio.
The price to book metric compares the equity value in the market to the accounting value of net assets on the balance sheet. For a developer like Skeena Resources with minimal current revenue and ongoing losses, most of the story is tied to future cash flows from projects rather than what historic cost accounting shows, so a clean read through this multiple is tricky.
Even with that caveat, a 32x P/B against a peer average of 4.2x and a sector average of 2.2x is a sharp gap. The valuation signals that investors are paying a much higher price for each dollar of book equity, which implies heavy confidence in future Eskay Creek economics and execution that is not reflected to the same extent in other metals and mining stocks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 32x (OVERVALUED)
Still, any stumble in securing funding on acceptable terms or setbacks at Eskay Creek could quickly challenge the premium valuation that Skeena Resources currently enjoys.
Find out about the key risks to this Skeena Resources narrative.
Another view on Skeena Resources using our DCF model
The market is treating Skeena Resources as expensive on a 32x P/B, yet our DCF model presents a different perspective. On that cash flow view, CA$43.58 is around 30% below an estimated future value of CA$62.27, which suggests a very different risk and reward profile.
Our DCF model relies on inputs such as 81.1% annual revenue growth and a path to profitability in the next 3 years. The key question is whether those assumptions seem robust enough to you to offset the headline P/B level.
Look into how the SWS DCF model arrives at its fair value.
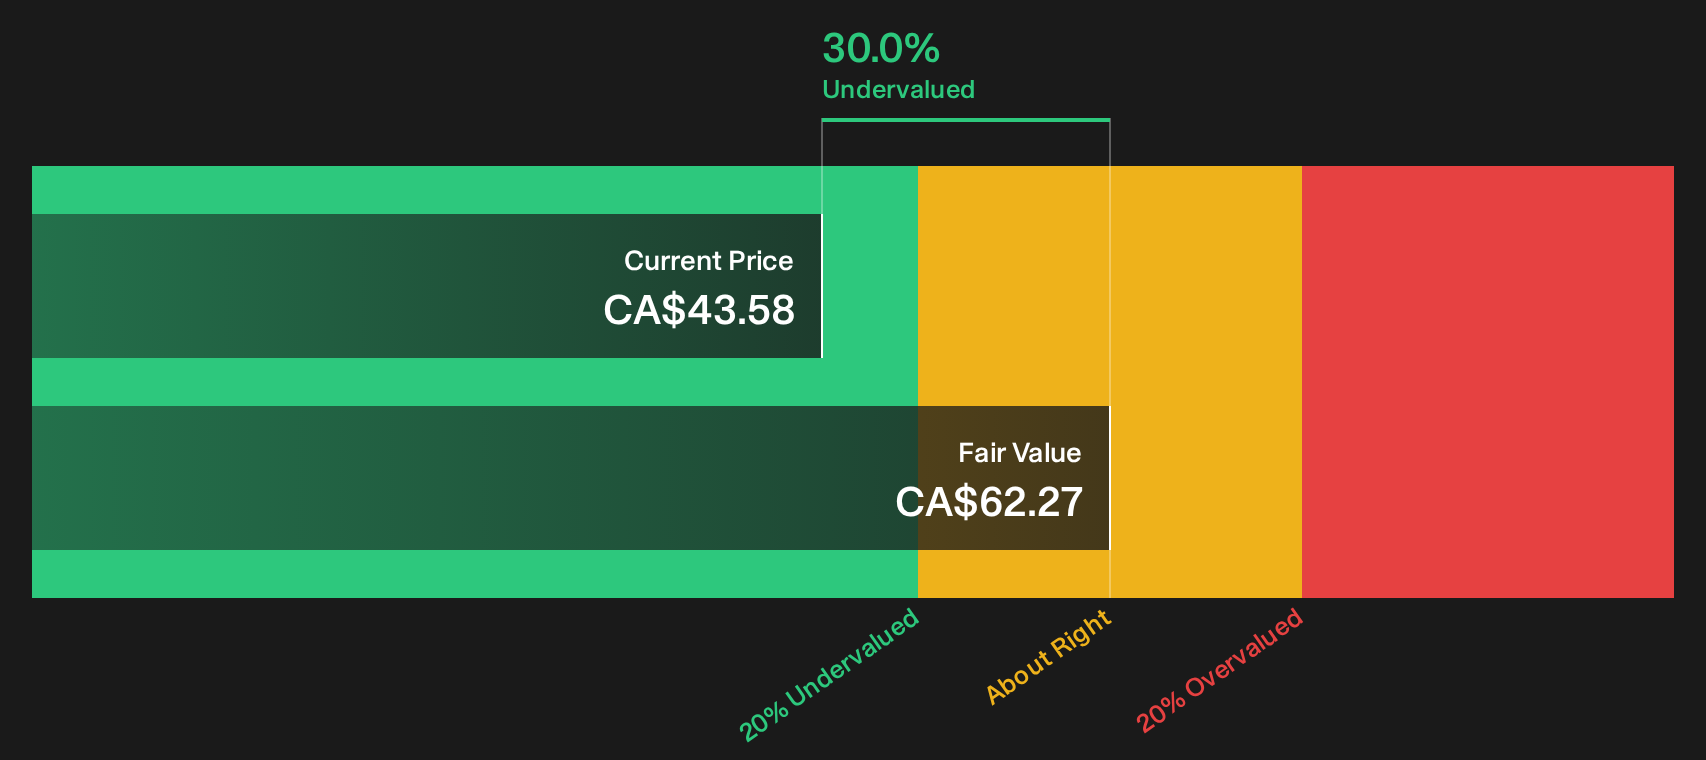
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Skeena Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed opinions remain on whether Skeena Resources still has room to run at CA$43.58 or already reflects the key Eskay Creek milestones. Act quickly, test the assumptions that matter most to you, and pressure test both sides of the story by checking the 3 key rewards and 3 important warning signs
Looking for more Skeena Resources sized ideas?
If Skeena Resources has your attention, do not stop here. Broader opportunities can sharpen your watchlist, stress test your thinking, and highlight alternatives.
- Hunt for quality at a discount by scanning the 6 high quality undervalued stocks that combine robust fundamentals with prices that trail their underlying metrics.
- Build staying power into your portfolio by reviewing the list of solid balance sheet and fundamentals (5 results) that may better handle shocks and funding cycles.
- Get ahead of the crowd by checking the 7 high quality undiscovered gems that pair strong financial profiles with relatively limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com