


EN
Silvercorp Metals Stock Faces El Domo Cost Overrun And Delay
- Silvercorp Metals reported past quarter results showing lower sales year on year, higher net income, and detailed cost and schedule revisions for the El Domo Project after diesel price changes, heavy rainfall, and additional power and water infrastructure needs.
- The combination of a higher El Domo construction budget, weather driven delays, and prolonged GC Mine downtime concentrates execution risk across Silvercorp Metals' growth pipeline and near term cash generation.
- We will now look at how Silvercorp Metals’ investment narrative is affected by the higher El Domo budget and delayed production start.
Compare how Silvercorp Metals' risk reward mix stacks up against other precious and base metal producers by scanning our hand picked 10 top silver producer stocks for potential alternatives in the same space.
Silvercorp Metals Investment Narrative Recap
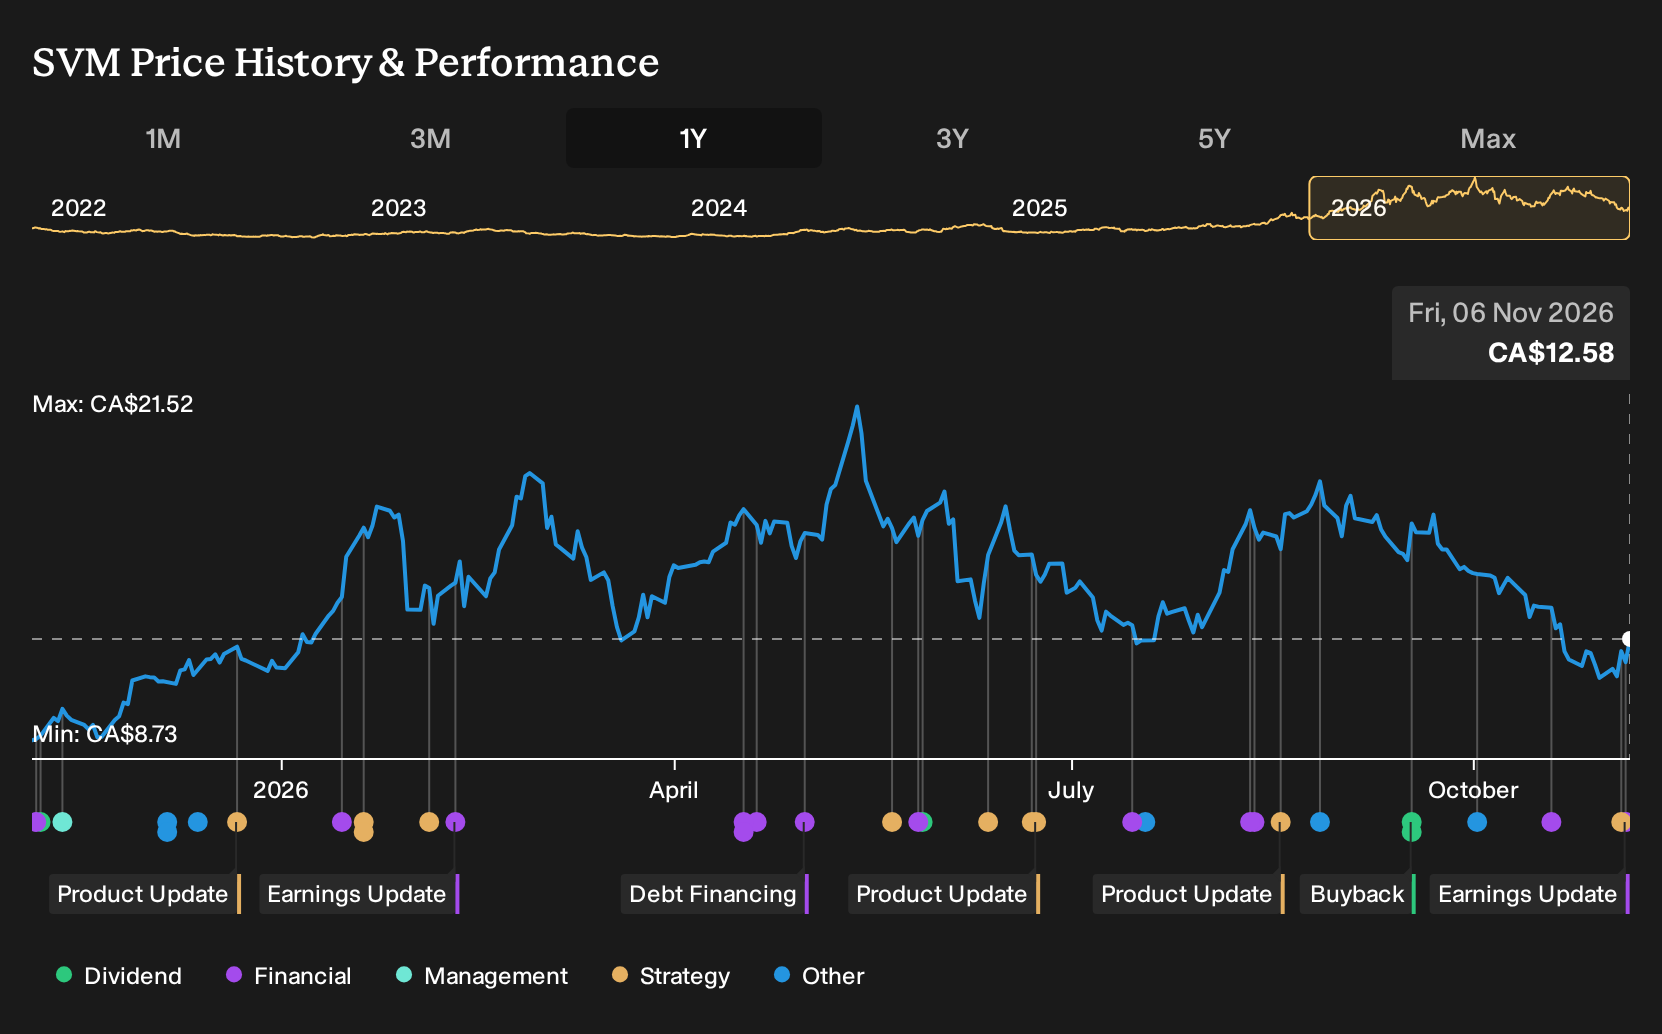
To own Silvercorp Metals today, you need to be comfortable with a story that leans heavily on turning recent operational disruption into more stable production while funding large growth projects. The latest quarter showed lower sales of US$72.1 million versus US$83.33 million a year earlier, but swung from a US$11.52 million loss to a US$5.32 million profit, which helps support that thesis.
In the short term, the key catalyst is execution at the Ying district and progress on El Domo, because GC Mine cash flow is off the table until at least late 2027. The biggest current risk is that higher construction costs, weather delays, and extended GC downtime keep straining cash generation while capital needs stay high.
The updated El Domo budget and schedule announcement is the most relevant development here. Construction costs are now projected at US$298.2 million, up US$14.6 million, with diesel subsidy removal, heavier rainfall, and extra power and water infrastructure all pushing required spend higher despite some offsetting reductions elsewhere.
That same update also pushed the targeted El Domo production start to November 2027 and flagged potential higher operating costs if powerline approvals keep lagging and the project relies on gen sets for longer. For you as a shareholder, this clusters timing risk, country risk, and cost risk around a single project that is central to Silvercorp Metals’ diversification beyond China.
Silvercorp Metals’ current analyst storyline points to revenues of $504.4 million and earnings of $143.0 million by 2028, based on assumed 17.9% yearly revenue growth and an earnings increase of about 2.6x from $54.4 million today.
Discover how Silvercorp Metals' fair value indicates a 37% potential upside to its current price that could close faster than you expect.
Exploring Other Perspectives
One alternate view around Silvercorp Metals focuses less on El Domo timing and more on long term earnings quality. The most pessimistic analysts were already baking in heavy execution and regulatory friction, even while modeling revenue at about $1.2b and earnings near $1.0b by 2029. Those projections came before this budget and delay update, so your own read on risk may differ a lot.
Explore 4 other Silvercorp Metals fair value estimates, including one that suggests it could be worth just CA$17.22!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Silvercorp Metals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Silvercorp Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Silvercorp Metals' overall financial health at a glance.
Looking for more investment ideas beyond Silvercorp Metals?
Once you are comfortable with where Silvercorp Metals fits in your portfolio, it often helps to line it up against a wider bench of opportunities using the Simply Wall St Screener.
- If you want potential value coupled with quality, scan a curated set of 6 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- For investors who care most about balance sheet strength, focus on the list of solid balance sheet and fundamentals (5 results) to see businesses where low leverage and solid finances are front and center.
- When you are hunting for ideas that the market may be overlooking, cast a wider net with a 7 high quality undiscovered gems that filters for under-the-radar companies with robust underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com