


EN
BorgWarner (BWA) Wins New EV Contracts, Is The Valuation Gap Enough?
BorgWarner (BWA) has paired a modest trim to its 2026 sales outlook with a string of fresh client wins across electric and hybrid programs, giving investors new data points to reassess the stock.
At a share price of US$48.81, BorgWarner has seen short term momentum fade, with a 30 day share price return down 21.73% and a 90 day move lower by 28.66%. This comes even though the 1 year total shareholder return sits at 9.94% and the 3 year total shareholder return reaches 56.83%.
Scan other electrification suppliers showing similar contracts and price dislocations by tracking our curated list of 52 AI infrastructure stocks together with BorgWarner’s latest guidance cut and EV program wins.
The share price reset and mixed 2026 outlook leave BorgWarner looking cheaper on the surface. Does that shift the risk reward in favour of buyers, or suggest the discount is deserved as valuation comes under the microscope next?
Most Popular Narrative: 38% Undervalued
BorgWarner’s most followed valuation storyline pegs fair value near $79.07 against the latest close at $48.81. This puts a wide gap between where the shares trade and what this narrative implies they could be worth when its thesis plays out.
The central execution test is whether BorgWarner can sustain structural margin gains while ramping its data center focused turbine generator and broader industrial portfolio, and managing the drag from its battery business.
The distributed power and turbine generator opportunity is viewed as a credible way for BorgWarner to diversify earnings beyond the auto cycle, including applications tied to AI data center power needs.
See why 24 investors see BorgWarner as 38% undervalued.
Result: Fair Value of $79.07 (UNDERVALUED)
Still, a faster shift away from combustion engines, or a more difficult transition away from batteries, could leave BorgWarner’s traditional profit pools and long term margin story under pressure.
Find out about the key risks to this BorgWarner narrative.
Another View: BorgWarner On Earnings Multiples
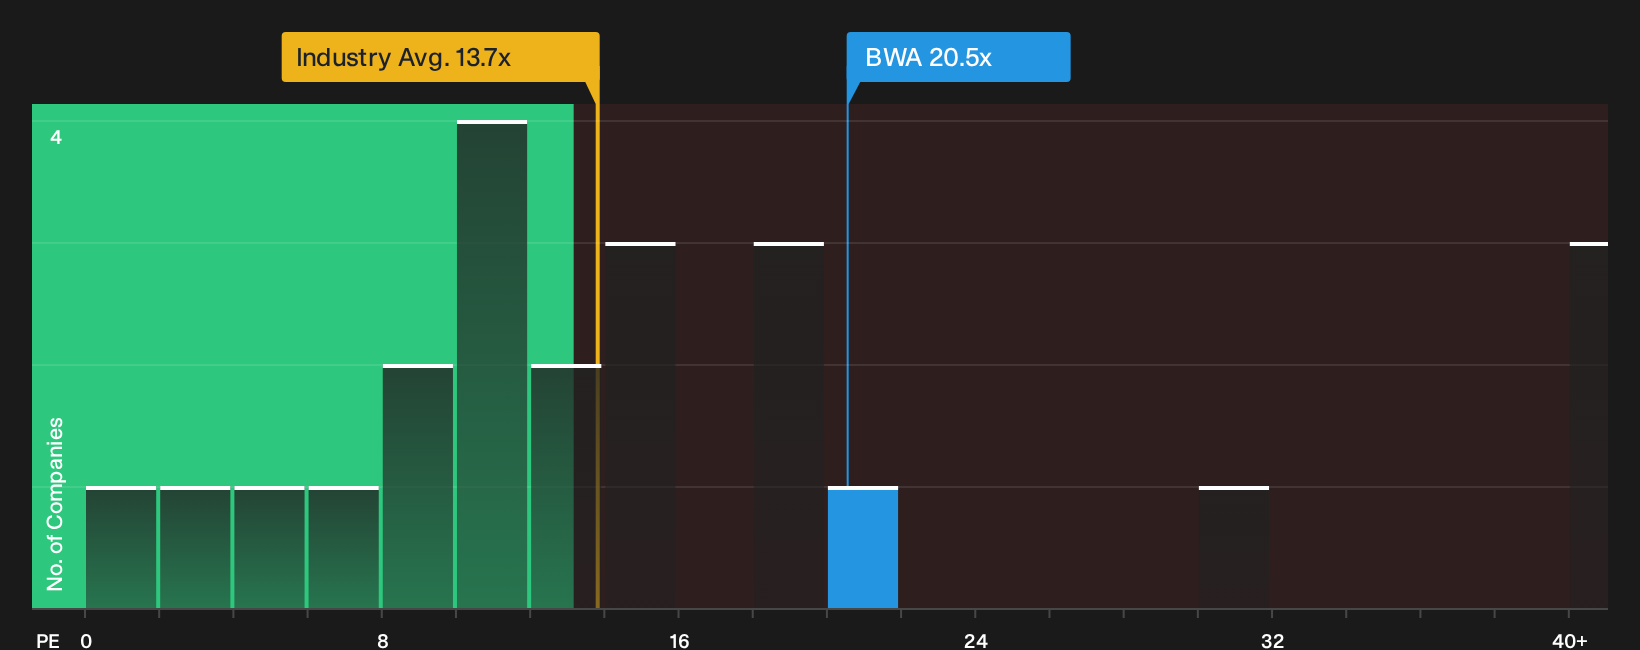
The story looks very different when BorgWarner is viewed through its P/E ratio rather than that US$79.07 fair value estimate. The shares trade on 20.5x earnings, compared with 13.7x for the US Auto Components group and 10x for peers, while the fair ratio sits nearer 16.4x.
That premium suggests investors are already paying up versus the sector and what the fair ratio implies the market could move towards. This raises a simple question for anyone running the numbers: Is this gap a margin of safety story, or a sign that expectations leave less room for disappointment?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around BorgWarner can feel messy, so move quickly, pull up the data that matters most, and weigh the 4 key rewards and 3 important warning signs for yourself.
Looking for more investment ideas beyond BorgWarner?
If BorgWarner has you thinking about pricing gaps and opportunity, do not stop at a single ticker. Broader idea hunting usually sharpens your decisions.
- Target potential mispricing by scanning a curated field of 41 high quality undervalued stocks that pair stronger fundamentals with more appealing entry points.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with sturdier financial footing.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems before attention and capital possibly rush in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com