


EN
Jacobs Solutions (J) Lands New Zealand Highway Role, Is The Stock Still Trading At A Discount?
Jacobs Solutions (J) just secured a major role on New Zealand's Warkworth to Te Hana Ara Tūhono highway project, a public private partnership that the government values at about US$2.1b.
Investors have been weighing this New Zealand win alongside a string of recent contract announcements, including new work with American Electric Power and San Francisco Public Utilities Commission. Jacobs Solutions’ share price has returned 9.2% over the past 30 days, while the 1 year total shareholder return has declined 1.9%. The 3 year total shareholder return is 38.1% and the 5 year total shareholder return is 29.2%, which points to longer term momentum that contrasts with the recent softer patch.
Scan other infrastructure focused plays benefiting from large capital projects with our hand picked 42 power grid technology and infrastructure stocks as a starting universe alongside Jacobs Solutions.
After a 9.2% one month share price gain and a mixed recent return profile, Jacobs Solutions now presents a clearer question for investors: Does the current valuation still leave enough upside to justify fresh risk?
Most Popular Narrative: 8% Undervalued
Jacobs Solutions last closed at $148.90, while the most followed narrative sees fair value at about $162.53. This frames today’s price as a discount that depends on strong execution on long contracts to close.
Record backlog of about US$29b with a trailing 12 month book to bill of 1.4x on gross revenue and 1.2x on net revenue points to multi year conversion of existing awards into revenue growth that many investors may not be fully pricing into Jacobs Solutions earnings power.
See why 21 investors see Jacobs Solutions as 8% undervalued.
Result: Fair Value of $162.53 (UNDERVALUED)
Still, if government infrastructure budgets tighten or AI data center orders prove shorter cycle than expected, the Jacobs Solutions backlog story could appear less secure.
Find out about the key risks to this Jacobs Solutions narrative.
Another View: Jacobs Solutions On Earnings Multiples
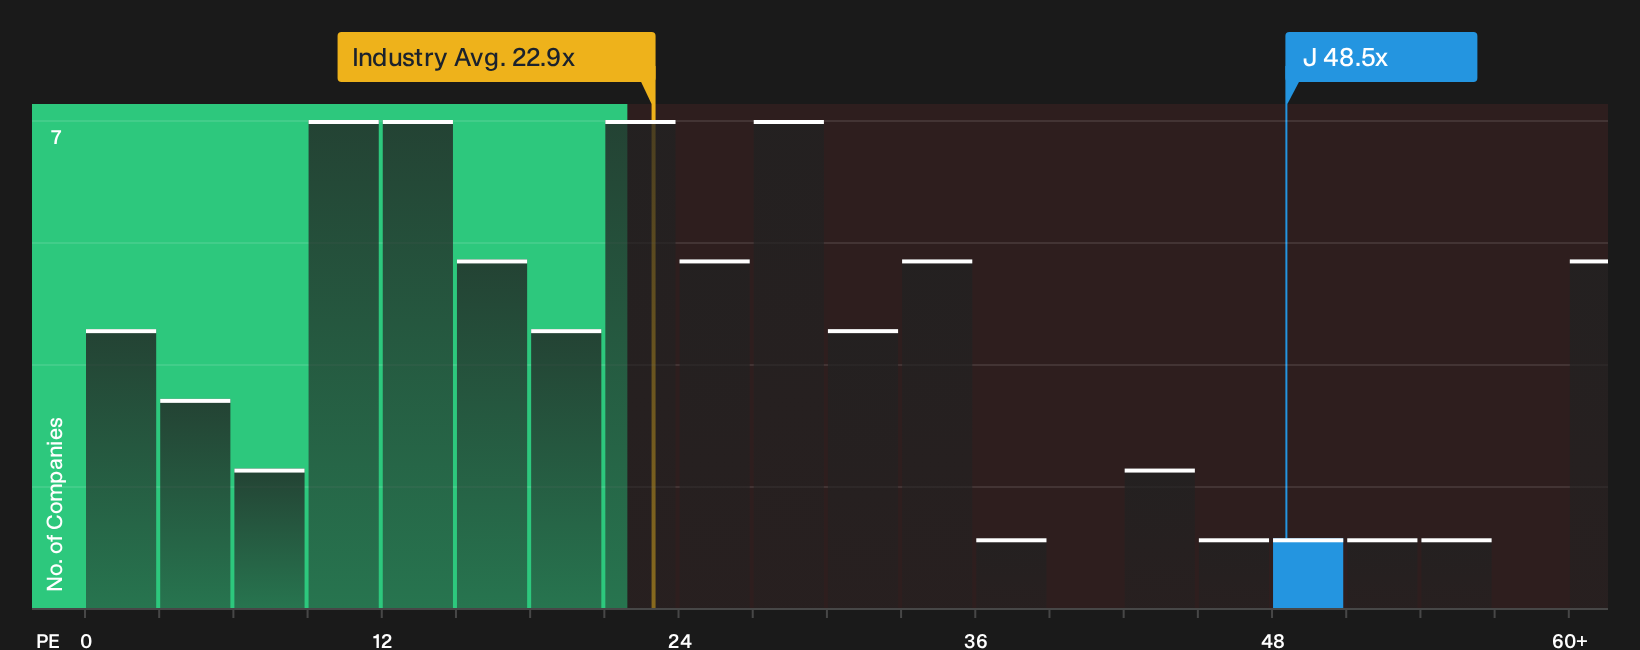
The narrative points to Jacobs Solutions trading below an estimate of future cash flow value, yet the P/E ratio tells a tougher story. At about 48.5x earnings versus 22.9x for the US Professional Services group and a 33.8x fair ratio, the stock carries valuation risk if expectations ease.
That wide gap on earnings multiples raises a simple question for investors. Is the discount to future cash flows enough to offset paying more than peers on current profits? Or is patience warranted until the P/E moves closer to the fair ratio that the market could drift toward over time, especially if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Jacobs Solutions story so far. If you want your conclusion to be grounded in your own work, pull up the key numbers, pressure test the assumptions, and see how they stack up against the 2 key rewards and 3 important warning signs.
Looking for more Jacobs Solutions style ideas?
If you want to keep your edge and not leave potential opportunities on the table, broaden your watchlist with a few focused stock idea sets built from clear fundamentals.
- Hunt for quality at a discount by scanning our hand picked 41 high quality undervalued stocks that pair stronger fundamentals with prices that some investors may be overlooking.
- Strengthen the income side of your portfolio by reviewing 8 dividend fortresses screened for higher yields and more robust cash support.
- Dial down portfolio stress and concentrate on resilience by working through the 30 resilient stocks with low risk scores that clear stricter balance sheet and risk filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com