


EN
Zalando (XTRA:ZAL) Could Be 27% Undervalued Following 2026 Guidance Reassurance
Zalando (XTRA:ZAL) has kept its full year 2026 guidance intact, even after reporting a net loss in the third quarter. This puts fresh attention on its logistics focused B2B operations.
Recent moves in Zalando’s share price tell a mixed story. The stock has climbed with a 22.47% 30 day share price return and a 12.27% 90 day share price return, while the 24.24% 1 year total shareholder return contrasts with a much weaker 5 year total shareholder return of 64.29%.
Compare Zalando’s guidance-driven story with other retailers by scanning our 227 high quality undervalued stocks that combine earnings power with balance sheet strength.
The share price rebound, combined with a recent net loss and confirmed 2026 guidance, raises a simple question: Does Zalando’s current valuation still skew the risk and reward in favour of new buyers?
Most Popular Narrative: 21% Undervalued
Against a last close of €27.63, the most followed narrative pegs Zalando’s fair value at €35.07. This frames the recent share price rebound as only a partial catch up to its modeled future cash flows.
The acquisition and integration of ABOUT YOU, together with identified synergies in commercial terms, logistics, marketing procurement and shared infrastructure, is planned to deliver around €40 million in annual synergies in 2026 and further efficiencies from payment and logistics consolidation through 2028, which directly targets higher net margins and group earnings.
See why 61 investors see Zalando as 21% undervalued.
Result: Fair Value of €35.07 (UNDERVALUED)
Still, the Zalando narrative can be knocked off course if sneaker demand stays weak for longer or if heavy AI and logistics spending fails to cut costs as intended.
Find out about the key risks to this Zalando narrative.
Another View: Zalando Looks Expensive On Earnings
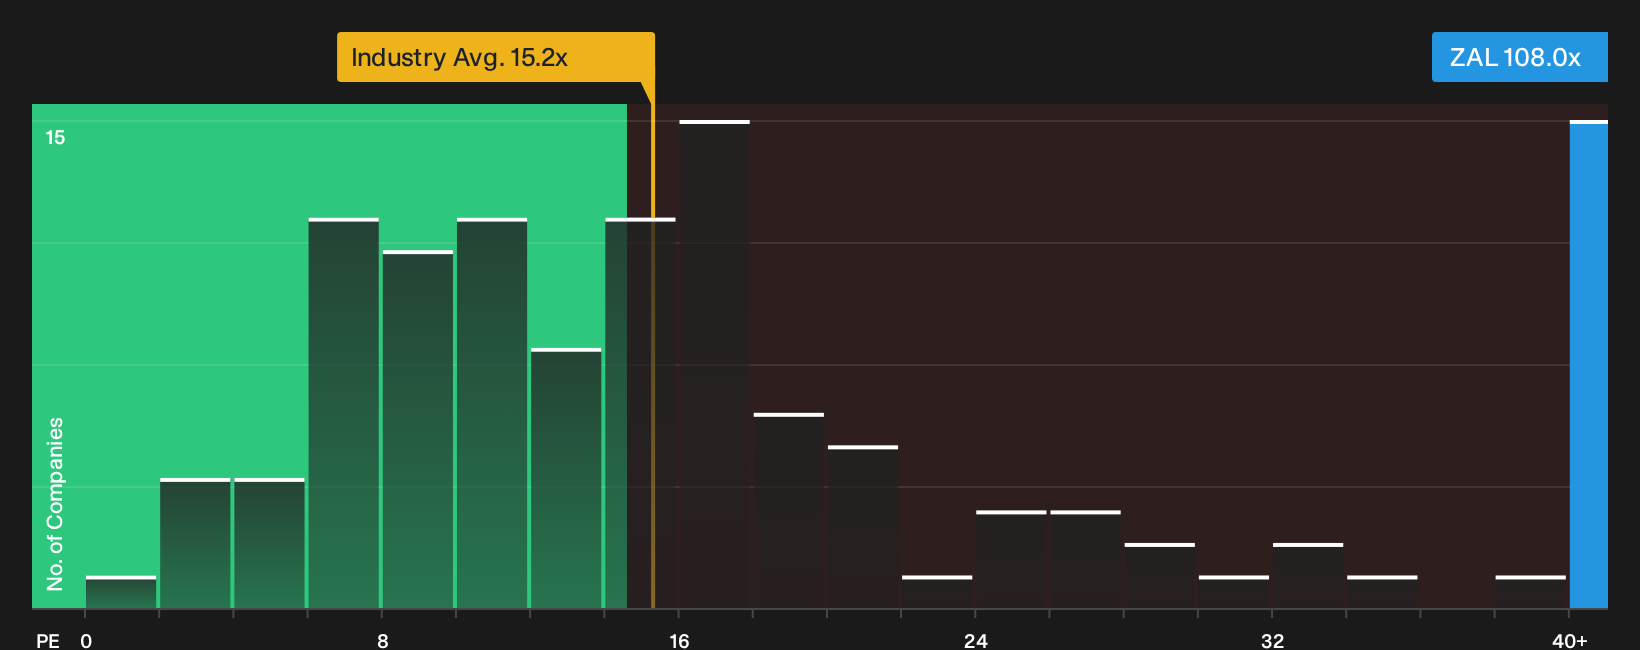
The story changes when you swap cash flow models for a simple earnings lens. On a P/E of 107.6x versus a European Specialty Retail average of 15.2x and a fair ratio of 25.6x, Zalando carries a heavy valuation premium that raises clear downside risk if expectations slip.
That gap between today’s rich multiple and the lower fair ratio points to a very different kind of risk reward skew than the DCF output suggests. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and sentiment do not have to leave you on the fence. Take a moment to review the numbers, weigh the trade offs and then decide where you stand using the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Zalando?
If Zalando has sharpened your focus on valuation and quality, do not stop here. Cast the net wider and stress test your thinking against fresh opportunities.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (192 results).
- Hunt for quality at a discount by reviewing our 227 high quality undervalued stocks.
- Build a cash flow focused watchlist by checking companies in our 232 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com