


EN
Earnings Growth Might Change The Case For Investing In IDEX Stock (IEX)
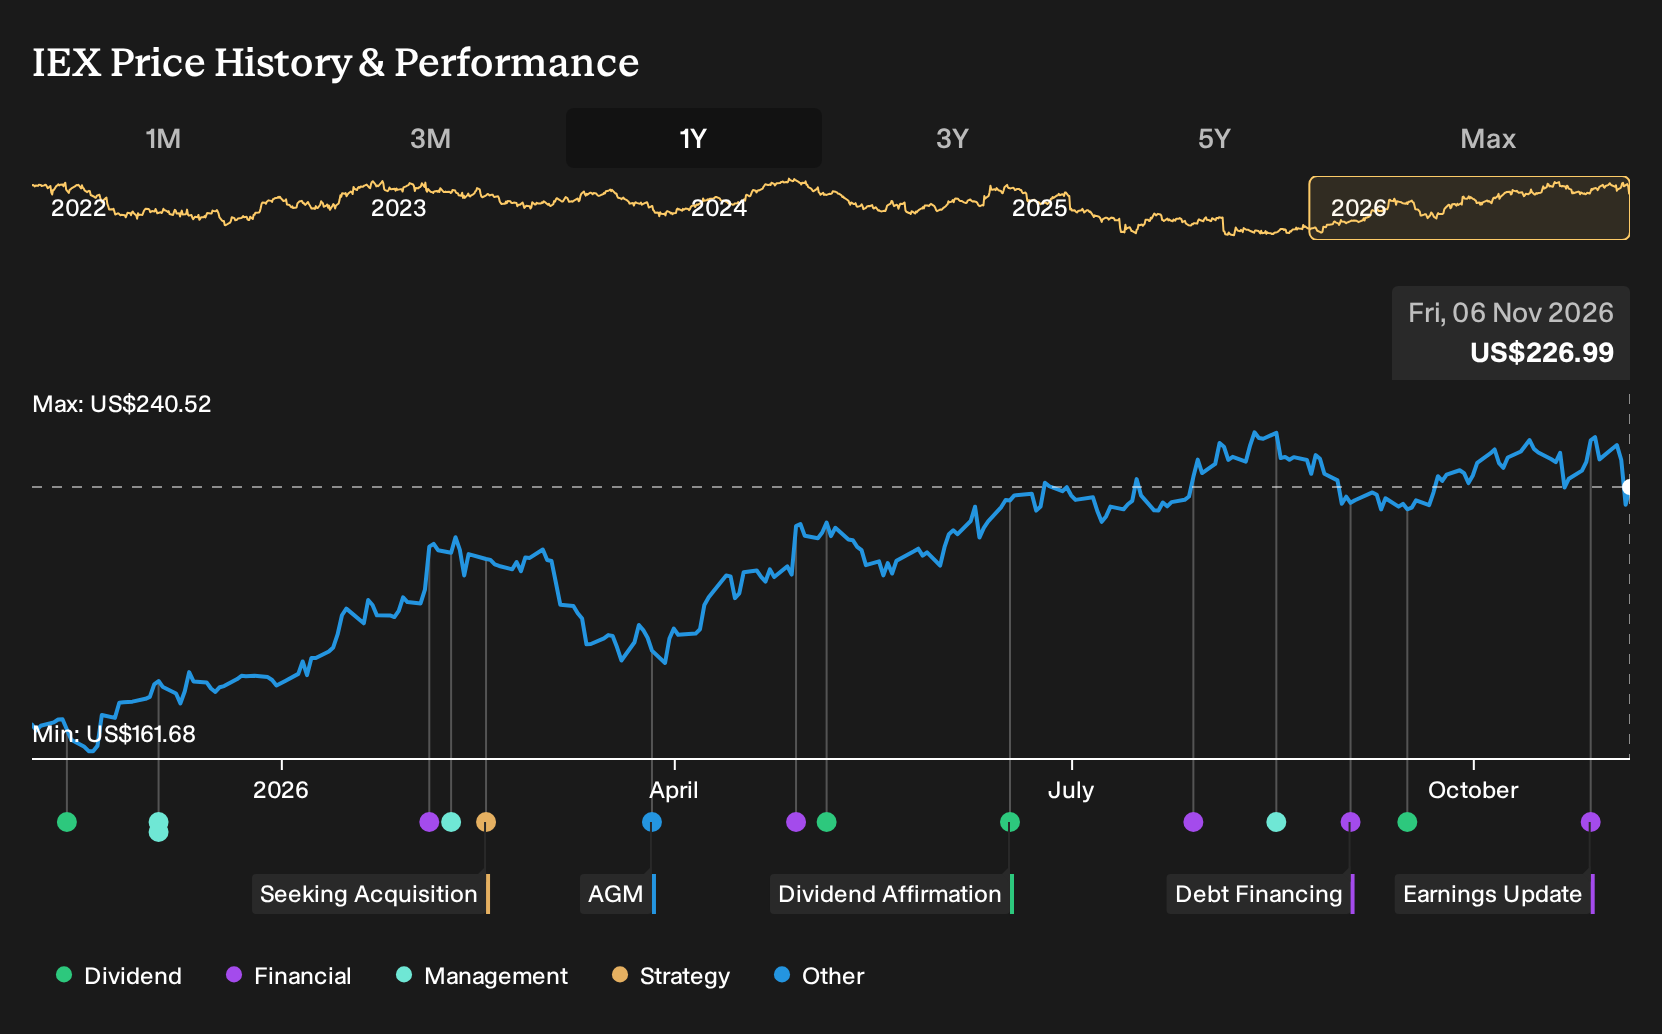
- IDEX Corporation reported third quarter 2026 sales of US$951.7 million and net income of US$144.1 million, with basic and diluted EPS from continuing operations of US$1.95, and nine month sales of US$2,759.2 million and net income of US$407.5 million.
- The latest figures show IDEX lifting both sales and earnings compared with the same periods in 2025, which puts fresh focus on how its mix of industrial and specialty solutions is translating into profitability over the year to date.
- Investors will now be watching how IDEX's higher earnings per share from continuing operations might influence the existing investment narrative around its growth focus.
Scan how IDEX's latest earnings compare with peers by lining it up next to 41 high quality undervalued stocks that also pair strong balance sheets with robust cash generation.
IDEX Investment Narrative Recap
IDEX investors need to believe that the push into higher value applications like data centers, semiconductors and space and defense can keep turning into healthier earnings while legacy areas do not drag too hard on margins. The latest quarter supports that narrative, with higher sales and net income for both Q3 and the first nine months of 2026.
The key short term swing factor is how quickly the record backlog and HST oriented capacity spending convert into revenue and cash flow without creating execution bottlenecks. The main risk remains any sharp pullback in orders or policy shocks that interrupt current demand and expose the business to more earnings volatility.
The Q3 2026 earnings release is the clearest operational update against that backdrop. Sales reached US$951.7 million for the quarter and US$2,759.2 million for the first nine months of 2026, while net income came in at US$144.1 million and US$407.5 million for those periods. Basic EPS from continuing operations was US$1.95 and US$5.50 respectively.
For a shareholder, those figures matter because they touch on several catalysts that were already in focus. They speak to whether the 80/20 methodology, HST mix shift and elevated capital expenditure are flowing through to earnings, and whether IDEX can keep funding dividends and buybacks while still managing policy and end market risks that could destabilise orders and margins.
IDEX's analyst narrative points to revenue of US$4.6b and earnings of US$815.7m by 2029, based on assumed 7.6% yearly top line growth and an earnings increase of about US$279.9m from current earnings of US$535.8m.
Uncover why IDEX's fair value indicates a 16% potential upside to its current price, before that discount narrows on stronger conviction in the IDEX story.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$262.93 and US$287.29, which signals a tight band of expectations around IDEX despite very different individual inputs. When you set those views against policy risk, order volatility and capital spending plans, you can see why opinions differ so widely. Explore more of them.
Explore another IDEX fair value estimate, including one that suggests it could be worth just $262.93.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your IDEX research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for IDEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDEX's overall financial health at a glance.
Looking for more investment ideas beyond IDEX?
If the IDEX story has sharpened your sense of what you want from a business, use that same filter across the wider market with the Simply Wall St Screener and build a watchlist that really matches your style.
- For investors who care most about quality at a sensible entry point, start by scanning a 41 high quality undervalued stocks that combine solid fundamentals with attractive pricing signals.
- If capital preservation ranks high on your list, focus on a 30 resilient stocks with low risk scores where balance sheets, earnings stability and volatility scores all work in your favour.
- When you want to go beyond the usual tickers and hunt for underfollowed opportunities, filter through a 19 high quality undiscovered gems that pair strong financials with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com