


EN
West Pharmaceutical Services (WST) Raises 2026 Outlook On Earnings Strength As Fair Value Debate Builds
West Pharmaceutical Services (WST) just posted third quarter figures that showed higher sales and net income versus a year earlier, raised its full year 2026 outlook, and completed a fresh tranche of share repurchases.
Against that backdrop, West Pharmaceutical Services has seen its share price move sharply over the past year, with a 30 day share price return of 9.09% and a year to date share price return of 44.65%. The 1 year total shareholder return sits at 47.97%, suggesting momentum has been building even as the 5 year total shareholder return is slightly negative at 3.41%. Shorter term swings, such as the 7 day share price return of 3.10%, reflect investors digesting the upgraded 2026 outlook, the recent buyback activity and the new credit facility.
Surf 19 high quality undiscovered gems that, similar to West Pharmaceutical Services after its upgraded 2026 outlook and buyback activity, combine solid fundamentals with strong recent momentum.West Pharmaceutical Services now couples a long established drug delivery franchise with a sharply rerated share price after its guidance lift and buyback. The key question is whether that quality is already fully reflected in today’s valuation.
Most Popular Narrative: 15% Undervalued
West Pharmaceutical Services last closed at $399.81, while the most followed narrative anchors fair value at $471. That gap frames the current debate around whether recent earnings strength and GLP-1 momentum are fully priced in.
The continued growth in GLP-1s, which made up about 10% of West Pharmaceutical Services revenues in the second quarter and are expected by management to grow at a high teens rate for the full year, together with participation in generic GLP-1 launches in multiple countries, could support revenue growth and earnings as higher value elastomer components are supplied into a broader therapy base.
The increase in demand and the transition to higher margin HVP components, supported by almost 800 Annex 1 and other upgrade projects and an estimated pool of roughly 6 billion eligible components with emerging interest in Annex 1 like upgrades in the U.S., is likely to positively impact both revenue and net margins through a sustained mix shift into higher value finishing and inspection services.
See why 16 investors see West Pharmaceutical Services as 15% undervalued.
Result: Fair Value of $471 (UNDERVALUED)
Still, the West Pharmaceutical Services story can unravel if high value GLP-1 demand cools, or if the premium P/E multiple resets on any earnings hiccup.
Find out about the key risks to this West Pharmaceutical Services narrative.
Another View: What Multiples Say About West Pharmaceutical Services
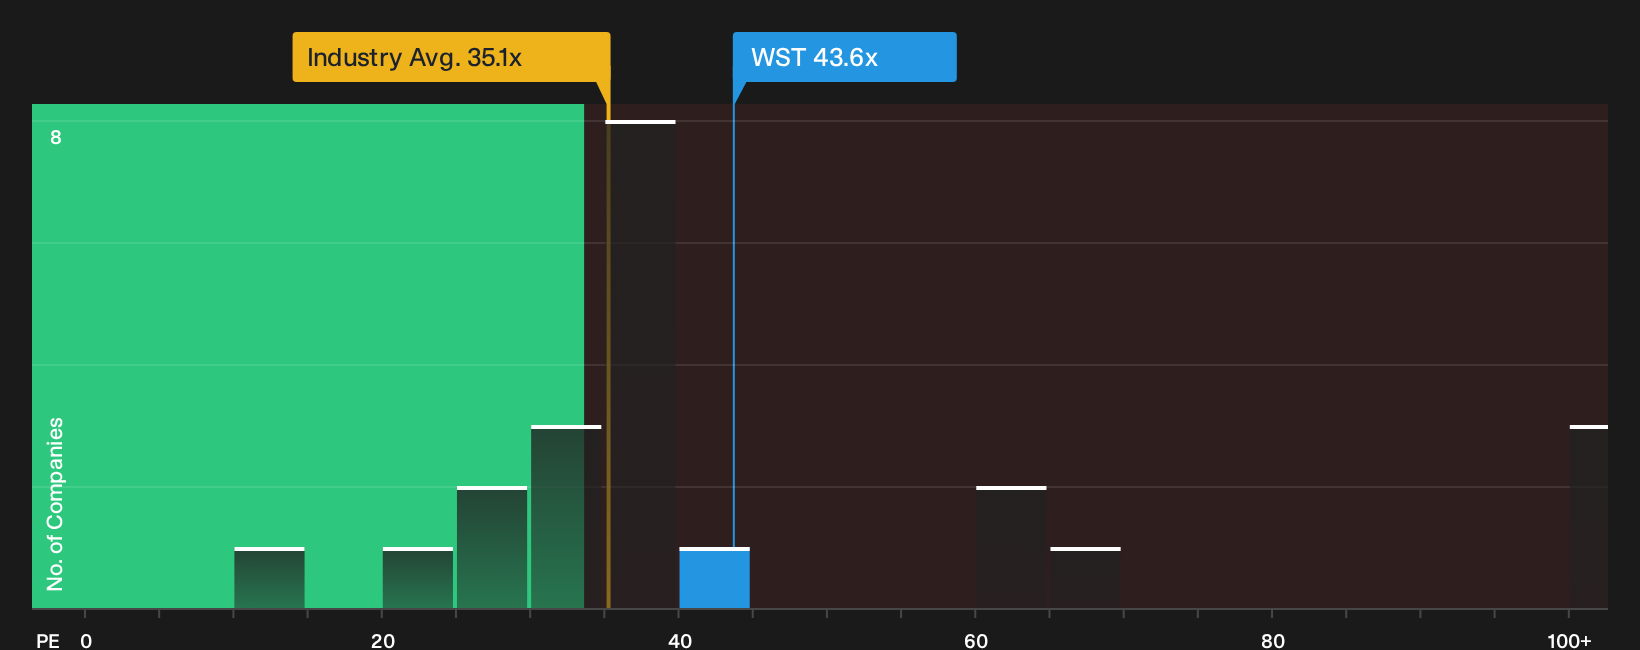
The first narrative leans on analyst targets and future earnings to claim West Pharmaceutical Services looks about 15% undervalued at a fair value of $471. Yet on simple P/E math, the picture tilts the other way.
At around 43.6x earnings, WST trades above the Global Life Sciences industry on 35.1x and even edges past its peer average of 43.4x. It also sits well above an estimated fair ratio of 24.5x, which is the level the P/E could move toward if sentiment cools. That kind of gap raises a practical question for you as an investor: Is this quality story worth paying such a rich headline multiple for, or does it leave less room for error if the growth narrative softens?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Whether you feel optimistic or cautious after looking at West Pharmaceutical Services so far, you can move quickly from headline narratives to your own data driven view by checking the 2 key rewards.
Looking for more investment ideas beyond West Pharmaceutical Services?
If West Pharmaceutical Services has sharpened your focus on quality, do not stop there. Use the tools available to widen your opportunity set across markets.
Step into income potential by scanning for resilient yield payers through 8 dividend fortresses that could complement a growth heavy portfolio.
Hunt for quality at a sensible price and let valuation work harder for you with the 41 high quality undervalued stocks.
Prioritise resilience and sleep easier at night by filtering for steadier performers using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com