


EN
Green Thumb Industries Stock Loss Widens As Florida Expansion Continues
- Green Thumb Industries reported Q3 2026 sales of US$324.41 million with a net loss of US$4.83 million, while also expanding its U.S. retail footprint through new dispensary openings.
- The shift from net income to a quarterly loss, alongside continued store growth, highlights pressure on profitability as Green Thumb Industries invests in scaling operations.
- We will now explore how Green Thumb Industries’ Q3 loss and ongoing Florida dispensary expansion could reshape its broader investment narrative.
Green Thumb Industries Investment Narrative Recap
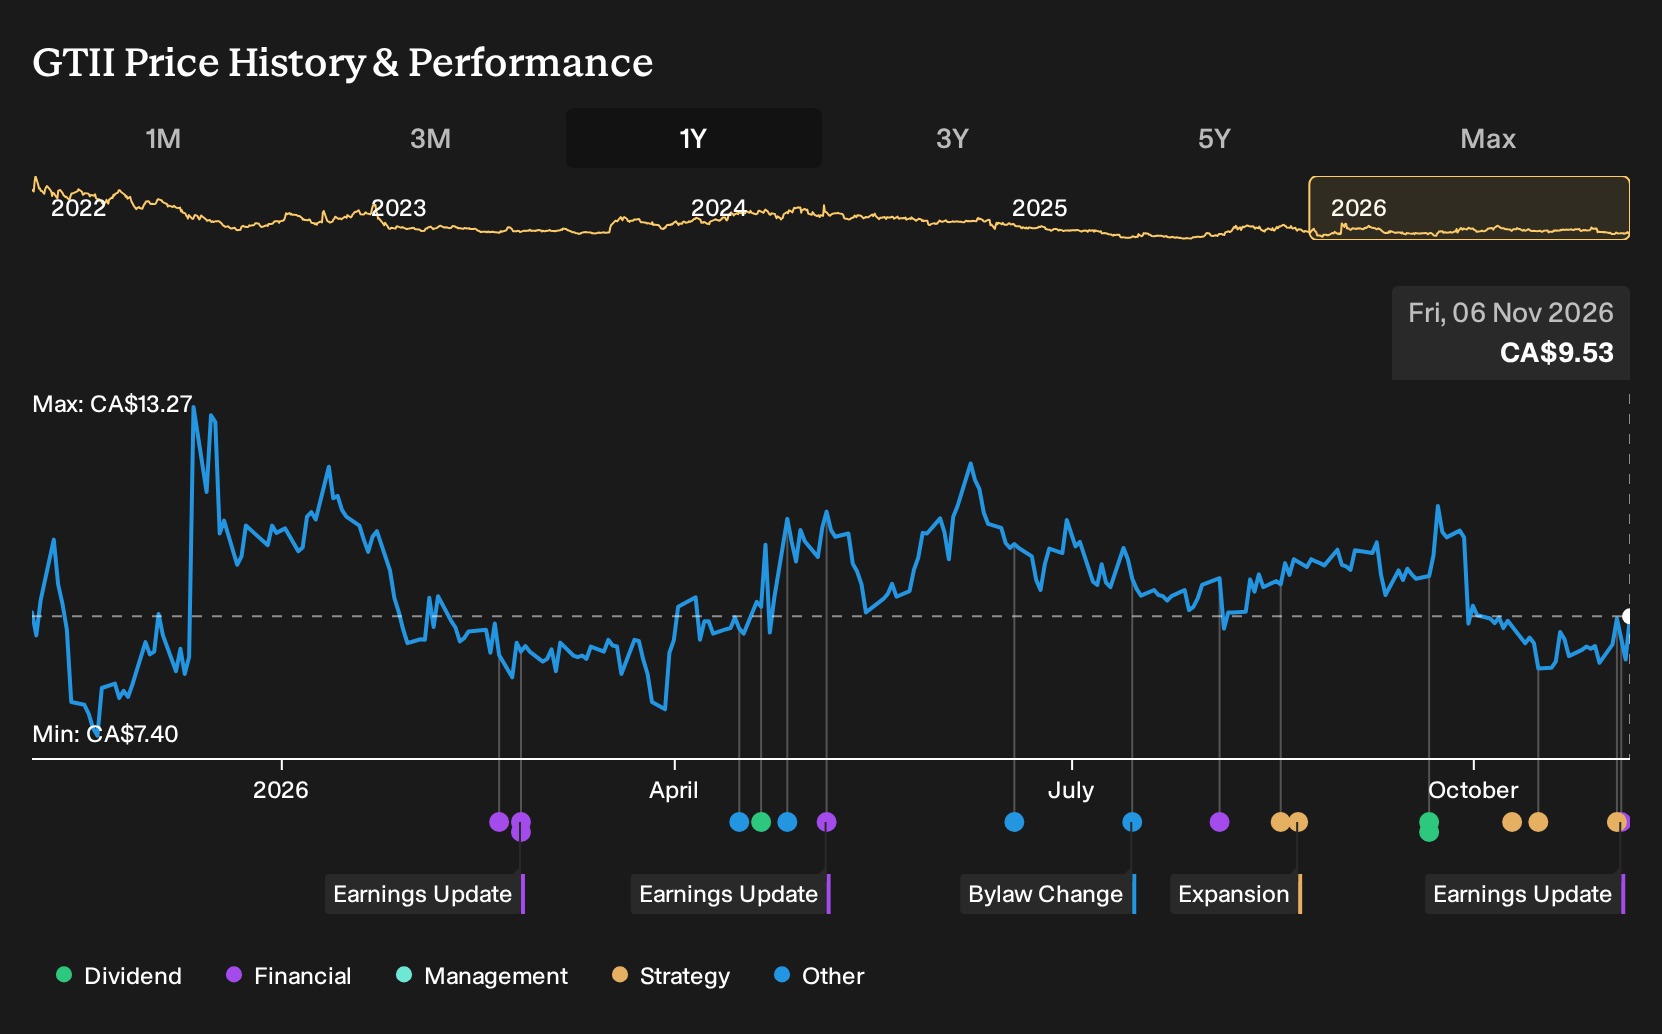
To own Green Thumb Industries, you need to be comfortable with a simple idea: the business is prioritizing footprint and product reach while accepting more earnings volatility. Q3 2026 captured that trade off. Sales for the quarter and year to date were higher than a year earlier, yet the period swung from profit to a US$4.83 million loss.
The key near term catalyst remains execution in newer and growing markets, especially Florida, while keeping a lid on operating costs that have already been trending higher. The biggest risk still sits in margin pressure from price compression and rising SG&A, and this quarter’s loss makes that pressure more visible rather than changing it.
The Mulberry, Florida opening is the announcement that ties closest to this earnings print. Management is adding another RISE outlet on top of an already broad Central Florida presence and more than 120 locations nationwide. Store count keeps climbing while same store pricing and margins face headwinds in several states.
For you as a shareholder, that mix of expansion and earnings compression sets the bar for execution. The Florida build out can support the longer term revenue catalysts analysts focus on, yet it also pushes near term costs higher. How Green Thumb Industries converts this denser footprint into stable margins sits at the center of the current thesis.
What Analysts Are Building Into The Green Thumb Industries Story
Green Thumb Industries' narrative projects $1.5b revenue and $79.6 million earnings by 2029. This is based on 6.6% yearly revenue growth and an earnings decrease of about $47.2 million from $126.8 million today.
Uncover how Green Thumb Industries' fair value indicates a 121% potential upside to its current price before sentiment around Green Thumb Industries closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts lean heavily on a different catalyst for Green Thumb Industries. They focus on THC beverages and premium brands, assuming revenue of about US$1.5b and earnings near US$59.1 million by 2029, before this Q3 loss and Florida opening. You can compare that optimism with your own assessment and decide whether sentiment may shift.
Explore 5 other Green Thumb Industries fair value estimates, including one that suggests as much as 162% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Green Thumb Industries research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Green Thumb Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Green Thumb Industries' overall financial health at a glance.
Looking For More Ideas Beyond Green Thumb Industries?
If Green Thumb Industries helps frame how you think about risk, growth and capital discipline, the next step is to compare it with a wider set of opportunities. The Simply Wall St screener can help you quickly line up companies with financial profiles that match the way you like to invest.
- If you want staying power ahead of anything else, focus on balance sheet strength and scan our list of solid balance sheet and fundamentals (5 results) that already pass strict debt and liquidity checks.
- If your priority is paying a regular income, filter for resilient cash generators by reviewing our 3 dividend fortresses that pair higher yields with fundamental support.
- If you are hunting for overlooked opportunities with room to mature, broaden your watchlist using our 7 high quality undiscovered gems that combine quality markers with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com