


EN
Enbridge (TSX:ENB) Q3 Results Leave Dividend Strain Front And Center
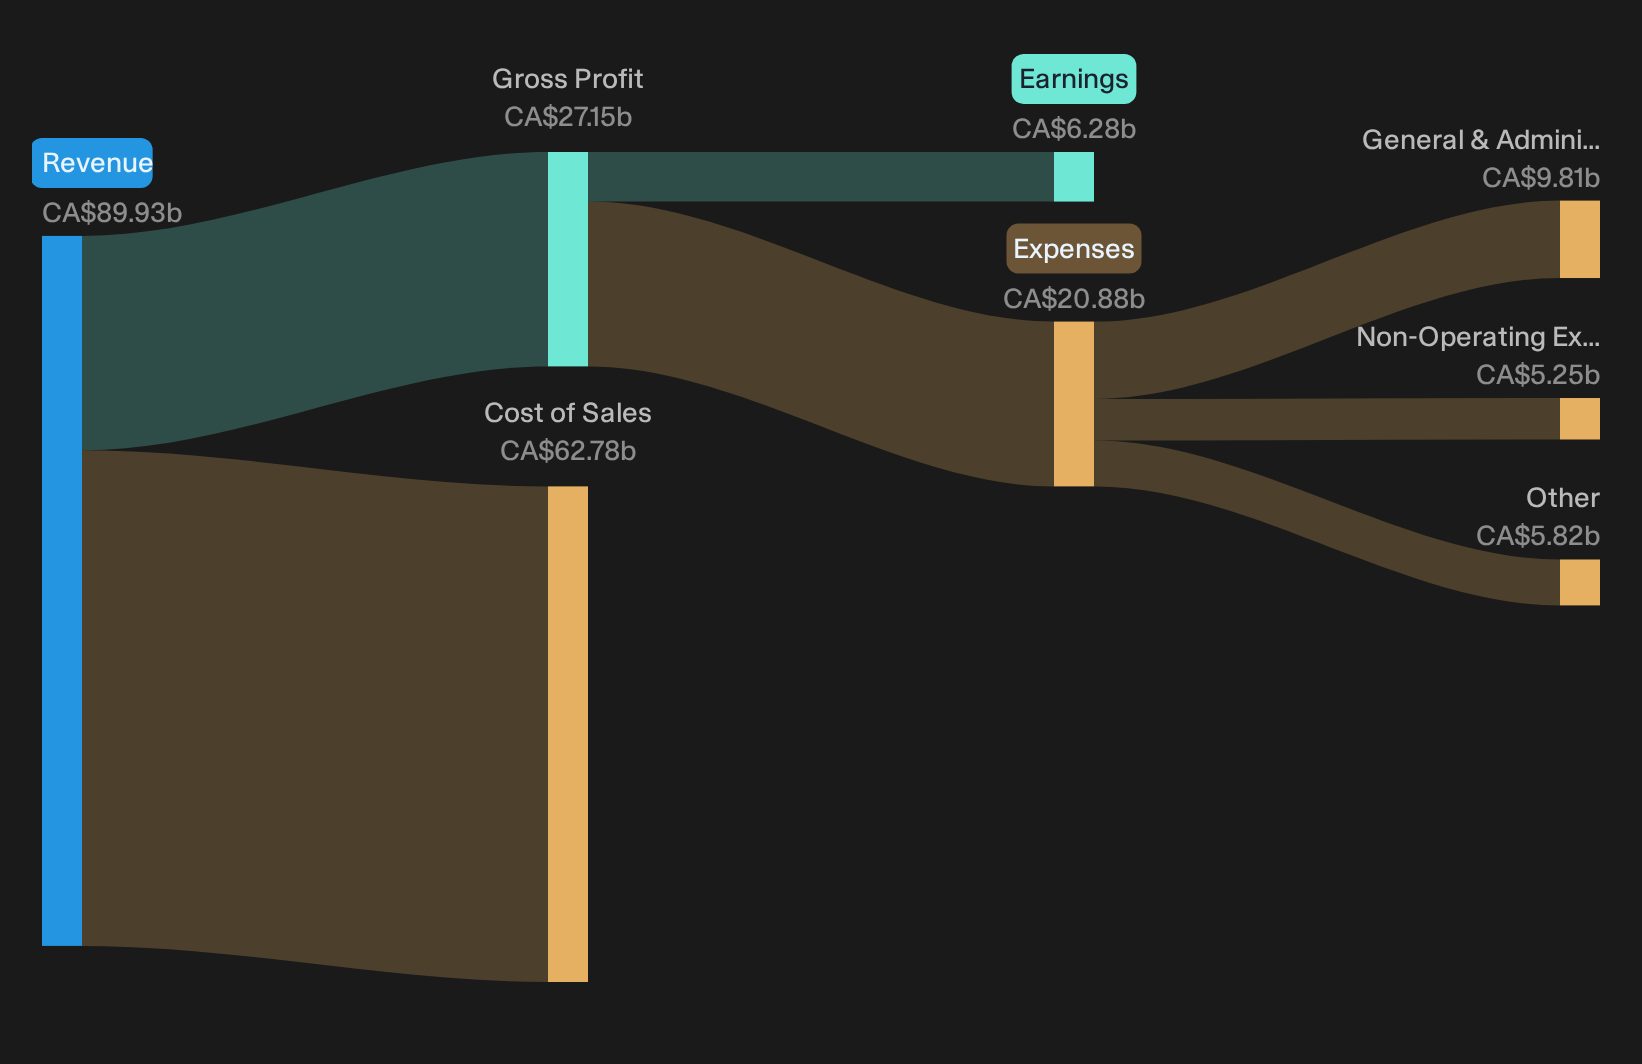
Enbridge entered its Q3 2026 earnings with the stock roughly flat over the past month and down over the last quarter, as investors weighed its income story against balance sheet worries. The company then reported another quarter of solid distributable cash flow, supported by CA$21.1b in revenue and CA$1.29b in net income from ongoing operations.
The twist for investors is that the shares closed the day at CA$66.14 with only a muted 7-day move lower, while the real strain remained in the background. Higher financing costs and a still heavy dividend commitment kept the balance sheet and payout coverage firmly in the spotlight.
Love Enbridge’s income profile but uneasy about the balance sheet strain behind that dividend load? Look at the list of solid balance sheet and fundamentals stocks (5 results).
Q3 2026 Earnings Summary
- Revenue, Q3 2026 vs. Q3 2025: CA$21,077m vs. CA$14,639m (up about 44%)
- Net Income (Excl. Extra Items), Q3 2026 vs. Q3 2025: CA$1,288m vs. CA$654m (up about 97%)
- Basic EPS, Q3 2026 vs. Q3 2025: CA$0.59 vs. CA$0.30 (up about 97%)
- Trailing 12-Month Revenue, Q3 2026 vs. Q3 2025: CA$89,929m vs. CA$64,234m (up about 40%)
Enbridge reaffirmed 2026 guidance and flagged a $38bn growth backlog. Ask Charlie what Enbridge’s $38bn backlog really hinges on.
Enbridge backlog story earns partial credit
Bulls argue Enbridge’s secured projects and self funded spend will steadily convert into higher cash flow while keeping leverage in check.
"The planned $10 to $11b of average annual self funded investment capacity, supported by free cash flow after dividends and incremental debt within the 4.5x to 5.0x leverage range, gives Enbridge room to keep building its asset base, which can support long term growth in cash flow and net income."
Q3 showed real progress. Over CA$3b of gas projects entered service and adjusted EBITDA and DCF both rose, and 2026 guidance was reaffirmed. Debt to EBITDA at 5.1x, even if FX adjusted within target, confirms the growth engine is working but still running close to the guardrails.
Leverage, dilution and delivery risk stay live
Bears focus on balance sheet stretch and the chance new assets fail to earn their keep on a per share basis.
"The recent C$3.0b common equity issuance to help fund the Tallgrass and Salt Creek acquisitions increases the share count. If the acquired assets or the broader secured project backlog do not produce the earnings uplift implied by current expectations, the result could be earnings per share dilution even if absolute earnings rise, limiting upside for shareholders and reducing the effectiveness of cash flow growth on a per share basis."
Here, the quarter cuts both ways. Tallgrass and Salt Creek closed and are contributing to higher EBITDA and DCF, and the Westcoast JV recycled CA$2.7b of capital. At the same time, the equity raise and leverage at 5.1x leave little room for project slippage before the dilution risk in that quote becomes more than theoretical.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Quiet Cash Engines
Enbridge shows how a steady income story can sit beside balance sheet concerns. The real opportunity is identifying stocks that could be undervalued before the market potentially narrows that valuation gap.
- Company 1 - 36% below our estimate - focus grows on scaling power systems and refrigeration capacity so higher equipment bookings support more durable earnings performance.
- Company 2 - 41% below our estimate - targets faster inventory turns with flexible open to buy commitments so stores and e-commerce align more closely with shifting demand.
- Company 3 - 34% below our estimate - expands through acquisitions while pushing digital tools and shared delivery centers so large infrastructure and water programs support higher consulting efficiency.
Those are three of them. See all 6 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com