


EN
What Resolute Mining Doubters Got Wrong
If Resolute Mining was on your watchlist rather than in your portfolio, the return may sting. Investors who held Resolute Mining over the past year are up 41.0%, including dividends. That outcome sits between a bullish camp arguing Doropo, automation at Syama and record gold prices could reset margins, and a cautious group focused on West African permitting risk and funding needs. If you were weighing those views back in November 2025, which business story about cost efficiency and new projects looked more convincing?
This theme extends beyond Resolute Mining. See which of 33 elite gold producer stocks may still merit a closer look.
The Two Resolute Mining Stories Investors Had To Weigh
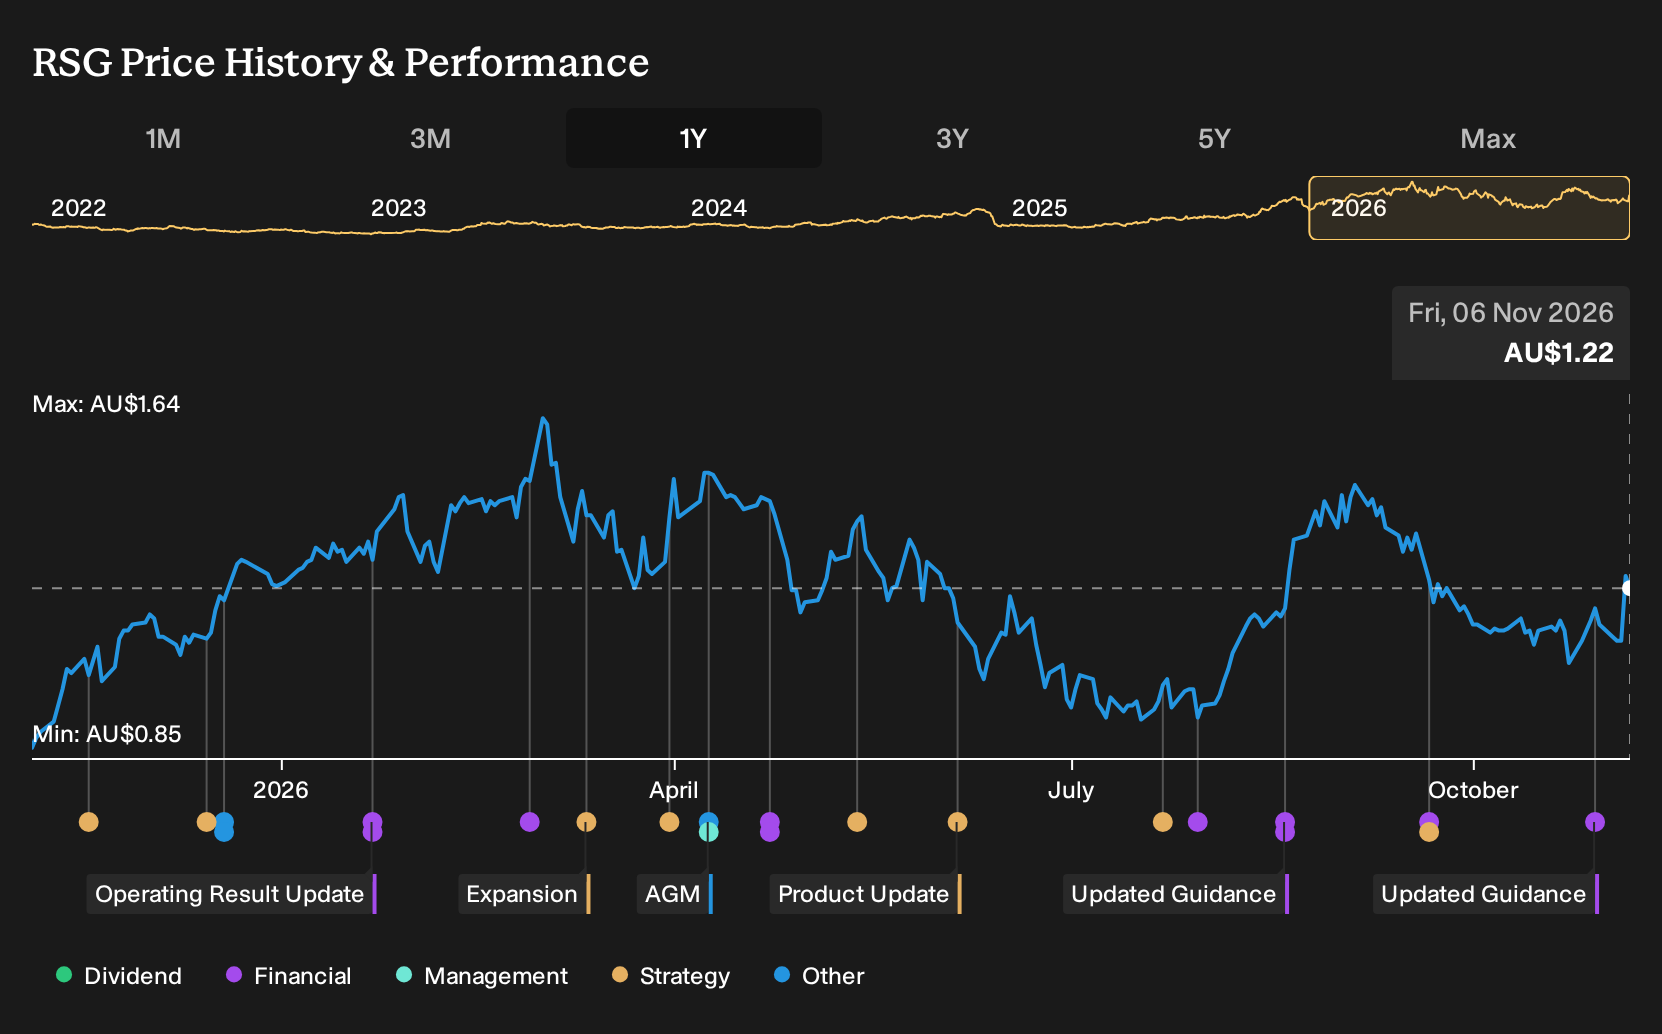
The shares cost A$0.85 at the start of the period, so every forecast about Resolute Mining hinged on whether that price already reflected its Africa focused risks and potential project gains.
The bullish narrative pointed to a Fair Value of A$1.8, a notional upside based on assumptions that Doropo, Syama automation and reserve upgrades would support 11.1% annual revenue growth and lift profit margins from 1.0% to 42.1% by 2028.
The more cautious script put Fair Value at A$0.75, an implied downside that still assumed margins could reach 29.8% by 2028 but flagged West African permitting uncertainty, cost pressures and future funding needs as major tests.
What The Results And Projects Meant For Resolute Mining
Resolute Mining’s H1 2026 report showed revenue at US$584.7 million and net income at US$128.2 million, with net margin lifting to 21.9%. That profitability shift backed the bullish focus on efficiency and cash generation. However, setbacks at Syama in Q2 2026 and lower production around 30,000 ounces challenged the idea that automation and West African operations would run smoothly.
The hinge assumption here was operational delivery at key assets. For any other miner with a big growth story, it is worth checking whether production volumes, all in sustaining costs and project timelines line up with the promises made a year earlier.
What Resolute Mining’s Price Now Assumes
Resolute Mining trades at A$1.22 today, with the selected Narrative arguing that its Fair Value sits above that level based on project delivery and cost control rather than sentiment alone.
The Narrative leans on Doropo and ABC turning Resolute Mining into a larger multi asset producer and contends today's price still does not credit sustained execution on those projects at controlled all in sustaining costs.
"Key Takeaways: Analysts expect Resolute Mining to move through a transformational growth phase driven by Doropo and ABC, with production targets above 500,000 ounces from 2028 and a further step up a few years later if ABC becomes a fourth mine. The main requirement is successful execution on Doropo construction and ABC drilling and studies, while keeping group AISC under control despite higher fuel and royalty costs and operational risk in Mali."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Resolute
Resolute Mining leans on gold, with its own mix of projects and jurisdictions. You might also think about which metals future infrastructure will keep needing.
Electrification, data centres and growing cities all depend on steady copper and aluminum supplies. Those materials help wires carry power and structures handle strain.
Another diversified miner concentrates on extracting those building blocks and refining them. It is also moving further into lithium, which links more directly to batteries.
The open question is how that mix of copper, aluminum and lithium might reshape its role in the next phase of materials demand.
One Narrative has already put a figure on it. → Uncover the company trading 17% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com