


EN
What adidas Stock's Raised Outlook Means For Shareholders
- adidas reported third quarter 2026 sales of €7,252 million and net income of €706 million, with basic earnings per share from continuing operations at €4.06, alongside higher sales and earnings for the first nine months compared with the prior year.
- The company paired this earnings update with a raised full year outlook, which signals management confidence in current demand trends and the profitability mix across its footwear and apparel portfolio.
- We will now look at how adidas's investment narrative may be influenced by this stronger third quarter performance and upgraded outlook.
Compare adidas' momentum and valuation premium against a curated group of resilient peers by scanning the 213 resilient stocks with low risk scores, which combines sturdier balance sheets with lower risk scores.
adidas Investment Narrative Recap
To own adidas, you need to be comfortable with a story built on brand reach, product performance categories and disciplined execution on margins. The latest quarter, with €7,252 million of sales and €706 million of net income, reinforces that the operating machine is functioning and supports management’s decision to raise the full year outlook.
The key near term catalyst is whether adidas can keep momentum in higher margin direct to consumer channels and performance lines while holding gross margins against FX, tariffs and promotions. The biggest immediate risk remains cost pressure from U.S. import tariffs and intense discounting by rivals, which could squeeze earnings if pricing power softens.
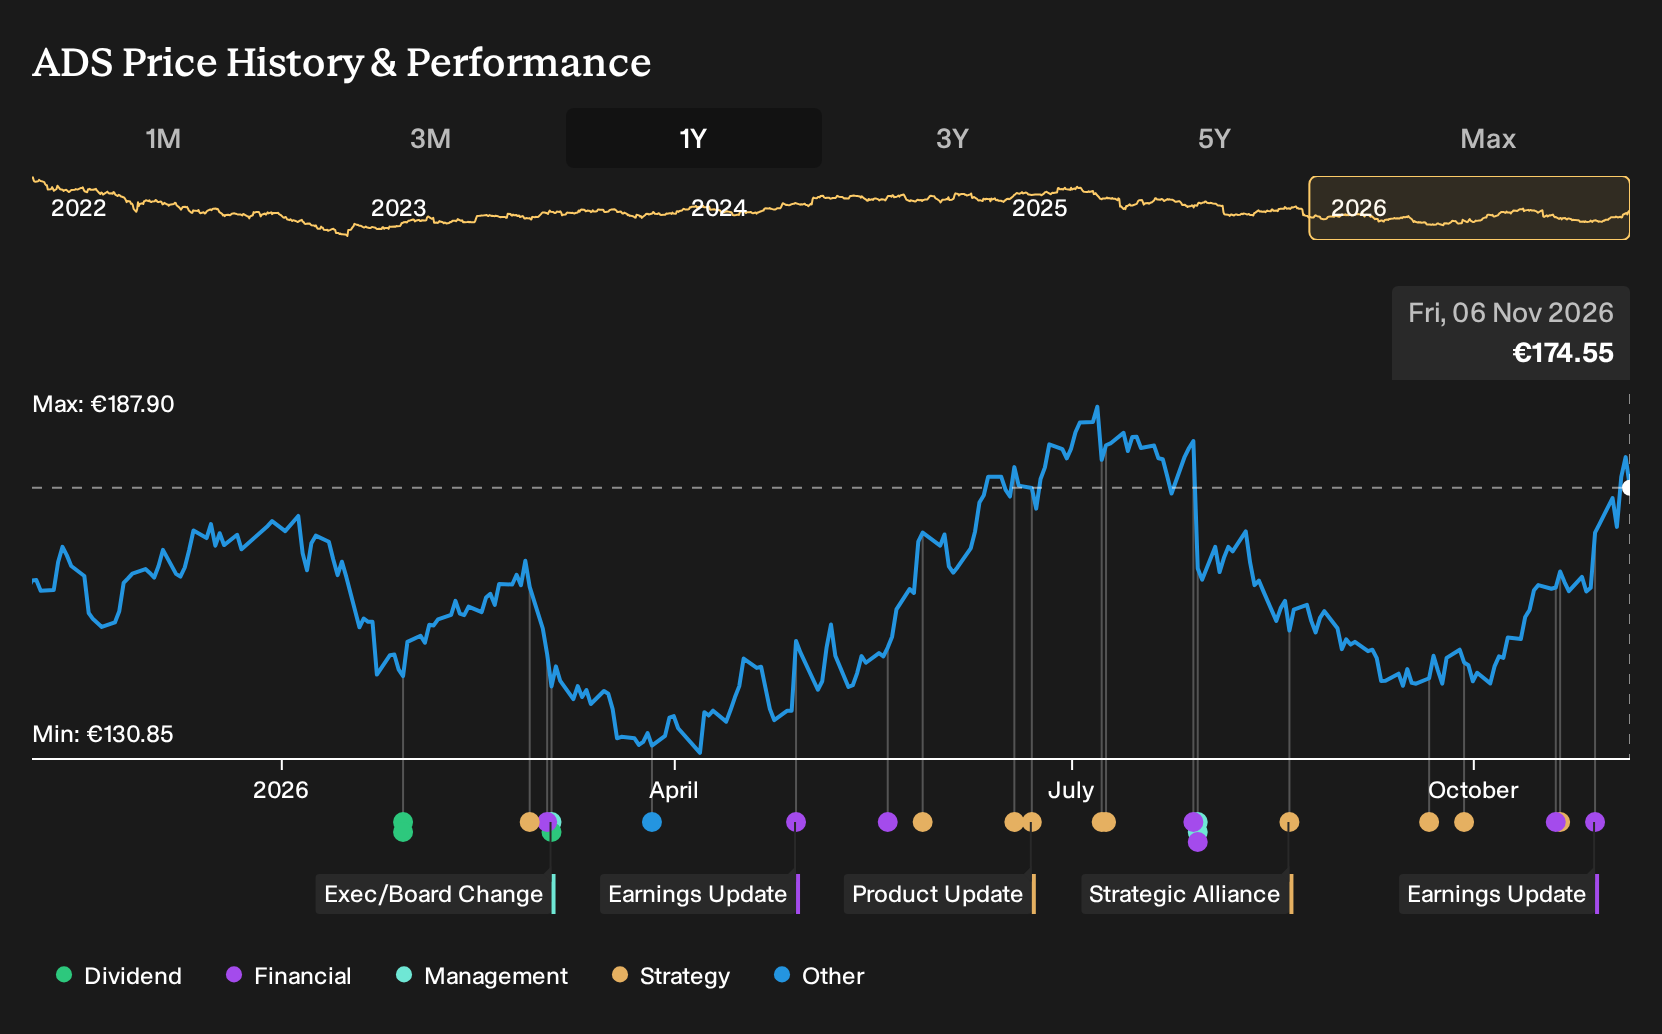
The third quarter 2026 earnings announcement is the clearest operational marker for this catalyst. Sales for the quarter were €7,252 million compared with €6,630 million a year earlier, and net income was €706 million compared with €461 million. Basic earnings per share from continuing operations reached €4.06 compared with €2.57, and adidas paired this with a higher full year outlook.
For the first nine months of 2026, adidas reported €20,587 million in sales and €1,543 million of net income compared with €18,735 million and €1,259 million a year earlier. That trajectory, together with the raised guidance, provides evidence on how the football program, performance franchises and direct channels are feeding into earnings, while also framing how exposed the business remains to tariffs, promotions and any future regulatory scrutiny of marketing claims.
adidas' current analyst narrative points to €32.0 billion of revenue and €2.4 billion of earnings by 2029, built on 7.1% yearly revenue growth and an earnings increase of about €1.0 billion from the €1.4 billion level today.
Uncover why adidas' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest adidas forecasts were already warning that once World Cup demand fades, revenue momentum might cool. Those analysts were working with around €32.1b of 2029 revenue and roughly €2.1b of earnings, and see the raised outlook as a potential test of that cautious view. Use this gap in expectations as a reminder to weigh several narratives, not just one.
Explore 6 other adidas fair value estimates, including one that suggests it could be worth just €190.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your adidas research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for adidas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate adidas' overall financial health at a glance.
Looking for more investment ideas beyond adidas?
If adidas is only one piece of your watchlist, it can help to scan for other opportunities that fit different roles in your portfolio, from potential value candidates to sturdier balance sheet plays or higher income options.
- For investors hunting for strong balance sheets and sturdier fundamentals, the list of solid balance sheet and fundamentals (192 results) can help you focus on companies where financial resilience is front and center.
- If you want to tilt toward value opportunities with quality characteristics, use the 227 high quality undervalued stocks to filter for stocks that combine healthier cash flows with what may be a more modest valuation.
- Income focused investors can narrow the field by checking the 232 dividend fortresses for higher yielding companies that aim to pair payout potential with stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com