


EN
Pan African Resources (LSE:PAF) Could Be 16% Undervalued On The Gold Price Rally
Pan African Resources (LSE:PAF) moved into focus after gold prices rose above $4,000 an ounce, with the stock benefiting from sector wide gains linked to a weaker US dollar and lower Treasury yields.
Recent trading shows that momentum around Pan African Resources has picked up, with a 7 day share price return of 10.72% and a 90 day move of 5.37%. This comes even though the year to date share price is down 3.58%. Over the longer term, total shareholder returns are very large over 3 and 5 years, and the 1 year total shareholder return of 38.19% points to strong compounding over time.
Capitalize on the renewed interest in gold by comparing Pan African Resources with a curated set of 33 elite gold producer stocks that are also reacting to the latest moves in the metal and currency markets.Pan African Resources has ridden the gold surge hard, yet the shares are still down for the year and trading near analyst fair value estimates. Does that mix of momentum and past underperformance still reward fresh buyers, or does it now favour patience?
Most Popular Narrative: 16% Undervalued
On the narrative view, Pan African Resources screens below a fair value estimate of £1.37, compared with the recent close around £1.16. That gap reflects a downside scenario that still arrives at a fair value well under the current analyst target, which sets a high bar for anyone leaning on stress test assumptions.
The FY2026 step-up reflects the expanded operating base and higher gold prices, so it should not be treated as a normalised downside-year run rate.
See why 0 investors see Pan African Resources as 16% undervalued.
Result: Fair Value of £1.37 (UNDERVALUED)
Still, the fully unhedged exposure to gold prices and the approximately US$2,000 per ounce Australian cost base could quickly pressure the Pan African Resources downside thesis.
Find out about the key risks to this Pan African Resources narrative.
Another View: Pan African Resources Through A Cash Flow Lens
A second take on Pan African Resources comes from the SWS DCF model, which puts future cash flow value at £1.15 per share against a recent price of £1.16. That pins the stock almost exactly on model fair value. Investors may therefore want to consider how much room is left if the gold tailwind cools.
For investors who want to see how robust that cash flow based result is under different scenarios, it helps to walk through the moving parts in detail. Look into how the SWS DCF model arrives at its fair value.
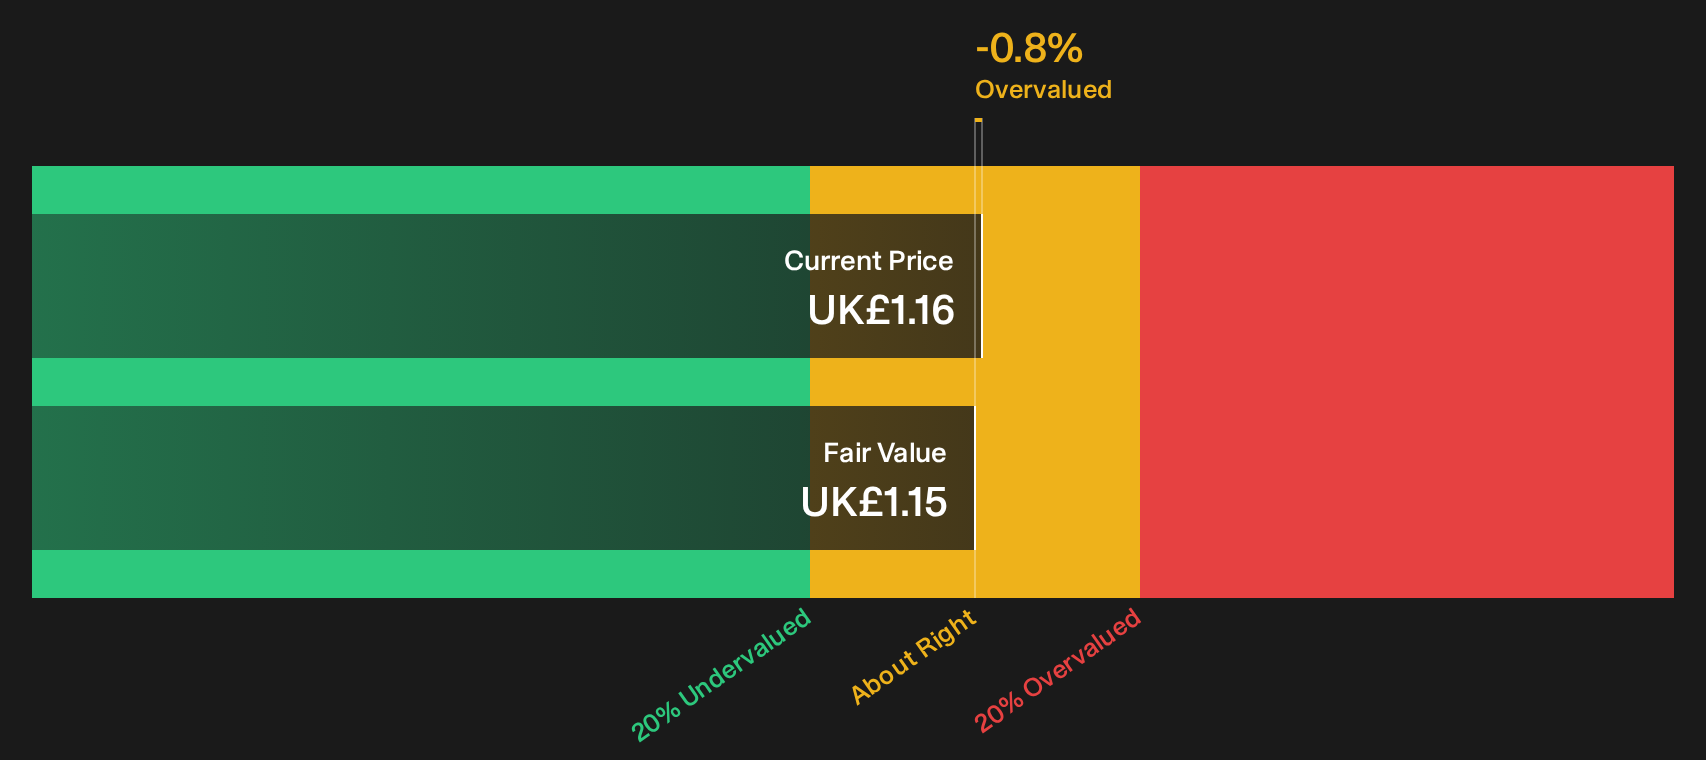
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pan African Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Pan African Resources can be confusing, especially with both concerns and bright spots in the story, so move quickly, review the underlying drivers, and weigh the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Pan African Resources?
If Pan African Resources has sharpened your focus on opportunities, broaden your watchlist now so you are not late to the next move.
- Target resilient income streams by scanning for companies built around dependable cash payouts using the 4 dividend fortresses.
- Hunt for mispriced quality by filtering for financially strong businesses trading below their estimated worth through the 15 high quality undervalued stocks.
- Spot potential future favourites early by tracking financially sound outliers in the 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com