


EN
HubSpot (HUBS) Stock May Be Undervalued After Slower Growth Outlook
HubSpot has seen its share price fall sharply in recent years, which puts fresh focus on whether the current US$200.61 level is still supported by what the business earns. With sentiment swinging around the latest earnings news, the key issue for you is how closely the stock price lines up with the underlying profit stream.
- Over the past 5 years the share price has declined 76.2%, so the valuation conversation today is happening after a very large reset in what the market is prepared to pay for HubSpot’s earnings.
- Recent earnings outperformance alongside expectations for slower revenue growth can influence whether investors place more weight on current profitability or on the pace of future expansion when assessing HubSpot’s earnings power.
- There is a second opinion on HubSpot worth weighing. See what analysts think HubSpot's shares could be worth.
The issue now is whether the current market price of HubSpot is justified by the earnings the company is producing today and is expected to generate over time.
If you are weighing HubSpot against other opportunities that also hinge on earnings power and valuation resets, it can help to compare it with 41 high quality undervalued stocks.
Is HubSpot Still Cheap on Earnings?
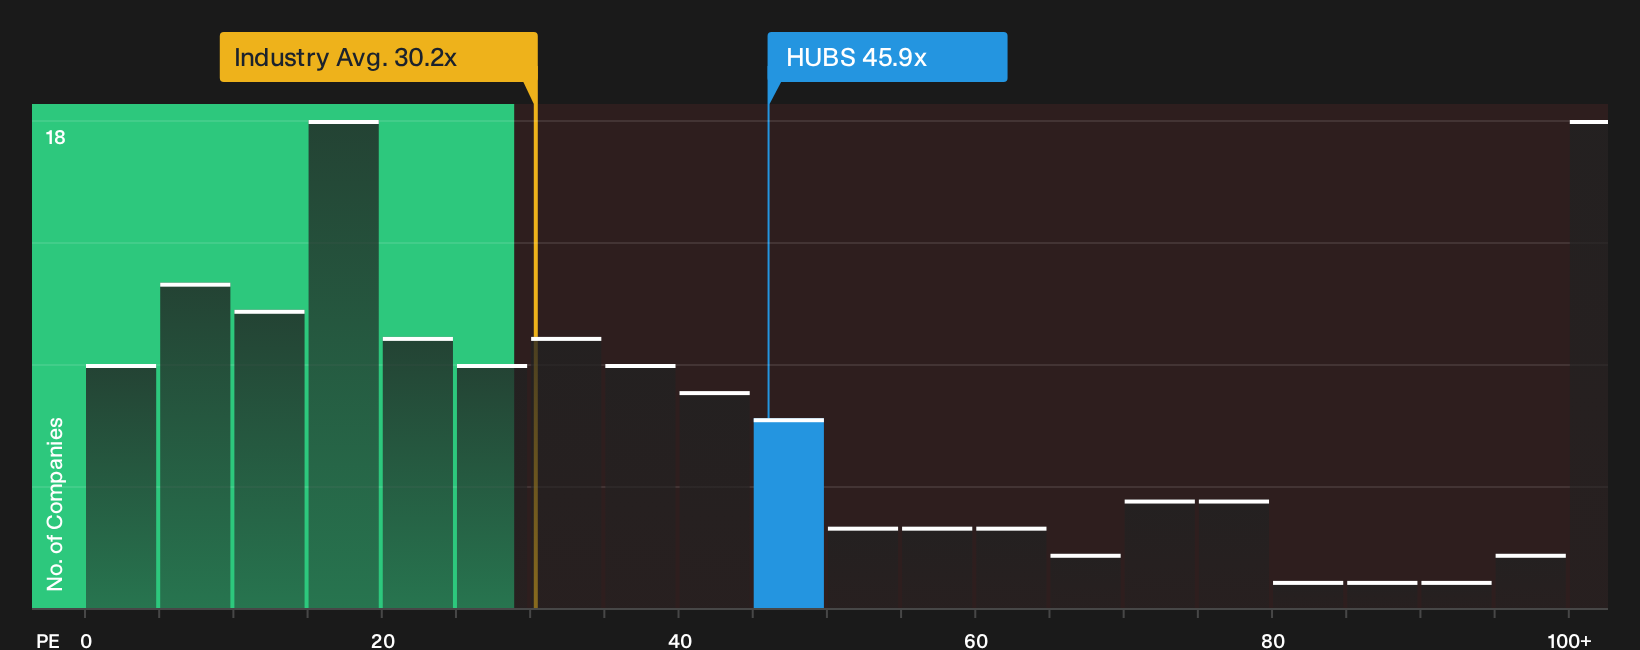
The P/E ratio suits HubSpot because earnings have become a key anchor for how the market is judging the story today. On this metric, the stock trades on a P/E of 45.9x, which is higher than the broader Software group on 30.2x and only slightly above the peer average of 45.1x. That puts HubSpot on a premium to the sector overall while pricing it roughly in line with closer direct comparables.
Because the current P/E sits below the level suggested by a more tailored fair multiple that blends growth, profitability, size and risk, the shares screen as undervalued on this framework. Despite the recent Q3 earnings beat and the mixed reaction around slower projected growth, the valuation still implies a discount to what that earnings profile would typically command over time. Explore the numbers behind HubSpot's P/E valuation.
The HubSpot Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for HubSpot sit on the Community page and extend this valuation puzzle by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price. Where a single ratio or model throws up one headline figure, these storylines lay out the future that number leans on so you can track whether that path actually holds over time.
HubSpot draws a split crowd, with some community members arguing it offers more value at today’s price while others see expectations as already full.
Bull case: 39% undervalued
"My view that customers won’t recreate HubSpot in-house supports the argument that HubSpot’s product-led convenience and ecosystem are durable defensive advantages..."
Discover why this Narrative puts HubSpot at 39% undervalued.
Bear case: 6% overvalued
"The numbers suggest that HubSpot's share price already reflects strong adoption of AI agents, multi-hub usage, international exposure, and margin expansion targets..."
Explore why this Narrative puts HubSpot at 6% overvalued.
For HubSpot, the share price only tells part of the story
Before you treat HubSpot’s valuation as the final word, it helps to look at who is steering the business and how their pay packets line up with your interests. See who runs HubSpot and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com