


EN
Chartwell Retirement Residences (TSX:CSH.UN) Turns Profitable In Q3 Following A Fresh Valuation Test
Chartwell Retirement Residences (TSX:CSH.UN) just released its Q3 2026 results, reporting revenue of CA$324.98 million and net income of CA$114.96 million, compared with a loss in the same period last year.
The latest Q3 announcement lands after a strong run in Chartwell Retirement Residences, with a 13.89% 1 month share price return and an 11.31% year to date share price gain. The 3 year total shareholder return of 137.13% points to powerful longer term momentum and a materially stronger performance for investors who have stayed invested through distributions.
Compare Chartwell Retirement Residences' momentum with a curated shortlist of income-focused operators by scanning 3 dividend fortresses, which echo this combination of distributions and recent share price strength.
For Chartwell Retirement Residences, that sharp run after Q3 can look like a clean read on stronger fundamentals or a rush of optimism that ran ahead of itself. Which story do the current valuation markers support?
Most Popular Narrative: 14% Undervalued
Chartwell Retirement Residences closed at CA$22.14, while the most followed narrative anchors fair value at CA$25.86. This frames the recent Q3 rally as still leaving a valuation gap on many investors’ numbers.
Ongoing portfolio recycling, with over $3.2b of newer residence acquisitions over two years and more than $300 million of non core asset sales in 2026 at cap rates above what Chartwell Retirement Residences reports paying for newer core assets, can continue to shift the mix toward higher quality properties and support higher EBITDA and net margins.
See why 20 investors see Chartwell Retirement Residences as 14% undervalued.
Result: Fair Value of CA$25.86 (UNDERVALUED)
Still, that story can crack if rising operating costs squeeze margins or if ongoing equity issuance and unit growth dilute per unit earnings power.
Find out about the key risks to this Chartwell Retirement Residences narrative.
Another View: Chartwell Retirement Residences Looks Expensive On Earnings
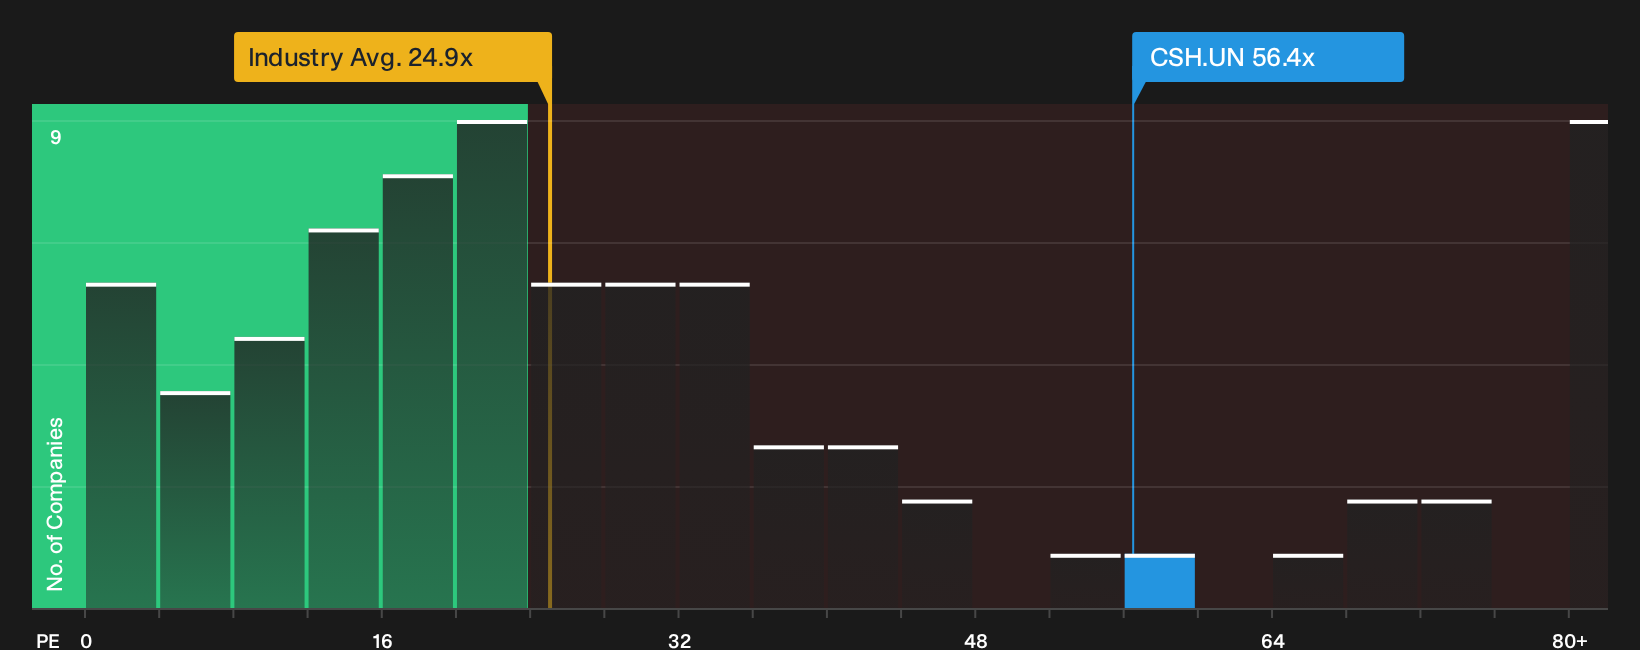
The Q3 story presents Chartwell Retirement Residences as about 14% below a CA$25.86 fair value, yet the current P/E of 56.4x suggests a tougher interpretation. A fair ratio of 25.4x, together with an industry average near 24.9x, points to a rich earnings multiple. Is this a cushion or a valuation trap?
To stress test that gap, it may help to focus on what it would take for earnings to align with today’s P/E and how comfortable you are paying more than double the fair ratio while sector peers trade much lower. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mixed tone around Chartwell Retirement Residences, with both optimism and concern in play, means you need to look through the data yourself and move quickly to frame your own stance. To size up both the upside and the pressure points in one place, start with these 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Chartwell Retirement Residences?
If Chartwell Retirement Residences has sharpened your focus on valuation and income, do not stop with a single opportunity. Broader context can sharpen every decision you make next.
- Target resilient balance sheets by running your checks through a curated list of solid balance sheet and fundamentals (5 results) that filters for financial strength first.
- Hunt for mispriced quality by scanning a focused 6 high quality undervalued stocks built to highlight stocks where fundamentals and price look out of sync.
- Fortify your income stream by reviewing a yield focused 3 dividend fortresses that concentrates on payouts supported by underlying financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com