


EN
Vistra (VST) Q3 Earnings Lift The Cash Flow Story
Vistra entered this Q3 2026 report with a choppy tape, down over the past week and month, then climbed 3.7% today to about $124.77. The market cheered first and asked questions later. The headline is simple. Vistra reported another strong quarter of profitability, with Q3 basic earnings per share at $3.25 on revenue of $6.3 billion, and management backing that up with raised guidance for 2026 adjusted earnings before interest, tax, depreciation and amortization and free cash flow. The short-term price move only hints at what that cash engine is now doing.
Impressed by Vistra turning that choppy share price into solid Q3 earnings and stronger cash guidance, but want more options that pair robust profitability with balance sheet discipline? Compare this setup with our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$6,347 million vs. US$4,971 million (higher year on year)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$1,092 million vs. US$604 million (higher year on year)
- Basic EPS (Q3 2026 vs. Q3 2025): US$3.25 vs. US$1.78 (higher year on year)
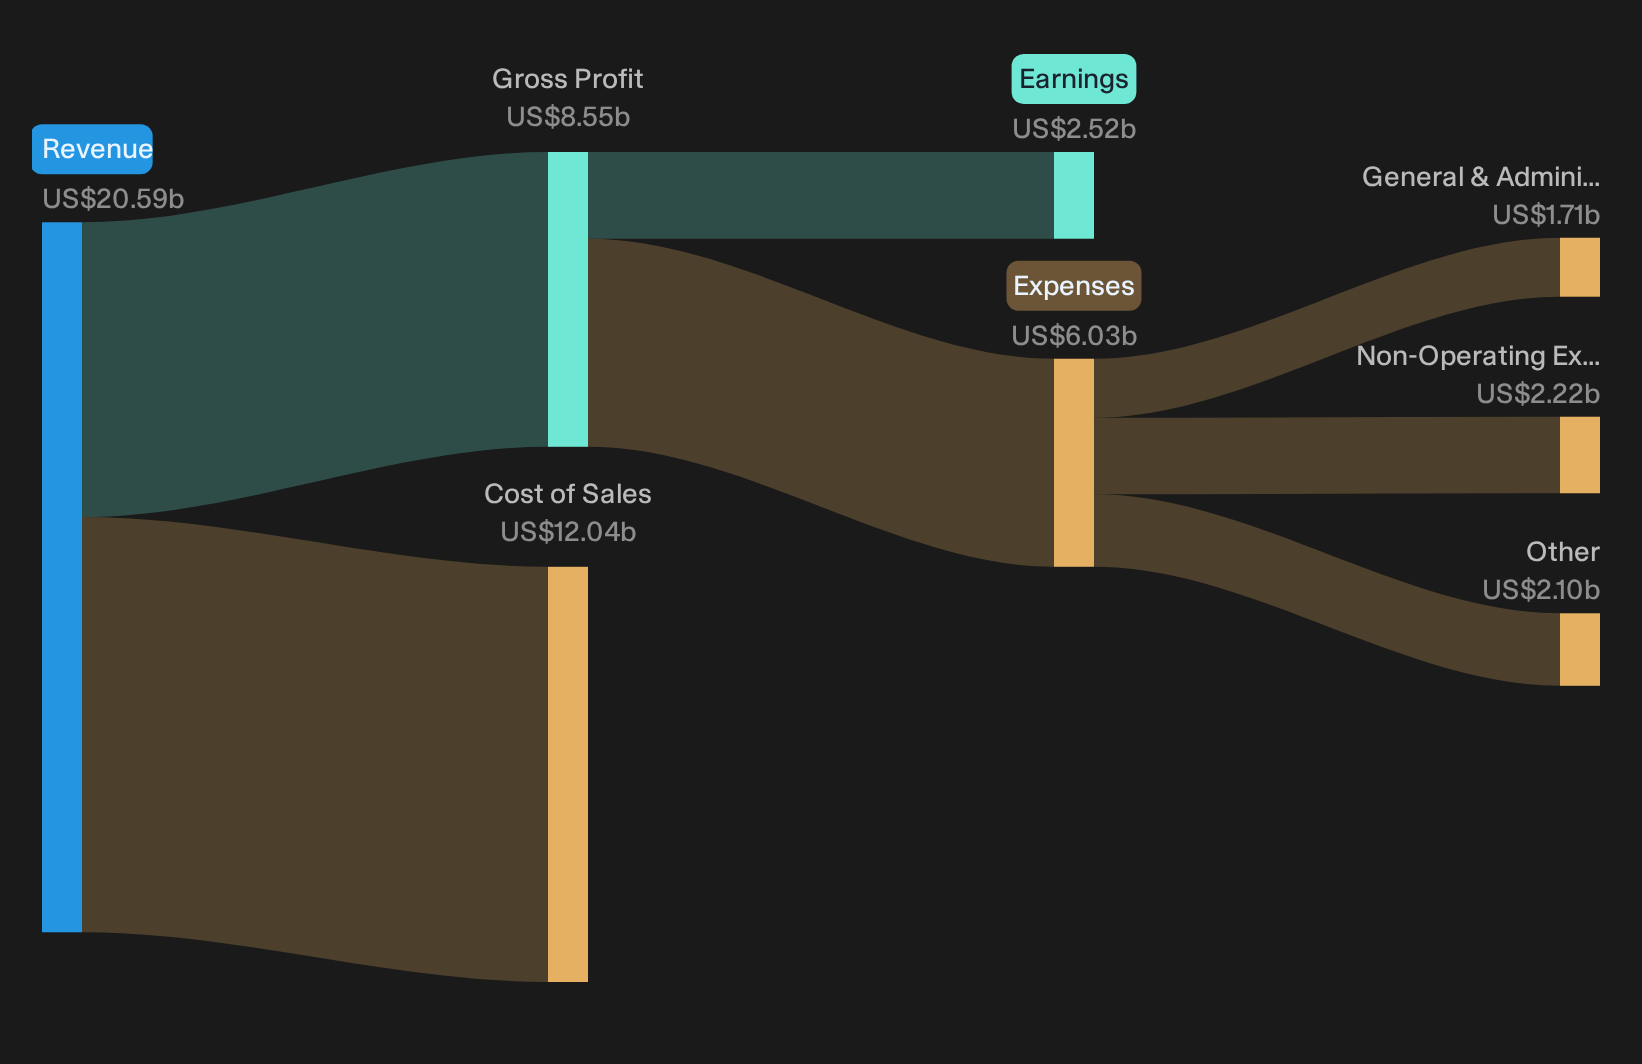
- Trailing 12 Month Revenue (Q3 2026 TTM vs. Q3 2025 TTM): US$20,588 million vs. US$17,191 million (higher on a rolling 12 month basis)
Prefer clean visuals instead of another wall of earnings tables and footnotes? See Vistra's full financial picture, including how its cash generation and profitability contribute to the overall valuation view, in an easy dashboard via our company report for Vistra.
Vistra’s Data Center Ambition Meets Hard Q3 Milestones
The bullish view depends on Vistra using long data center deals and a heavy capex plan to turn growth projects into steadier, contracted cash flow.
"The main thing that has to go right is that Vistra successfully executes its capital program of roughly US$4.5 to 5.0b in growth investments and billions of available cash while managing regulatory shifts so new projects and contracts earn attractive returns."
Q3 results show that execution is starting to appear in the numbers. Record adjusted EBITDA, raised 2026 guidance and fresh 2027 targets, the Cogentrix close, the DOE backed nuclear upgrade plan and new long term PPAs with Meta, Amazon and TCDC are concrete markers that this investment agenda is moving from narrative to operating reality.
One Narrative disagrees with today's price. → See where this Narrative says Vistra should trade.
Vistra Bear Case: Demand Risk Still Mostly Theoretical
Bearish analysts argue that Vistra’s long run earnings could suffer if efficiency, distributed resources and regulation cap demand for big new plants.
"Bearish analysts expect Vistra to face ongoing pressure on long term earnings growth due to energy efficiency gains, distributed resources, regulatory changes and more decentralized consumer solutions that could weigh on power demand and returns from new projects."
Q3 tells a different story so far. Record adjusted EBITDA and raised 2026 guidance, along with new long duration PPAs with Meta, Amazon and TCDC, indicate large load customers are still locking in supply. The Cogentrix close and DOE backed nuclear upgrade plan also suggest that projects are progressing rather than being stranded by weak demand or policy pushback in this period.
Hunt For Quiet Cash Engines
Vistra just showed how a single quarter can reset expectations for its cash flow story. The real opportunity sits in finding stocks that could be undervalued before the market closes that gap.
- Company 1 - 39% below our estimate - targets expanding AI and cloud storage demand as new high density NAND technology reshapes its enterprise SSD product mix and manufacturing cost structure.
- Company 2 - 27% below our estimate - converts record program wins in tightly regulated hardware into multi year contracts that aim to keep specialized factories operating at high utilization and support disciplined margin management.
- Company 3 - 45% below our estimate - advances late stage kidney, gene editing and endocrine therapies that diversify beyond a single treatment area into multiple serious chronic disease indications.
That is three of the list. See all 41 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com