


EN
3 Financial Stocks That Could Benefit If Higher Rates Stick Around
A stronger October jobs report, firmer wage data and louder Fed talk about more hikes have put higher-for-longer interest rates back in focus. That backdrop can reshuffle which dividend-paying financials quietly collect a little more from every dollar they lend or invest. This article walks through three stocks from our screener that are closely tied to this rate story and explains why some investors are watching them now.
The three dividend-paying financials covered below are only a sample of the idea. The full screen surfaced 7 more US banks, insurers and asset managers with similarly detailed stories around payouts, balance sheets and rate exposure that are not covered here.
If you want to go deeper on this theme and identify your own highest-conviction dividend plays that fit these filters, head straight into the US Dividend-Paying Financials Positioned for Higher-for-Longer Interest Rates screener to analyze, compare and refine the full list to your preferences.
Ridgepost Capital (RPC)
Overview: Ridgepost Capital is a Dallas based alternative asset manager offering private equity, venture capital, impact and private credit solutions globally.
Operations: Ridgepost Capital generates about $326 million in revenue from asset management fees across its private market investment platforms.
Market Cap: $1.06b
Ridgepost Capital fits this higher for longer dividend screen as a US alternative asset manager collecting fees on private equity, impact investing and private credit strategies. Recent revenue of $88.92 million and nine month net income of $25.7 million support that income profile. Its reliance on external funding, however, introduces an additional pressure point that could be important for future margins.
Those funding pressures make it worth seeing the Ridgepost Capital financial health report to gauge how Ridgepost Capital’s balance sheet could amplify or blunt the higher rate tailwind.
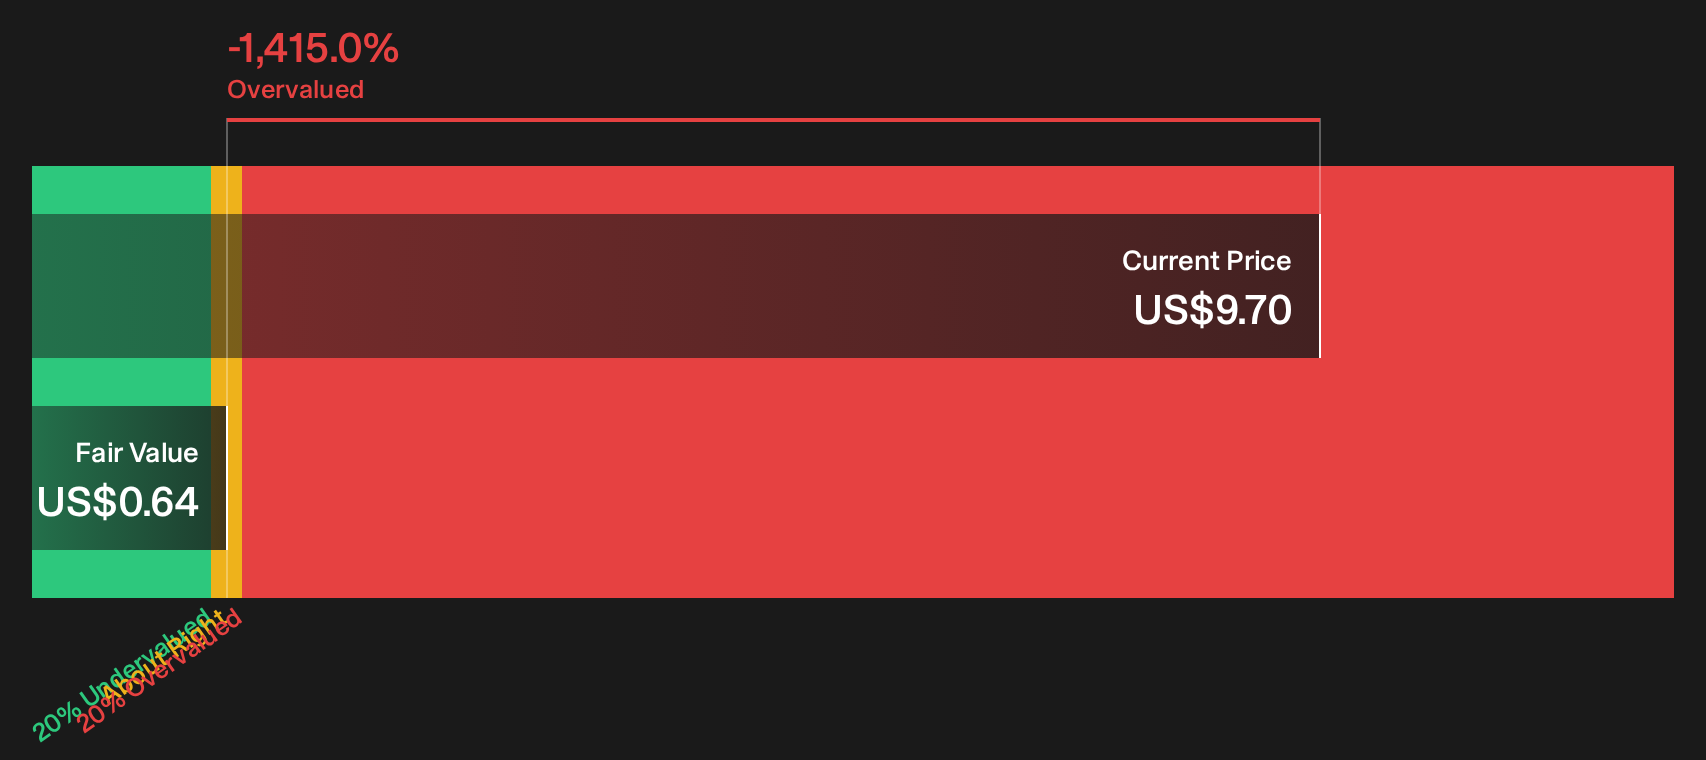
Cohen & Steers (CNS)
Overview: Cohen & Steers is a New York based asset manager focused on global real assets and alternative income portfolios for dividend minded investors.
Operations: Cohen & Steers generates about US$600 million from asset management, primarily in North America with smaller contributions from Japan, Europe and Asia Pacific.
Market Cap: US$3.77 billion
Cohen & Steers fits this dividend financials screen as a US asset manager geared to income focused portfolios that can benefit when higher-for-longer rates support yields on real assets and preferred securities.
"Strategic expansion into active ETFs and broader product diversification, including the launch of integrated listed and private real estate strategies, is expected to attract new investor segments and improve client retention, supporting future AUM growth and revenue stability."
What happens to Cohen & Steers’ fee margins and dividend headroom if a single key assumption about investor appetite for real assets breaks?
If that assumption is wrong, the full narrative for Cohen & Steers shows how Cohen & Steers’ dividend story could still accelerate under different fee, flow and payout scenarios.

Futu Holdings (FUTU)
Overview: Futu Holdings runs Futubull and moomoo, two digital platforms that provide online brokerage, margin financing and wealth products worldwide.
Operations: Futu Holdings generates about HK$24.1 billion from online brokerage and margin financing services, its main source of operating income.
Market Cap: US$13.7 billion
Futu Holdings fits this higher-for-longer dividend screen as a US listed, cash generative broker. Client cash yields, margin funding and trading activity can all react strongly to a stickier Fed rate path.
"The rapid growth in funded accounts remains a live driver, with total funded accounts reaching about 3.84 million in Q2 2026 and overseas markets contributing nearly 60% of these, which can support future revenue and fee income growth from a larger, more diversified client base."
The real swing factor is how one unresolved regulatory and funding pressure shapes what those headline account and asset figures actually mean for margins.
That pressure point is exactly where the full narrative for Futu Holdings shows how Futu Holdings’ regulatory risk, funding mix and account growth could be decoupling in ways the headline figures miss.

Seeking Fresh Alternatives Before Momentum Flies
Fresh breakouts rarely stay under the radar for long. Prices move, stories spread, and the edge drops fast. Scan these ideas before the crowd catches up and consider them promptly.
- Spot strong cash engines before momentum headlines appear by scanning the 41 high quality undervalued stocks, curated to highlight financially solid businesses priced below what their fundamentals suggest.
- Follow structural demand in critical materials by tracking the 16 top copper producer stocks, built to surface producers tied to long term electrification and infrastructure themes.
- Focus on consistent income by reviewing the 8 dividend fortresses, which is centered on resilient payers that aim to keep distributions flowing even when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com