


EN
NGEx Minerals Stock In Focus After Narrower Losses And New Lunahuasi Drilling Plans
- NGEx Minerals reported a quarterly net loss of C$16.14 million and a nine month loss of C$80.26 million, both lower than the prior year, while preparing a Phase 5 drill program and an exploration adit at the Lunahuasi project and advancing the spin out of its Valle Ancho asset into Valiente Resources.
- The combination of narrower losses and continued heavy spending on Lunahuasi and the Valiente Resources spin out highlights NGEx Minerals' focus on building long term project optionality rather than near term profitability.
- We will now look at how NGEx Minerals' narrower losses and Lunahuasi expansion plans could reshape the company's broader investment narrative.
Scan projects with similar long term potential by sizing up NGEx Minerals against a hand picked 16 top copper producer stocks that could benefit from the same appetite for future-facing assets.
NGEx Minerals Investment Narrative Recap
To own NGEx Minerals, you need to be comfortable backing an exploration-heavy story that still reports no revenue and continues to post losses. The big belief is that Lunahuasi, Los Helados and the broader Vicuña portfolio can justify years of upfront spending. The latest quarterly loss of C$16.14 million, narrower than last year, does not materially change that high risk, long duration profile.
The most important near term catalyst remains progress at Lunahuasi, especially drilling and the planned exploration adit, because that work underpins any future project studies. The main operational risk stays the same: cash burn and potential future dilution if exploration and permitting take longer or prove more expensive than investors currently expect.
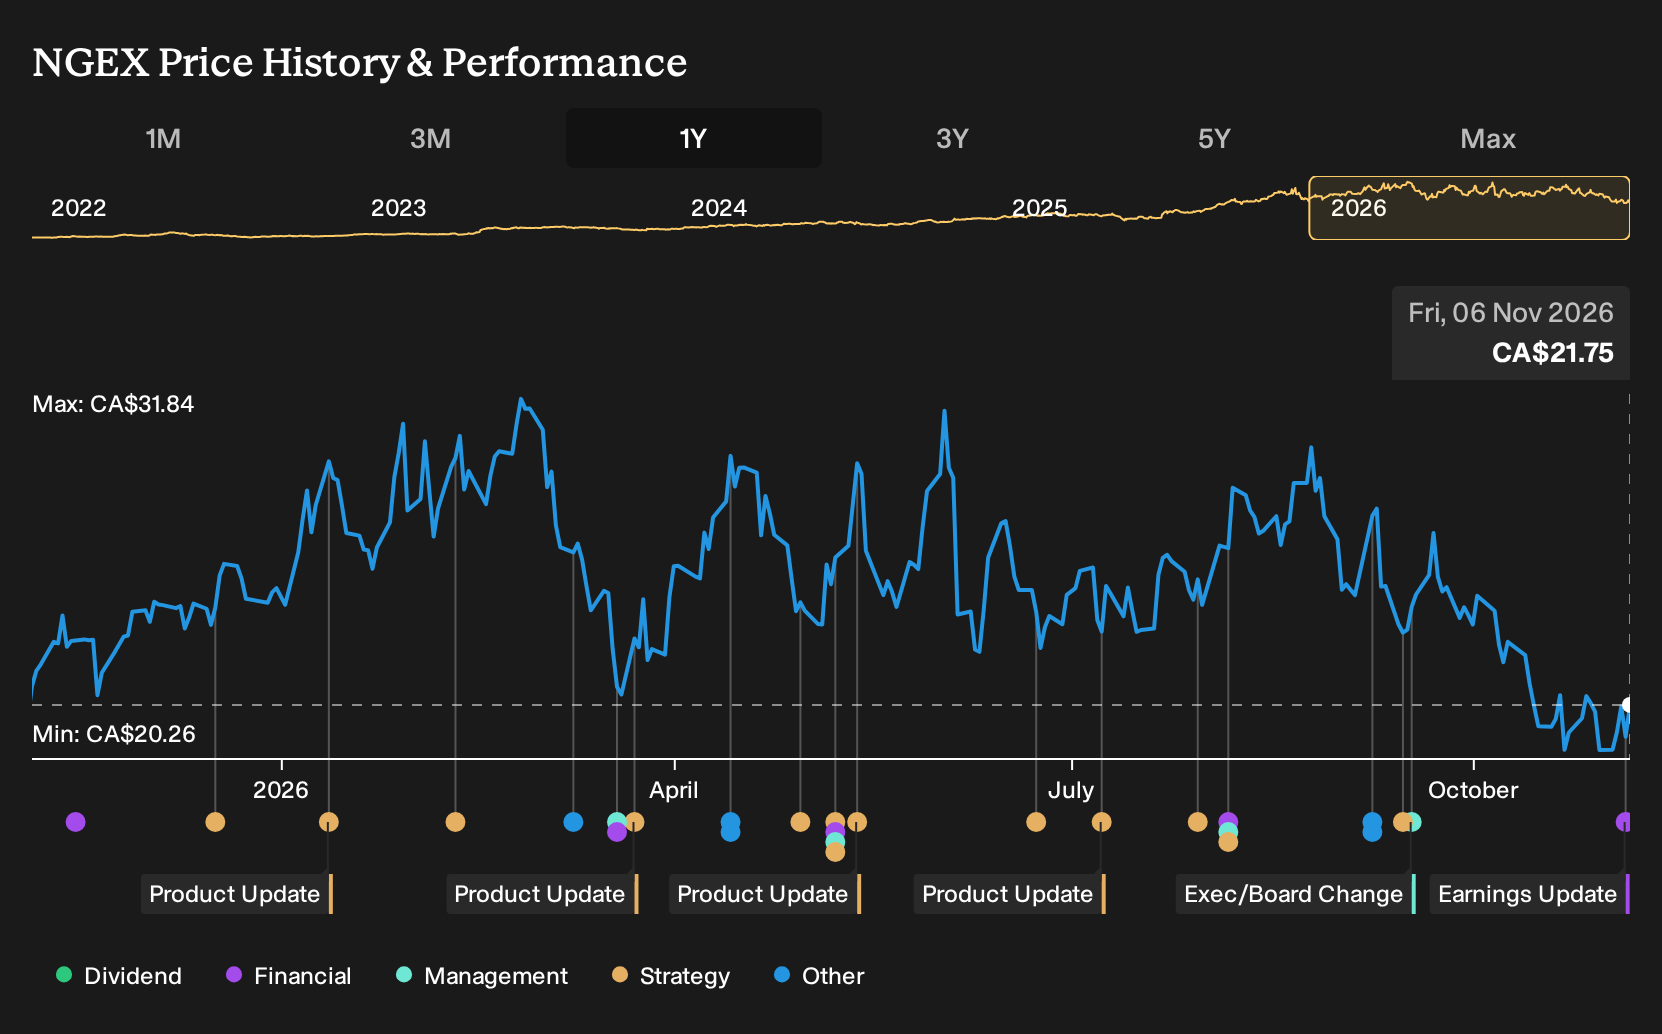
The earnings update for the quarter to 30 September 2026 is the key piece of news here. NGEx Minerals reported a quarterly loss of C$16.14 million and a nine month loss of C$80.26 million, both lower than the prior year. Loss per share also improved. That points to controlled spending or timing effects, but the business still runs without operating revenue.
For you, the relevance is about funding runway and execution capacity on core catalysts. Phase 5 drilling and the Lunahuasi adit need consistent capital to keep momentum, while the Valiente Resources spin out adds another workstream to manage. The slightly smaller loss helps sentiment, although the fundamental risk around exploration outcomes and schedule slippage remains intact.
NGEx Minerals' current story uses analyst assumptions that revenue could reach CA$510.5 million and earnings CA$160.4 million by 2029. That implies yearly revenue growth from essentially zero and an earnings swing of about CA$291.3 million from current earnings of a CA$130.9 million loss.
Uncover how NGEx Minerals' fair value indicates a 64% potential upside to its current price. This highlights a valuation gap that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between 35.51 and 63.43, which shows how differently retail investors are framing NGEx Minerals. Some focus on the funding in place and the Lunahuasi drill and adit plans. Others are more conscious of exploration risk and the chance of project delays weighing on execution.
Explore 3 other NGEx Minerals fair value estimates, including one that suggests as much as 192% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your NGEx Minerals research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NGEx Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NGEx Minerals' overall financial health at a glance.
Looking for more NGEx Minerals style investment ideas?
If you like the high conviction story around NGEx Minerals but want a broader watchlist, it can help to scan for other companies that match the type of risk and return profile you prefer.
- For investors who want potential mispricings with stronger fundamentals on their radar, run a screen of 6 high quality undervalued stocks and see which companies line up with your preferred balance of quality and price.
- If capital preservation sits high on your priority list, you can focus on resilience first and return second by filtering for 9 resilient stocks with low risk scores that might better suit a steadier approach.
- When you want sturdier finances behind the story, concentrate on balance sheet strength by scanning a list of solid balance sheet and fundamentals (5 results) and shortlisting the candidates that fit your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com