


EN
Lundin Mining Stock Has The Bull Case Changed After An Earnings Beat
- Lundin Mining reported third quarter 2026 sales of US$1,109.2 million and net income of US$235.2 million, with basic EPS from continuing operations of US$0.27, and updated its 2026 copper production and cash cost guidance alongside a confirmed quarterly dividend of C$0.0275 per share.
- The latest results show higher earnings and revenue than the same quarter a year earlier despite lower quarterly copper and molybdenum output. This puts the focus on pricing, mix, and cost control as key levers in Lundin Mining's current earnings profile.
- We will now look at how Lundin Mining's investment narrative could be influenced by the earnings beat and updated 2026 guidance.
Scan Lundin Mining’s earnings beat alongside hand-picked copper peers by running the 16 top copper producer stocks for potential producers reacting differently to the same commodity backdrop.
Lundin Mining Investment Narrative Recap
To own Lundin Mining, you need to be comfortable with a copper focused portfolio that leans heavily on South American assets and a long build out in the Vicuña district. The latest quarter shows the business producing lower copper and molybdenum volumes while still reporting higher sales and earnings, which keeps the spotlight on costs and realized pricing.
The biggest near term swing factor remains operational execution at core mines like Candelaria, Caserones and Chapada, especially around recoveries and weather exposure in Chile. Management’s updated 2026 copper and cash cost guidance sets near term expectations. If operations track that range, the earnings beat is supportive. If not, cost inflation and outages stay front of mind.
The most relevant update here is Lundin Mining’s revised 2026 copper production guidance of 285,000 to 310,000 tonnes with cash costs targeted between US$1.95 and US$2.15 per pound. This sits alongside confirmation that production remains in line with the previous annual range of 135,000 to 145,000 tonnes for the period referenced.
That guidance matters more than the single quarter beat because it frames how you think about Lundin Mining’s ability to fund Vicuña and brownfield projects from internal cash generation. It also interacts directly with the key risks already present, including Chile specific weather and regulatory issues and processing performance at assets like Caserones.
Lundin Mining Analyst Assumptions and Valuation Check
Lundin Mining’s analyst playbook is built on shrinking headline revenue, lower profit margins and a very specific earnings path into the late 2020s. Consensus forecasts point to revenue declining by 1.1% a year over the next three years, with profit margins easing from 29.2% today to 24.8% in 2029. Against that backdrop, analysts model earnings today at about US$1.4b and expect this to move to US$1.1b by 2029, while the most cautious forecasts in the group drop that figure to US$592.4m. The same set of projections assumes a modest 0.61% yearly reduction in the share count, which would slightly lift earnings per share if profits track those estimates.
Lundin Mining's narrative projects US$4.5b revenue and US$1.1b earnings by 2029. This rests on a 1.1% yearly revenue decline and an earnings decrease of about US$300m from current earnings of roughly US$1.4b.
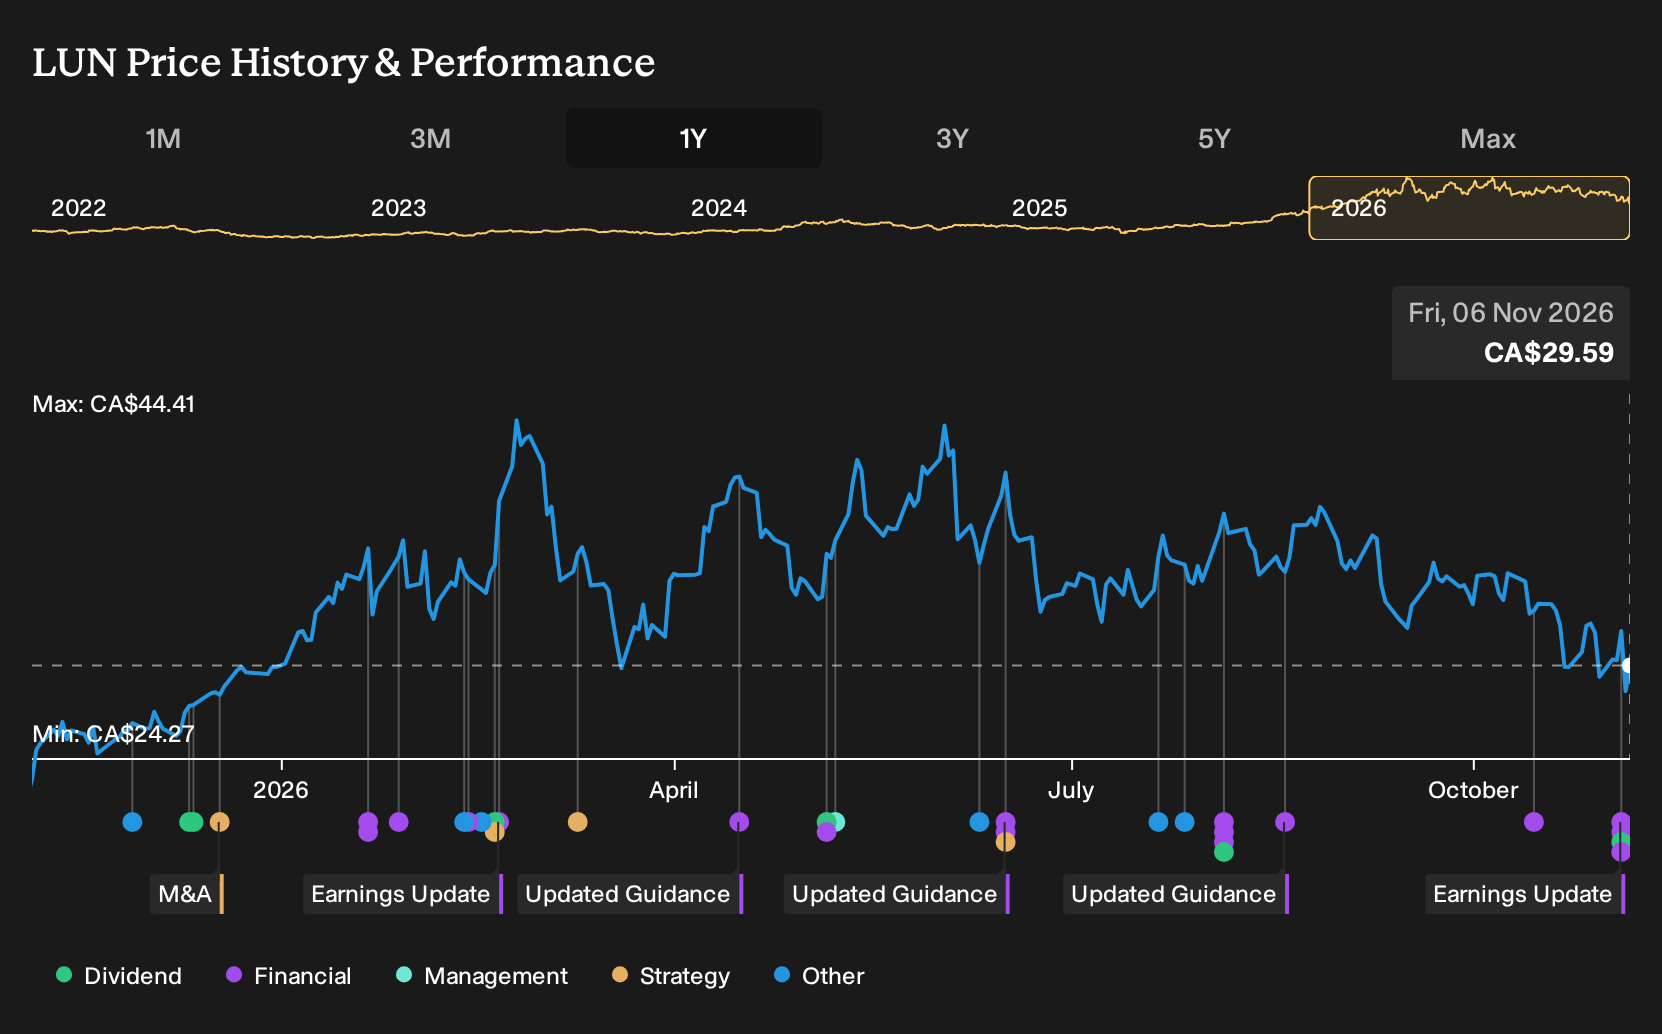
The valuation bridge that ties these estimates together is demanding. To line up with the consensus view, you would need to assume Lundin Mining reaches US$1.1b of earnings in 2029 and trades on a P/E of 29x at that point, almost double the current multiple of 14.2x and above the GB Metals and Mining sector at 14.5x. On the revenue side, the same scenario requires the business to generate US$4.5b of sales while profit margins settle closer to 24.8%, which is lower than today’s margin profile. Those inputs are what underpin a consensus price target of C$43.02 per share, with a bullish case at C$53.28 and a cautious case at C$32.57 against a recent share price of C$31.57.
For you as an investor, the key question is not whether the consensus target is right or wrong, but whether the path implied by those numbers feels reasonable. The market today prices Lundin Mining below the average analyst target even though that target is built on declining revenue and lower profitability. That gap suggests analysts see more value in the copper heavy asset base, the Vicuña build out and the current project pipeline than the share price reflects. Your task is to decide how much weight to give to the 2029 revenue and earnings markers, the higher implied P/E, and the risks around South American concentration, weather disruption and processing performance before you lean on those figures in your own work.
Uncover why Lundin Mining's fair value indicates a 45% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view treats Lundin Mining’s copper growth pipeline as the real catalyst. Before this earnings beat, the most optimistic analysts were mapping out revenue of about US$5.5b and earnings near US$1.2b by 2029 on a higher P/E. Those projections were set without this quarter’s update, so your own view may shift as you compare narratives.
Explore 3 other Lundin Mining fair value estimates, including one that suggests potential upside of up to 313% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Lundin Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lundin Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lundin Mining's overall financial health at a glance.
Looking for more Lundin Mining style investment ideas?
If Lundin Mining is on your radar, it can help to compare it with other opportunities that match different risk and return profiles. The Simply Wall St Screener lets you scan the market quickly using focused filters so you can line up alternatives that fit your own approach.
- For investors who want potential upside paired with disciplined financials, consider starting with a 7 high quality undiscovered gems that may not be widely followed yet.
- If capital preservation and balance sheet strength sit at the top of your checklist, filter for companies using a 9 resilient stocks with low risk scores to narrow the field to businesses with lower risk scores.
- When you want resilient fundamentals and less fragile finances, use the list of solid balance sheet and fundamentals (5 results) to focus on stocks with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com