


EN
How Raised Earnings Guidance Will Impact Vistra (VST) Investors
- Vistra reported third quarter 2026 results with sales of US$6.35b and net income of US$1.14b, alongside higher year to date revenue and profit compared with the prior year.
- Management paired these earnings with raised adjusted EBITDA guidance, a larger buyback program and fresh capacity from the Cogentrix acquisition. Taken together, these developments may reshape how investors view Vistra’s future cash generation profile.
- The focus now turns to how Vistra’s upgraded earnings guidance and capital return plans may influence the longer term investment narrative.
Scan how Vistra’s fresh guidance and buyback plans compare with other potential power plays by checking the hand picked 40 power grid technology and infrastructure stocks aligned with the energy and grid upgrade theme driving this story.
Vistra Investment Narrative Recap
To back Vistra, you need to be comfortable with a story built around rising power demand, data center and hyperscaler contracts, and a larger generation fleet that now includes the Cogentrix assets. The latest quarter showed higher sales and net income versus last year, alongside stronger adjusted EBITDA guidance that supports this thesis operationally.
The flipside sits in Texas policy risk and power pricing. Election results raised questions around future data center growth, while soft wholesale prices and hedge related earnings volatility remain live issues. The upgraded outlook and hedging coverage help in the near term, but the biggest swing factor is still how regulation shapes long term load growth.
The fresh US$1.5b share repurchase authorization, combined with raised and narrowed adjusted EBITDA guidance for 2026 and new 2027 guidance, is the announcement that really ties this news together. It reflects Vistra’s record third quarter EBITDA and expanded 50,000 MW generation footprint after closing Cogentrix.
For you as a shareholder, that package places execution at the center of the story. The key question is whether Vistra can continue translating its larger and more diversified fleet, plus long dated contracts like the Meta nuclear deal, into the cash generation needed to support buybacks, manage debt and absorb potential Texas data center policy headwinds.
Vistra's current narrative is anchored in analyst expectations that revenues reach US$26.1b and earnings reach US$4.0b by 2029, based on revenue growing at 10.8% per year and forecast earnings increasing by US$2.0b from US$2.0b today.
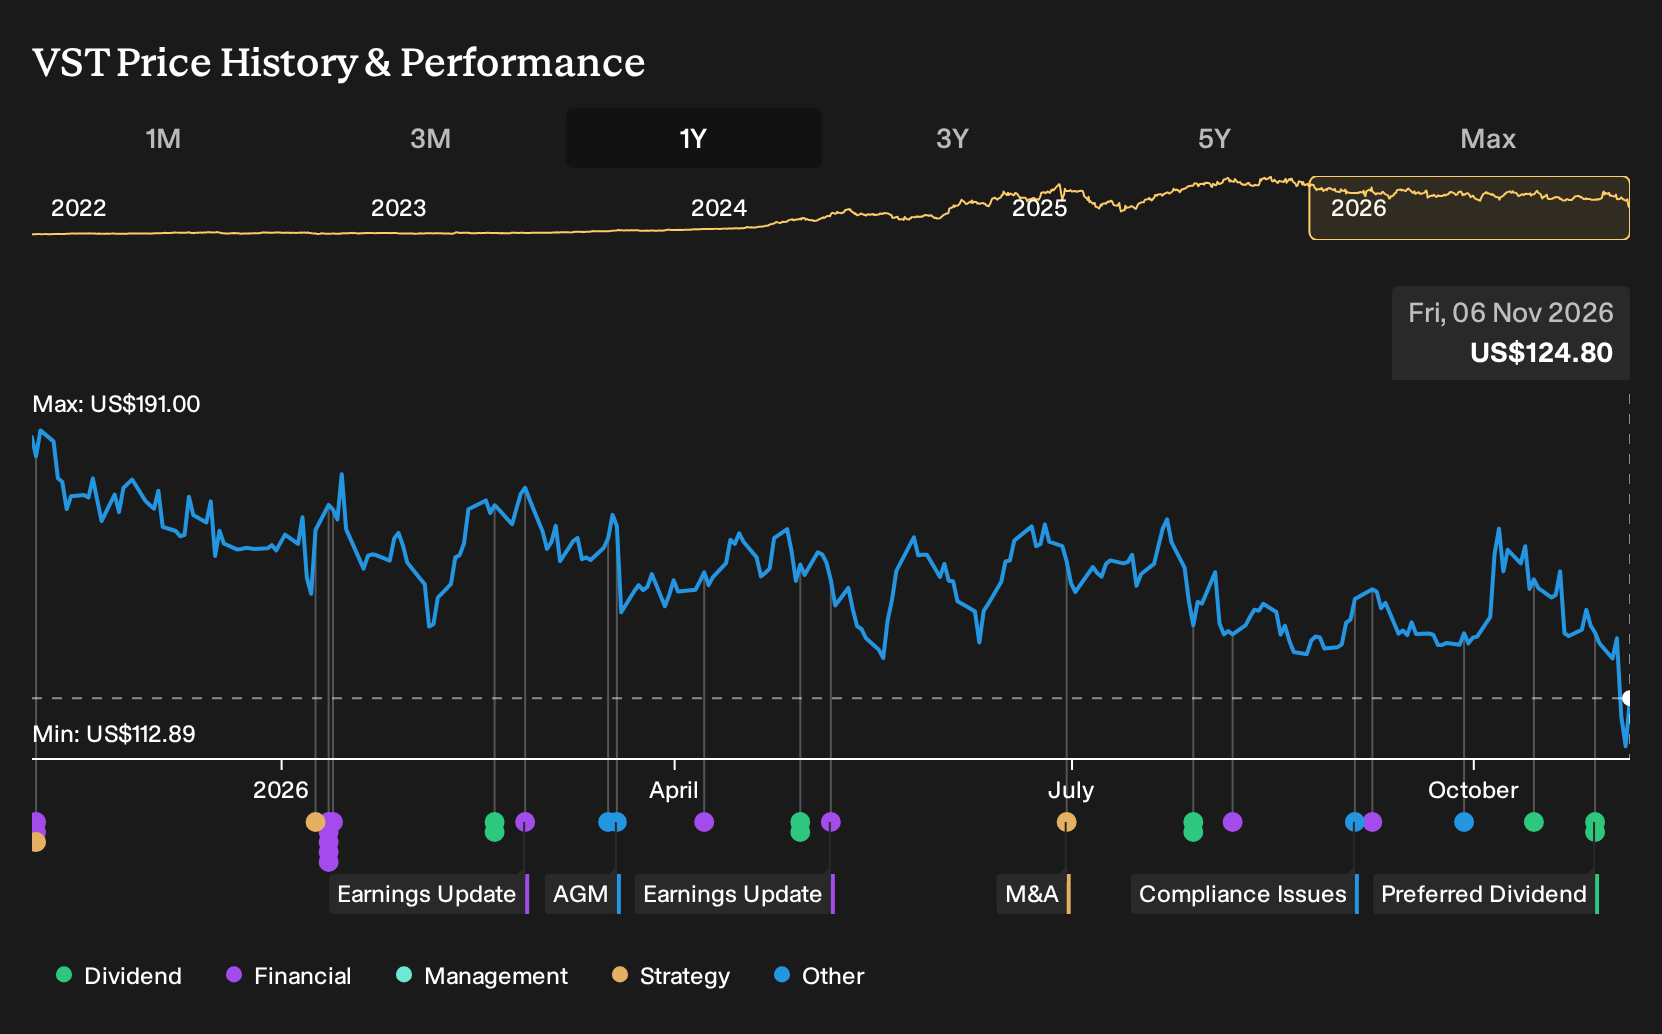
Uncover why Vistra's fair value indicates a 67% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most cautious analysts frame data center obligations as the real swing factor for Vistra. Before this earnings release, the lowest forecasts were built on revenue of about US$19.8b and earnings of roughly US$3.5b by 2029, a much more restrained path. That gap shows how far opinions can diverge, so it pays to explore several viewpoints.
Explore 13 other Vistra fair value estimates, including one that suggests it could be worth just $130.01.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vistra research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vistra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistra's overall financial health at a glance.
Looking for more investment ideas beyond Vistra?
If Vistra has sharpened your interest in the power and infrastructure theme, it can help to line it up against other companies with different strengths and risk profiles.
- If wealth preservation matters most to you, start by reviewing 32 resilient stocks with low risk scores that aim to keep volatility in check while still giving you equity exposure.
- If you care about durable cash flows and balance sheet strength, compare Vistra with our list of solid balance sheet and fundamentals (24 results) that already meet strict financial quality filters.
- If you are hunting for mispriced opportunities, scan through the 42 high quality undervalued stocks and see which companies the data suggests may be trading below their fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com