


EN
CAVA Group (CAVA) Could Be 27% Undervalued After Its Third Quarter Earnings Miss
CAVA Group (CAVA) is back in focus after third quarter 2026 results showed sales of US$356.44 million and earnings of US$0.11 per share, slightly below analyst expectations and accompanied by softer profitability.
The mixed third quarter has checked some of CAVA Group’s earlier momentum, with the share price falling 3.2% on the day of the release, but still posting a 14.0% 1‑month share price return and a 28.8% 1‑year total shareholder return.
Spot opportunities beyond CAVA Group by scanning a hand picked set of consumer facing growth stories in the 21 high quality undiscovered gems that share similar expansion and earnings pressure themes.
CAVA Group now trades well below where analysts had pencilled it in before this miss, yet the business is still opening restaurants at pace. Has most of the upside already played out, or is the market overreacting?
Most Popular Narrative: 27% Undervalued
CAVA Group closed at $60.01, compared with a narrative fair value of $82.75 that assumes a high bar for both expansion and execution quality.
The main thing that has to go right is that CAVA continues to execute well in its restaurants as it scales, including developing enough leaders through programs like Flavor Your Future and maintaining strong hospitality and food safety while adding catering and other revenue channels.
Current valuation implies the share price already reflects continued rapid unit growth, solid restaurant level margins in the mid 20s and effective use of cash including the US$100m buyback, so the stock appears priced for strong execution rather than for disappointment.
See why 73 investors see CAVA Group as 27% undervalued.
Result: Fair Value of $82.75 (UNDERVALUED)
Still, the CAVA Group story relies on tight execution as it opens more locations, and on avoiding renewed food safety issues that could weigh on traffic and earnings.
Find out about the key risks to this CAVA Group narrative.
Another View: CAVA Group Through The P/E Lens
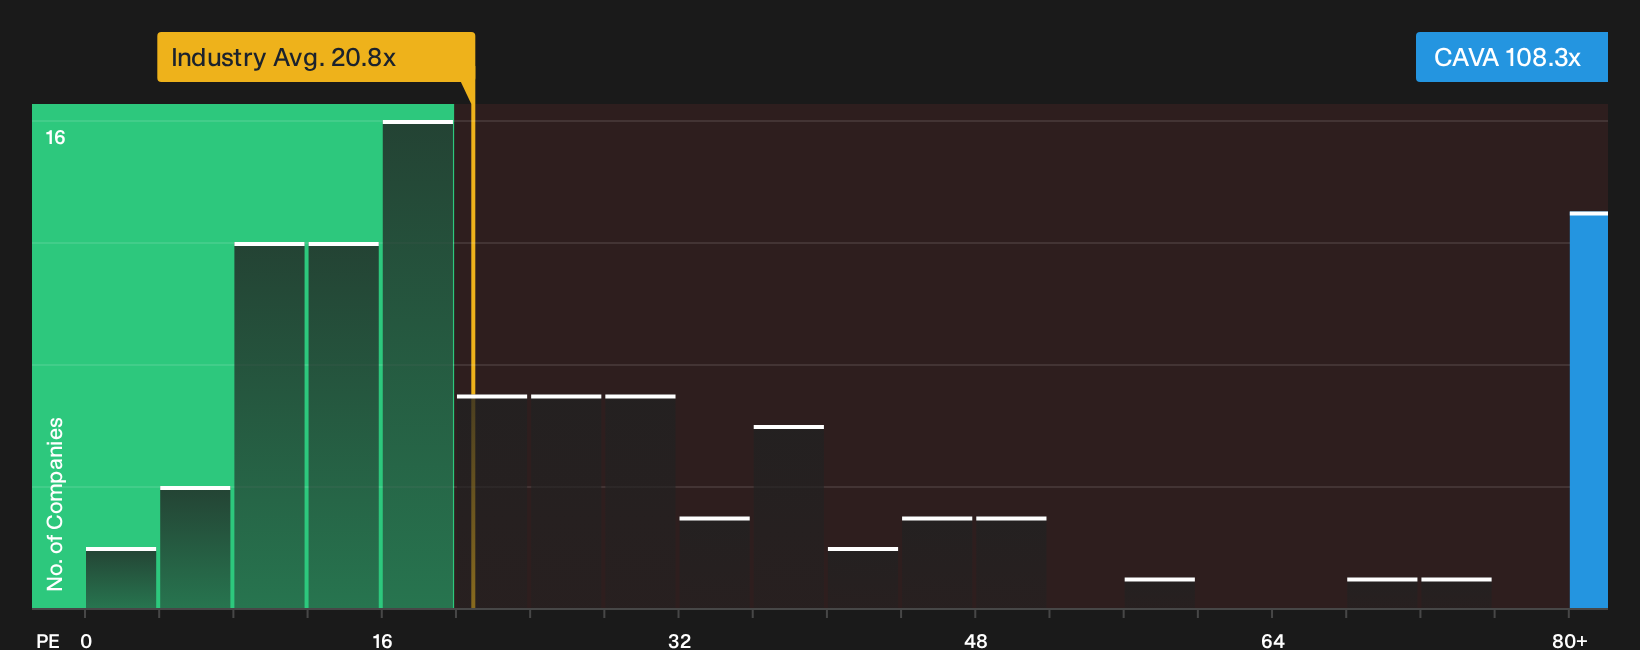
The narrative fair value paints CAVA Group as 27% undervalued, yet the market multiples tell a tougher story. The stock trades on a P/E of 108.3x, compared with a fair ratio of 30.7x, a peer average of 50.3x and a US Hospitality sector level of 20.8x.
That kind of premium leaves far less room for execution hiccups or slower unit growth, since even small disappointments could trigger a sharp reset toward the fair ratio or industry levels. The key question is whether you see that gap as valuation risk or a price worth paying for the growth profile.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around CAVA Group feels familiar, act while the data is fresh and form your own view with the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond CAVA Group?
If CAVA Group has sharpened your appetite for focused research, do not stop with a single stock when a broader watchlist could sharpen your decisions.
- Target stability first by reviewing companies screened for resilient fundamentals and low risk profiles in the 32 resilient stocks with low risk scores.
- Hunt for mispriced quality by scanning the 42 high quality undervalued stocks and see which businesses combine stronger financials with potentially attractive entry points.
- Build a sturdier core to your portfolio by checking the list of solid balance sheet and fundamentals (24 results) and focus on companies with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com