


EN
What EMCOR Group Stock's Raised Outlook Means For Shareholders
- EMCOR Group reported strong third quarter and nine month 2026 results, with higher sales, net income, and earnings per share. The company raised full year revenue guidance to US$20.6b to US$21.0b and highlighted record remaining performance obligations of US$18.57b.
- Beneath the headline figures, the business showed particular strength in core mechanical and electrical construction and U.S. building services, even as it absorbed a US$34 million non cash impairment tied to an energy efficiency performance contracting subsidiary.
- We will now look at how EMCOR Group's investment narrative could be shaped by raised full year guidance and record backlog.
Scan EMCOR Group’s raised guidance alongside other potential breakouts in complex infrastructure and building services by reviewing the hand picked 40 power grid technology and infrastructure stocks shaping this part of the market.
What Is EMCOR Group's Investment Narrative?
To own EMCOR Group, you have to be comfortable with a construction and services platform that lives or dies on execution quality and project selection. The raised 2026 revenue guidance, record US$18.57b remaining performance obligations and strong mechanical, electrical and U.S. building services performance point to healthy demand and pricing right now. In the short term, the key swing factors are whether crews can be staffed efficiently, complex work like data centers can be delivered on schedule and that sizeable backlog can be turned into cash without heavy cost overruns.
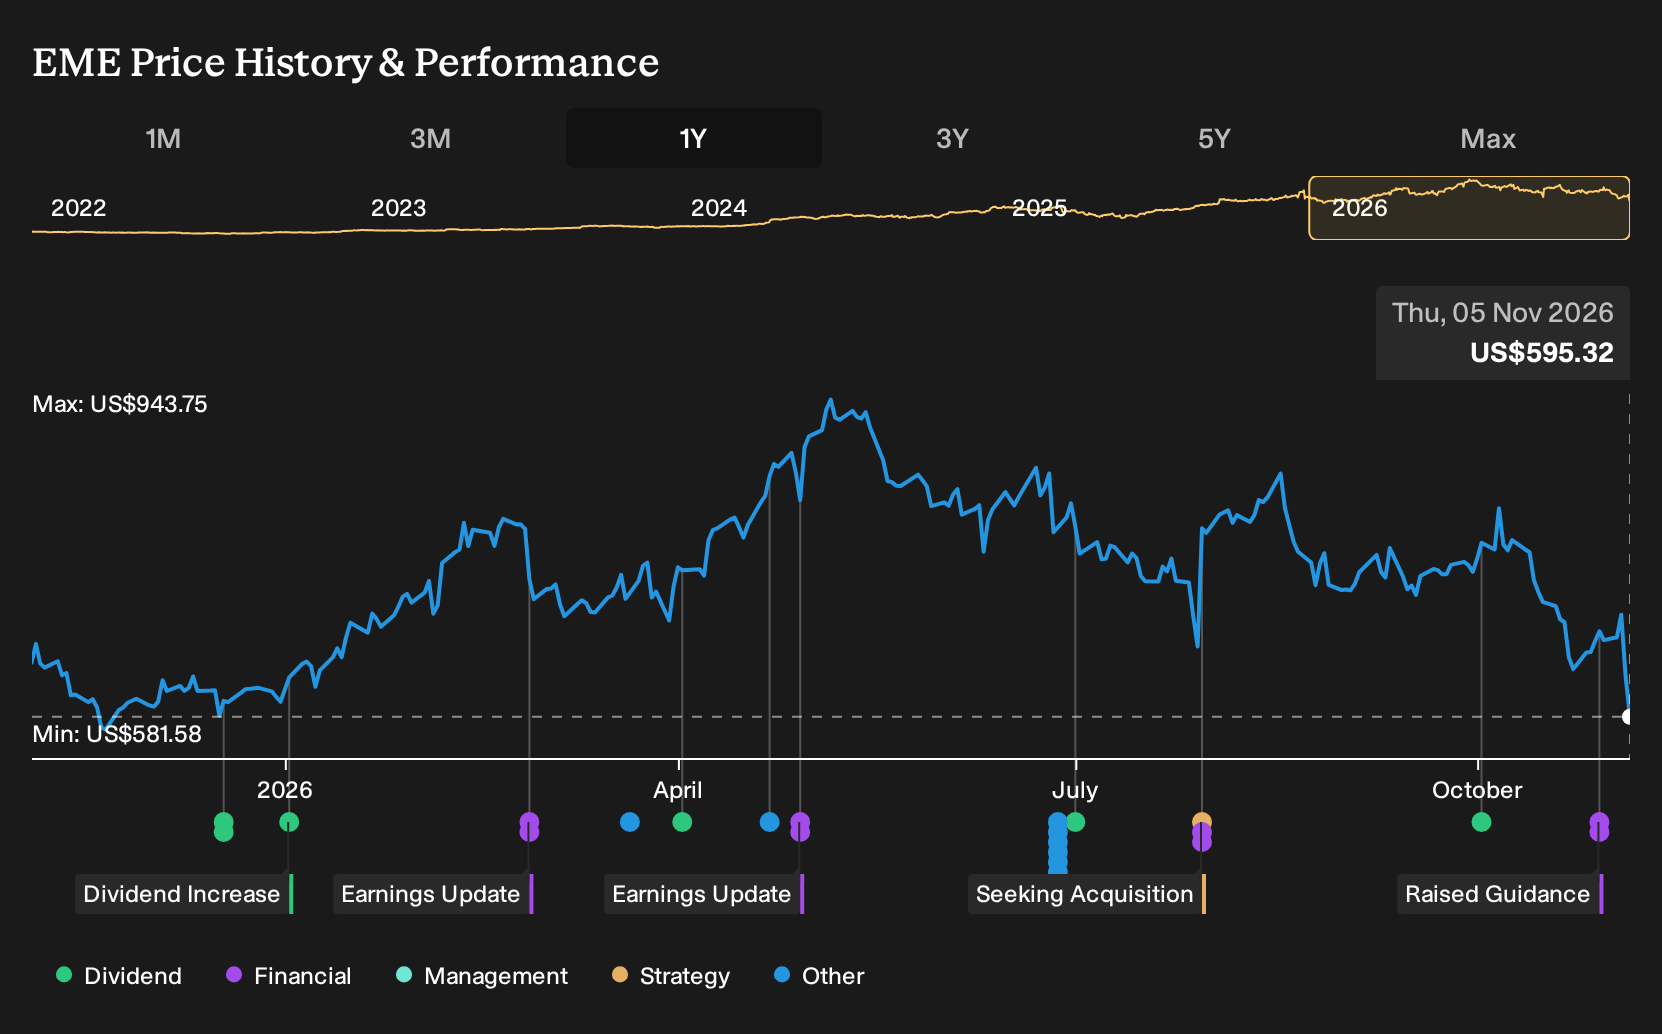
The recent non cash US$34m impairment in the energy efficiency contracting unit is a reminder that not every bet pays off, even inside a strong quarter. Shares have fallen sharply over the past month despite higher earnings and upgraded guidance. This suggests investors are already wrestling with execution risk, capital needs on large, multi year builds and customer concentration in data centers. If EMCOR Group keeps converting that record workload into margins and cash, the story looks straightforward, yet the room for disappointment on any of those fronts is real.
That said, the clean headline story around guidance and backlog looks different once you consider ...
There's only one way to know the right time to buy, sell or hold EMCOR Group. Head to Simply Wall St's company report for the latest analysis of EMCOR Group's Fair Value.
Exploring Other Perspectives
One optimistic twist on EMCOR Group focuses on the AI and cloud data center boom. The most bullish analysts were already penciling in revenue of about US$27.8b and earnings of roughly US$2.3b by 2029, before this guidance hike. That is a very different story from cautious views, and it is exactly why you may want to compare several competing narratives.
Explore 5 other EMCOR Group fair value estimates, including one that suggests up to 168% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your EMCOR Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for EMCOR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EMCOR Group's overall financial health at a glance.
Looking For More EMCOR Group Style Investment Ideas?
If EMCOR Group has sharpened your interest in complex infrastructure, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you move from a single stock story to a watchlist of candidates that share the traits you care about most, whether that is resilience, income or potential mispricing.
- If capital preservation comes first for you, start with a basket of companies that our filters flag as relatively resilient by financial risk metrics through 32 resilient stocks with low risk scores.
- If income is your priority, focus on businesses that pair higher yields with supporting fundamentals by reviewing a curated set of 6 dividend fortresses.
- If you want to hunt for potential bargains with stronger underlying quality, broaden your research to a hand picked 42 high quality undervalued stocks that may merit a closer look alongside EMCOR Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com