


EN
Shift Into GEAR Plan Might Change The Case For Investing In CarMax (KMX)
- CarMax has laid out its Shift into GEAR roadmap through 2030, targeting mid single digit used retail volume growth and mid teens adjusted EPS growth through operational efficiencies, digital upgrades and an expanded finance and protection product mix.
- The plan leans heavily on higher contribution from CarMax Auto Finance, stronger extended protection plan economics and cost savings in reconditioning and logistics to support sharper pricing while aiming to protect margins.
- We will now look at how CarMax's Shift into GEAR cost discipline and efficiency push could reshape the broader investment narrative.
CarMax Investment Narrative Recap
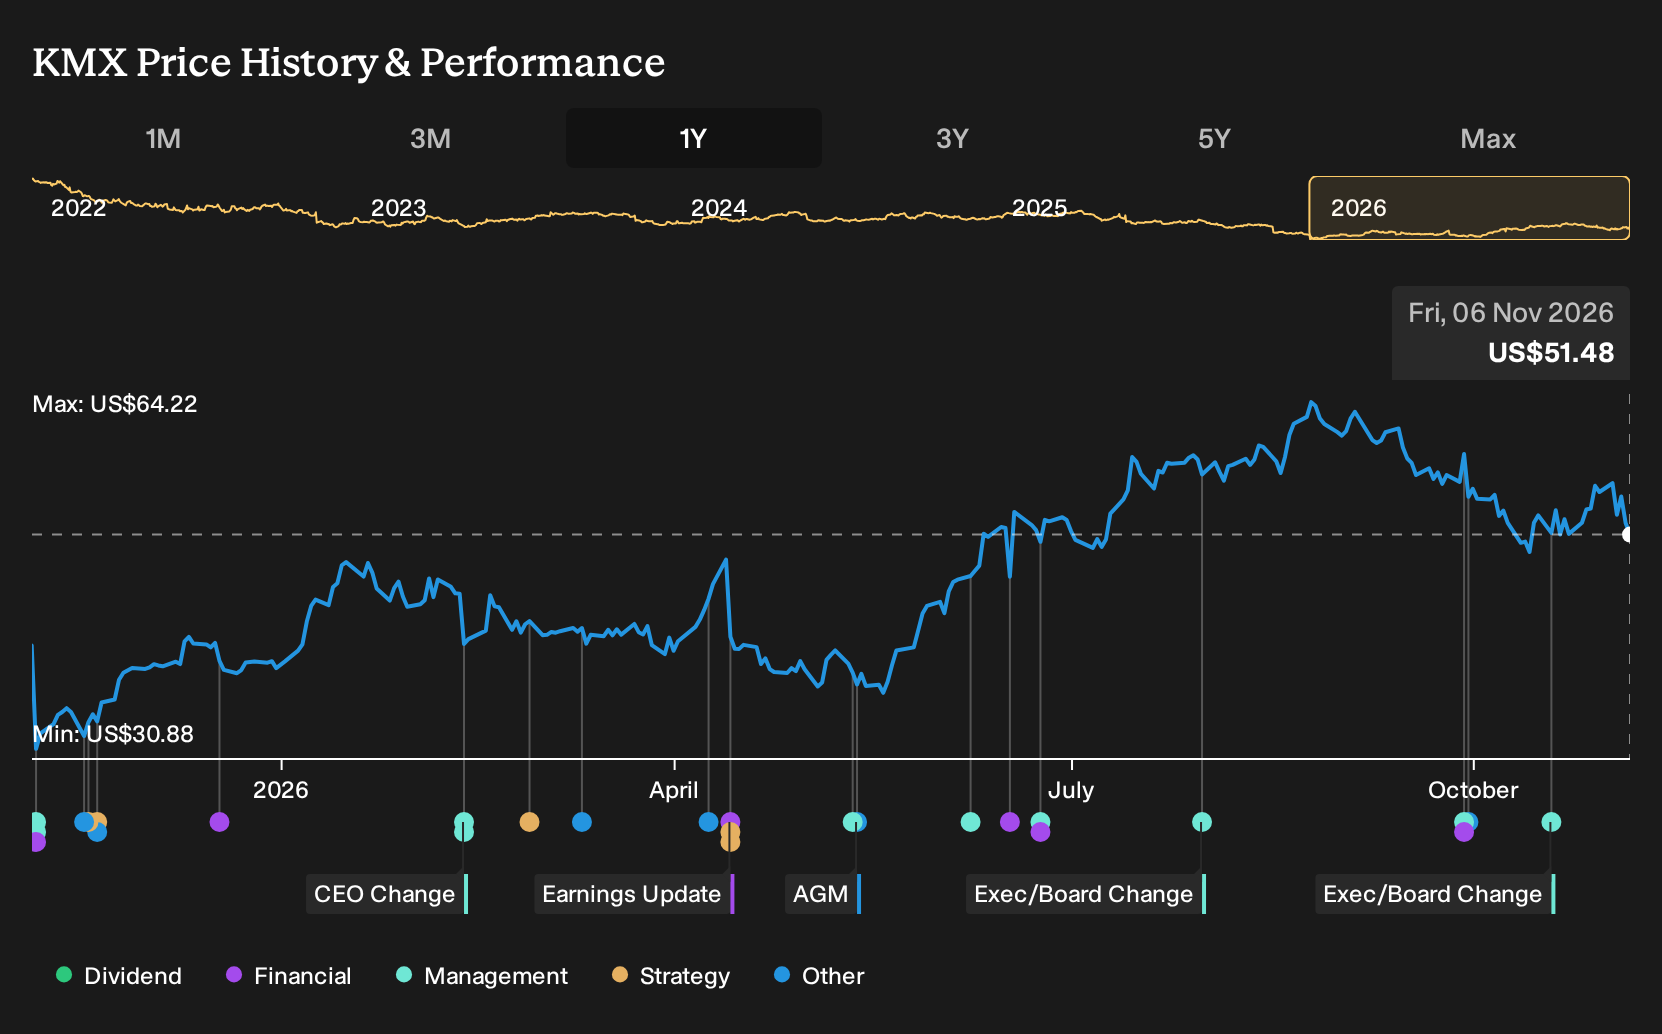
To own CarMax, you need to be comfortable that the Shift into GEAR plan can translate a richer product mix, digital progress and SG&A savings into steadier earnings, even though recent history has been choppy. In the near term, the main swing factor is whether operational efficiencies really offset pressure on retail and wholesale profit per unit.
The biggest risk right now is that weaker unit economics and higher credit loss provisioning at CarMax Auto Finance blunt that earnings rebound while the stock still trades around a premium 26.8x P/E. The latest roadmap does not remove that risk, but it gives investors clearer milestones to watch on costs and margins.
The most relevant update is the detailed Shift into GEAR roadmap that ties operational projects to a 2030 earnings framework. That plan relies on higher contribution from CarMax Auto Finance, stronger economics from extended protection plans, and lower logistics and reconditioning costs to support sharper pricing while trying to protect profitability.
For catalysts, the key question is execution on those cost initiatives and the full credit spectrum strategy without letting loss reserves or weaker profit per unit erode the benefit. With CarMax already trading at a higher P/E multiple than many specialty retail peers, any stumble on GPUs, credit performance or SG&A savings could quickly become important for the equity story.
What The CarMax Consensus Is Really Pricing In
CarMax's narrative projects US$29.7b revenue and US$811.7m earnings by 2029. This builds on analyst assumptions that the top line will stay roughly flat each year while profit margins shift. It also implies earnings would need to rise by about US$519m from the current US$292.4m base.
Uncover why CarMax's fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate CarMax storyline zooms in on loan loss provisioning. The most cautious analysts saw heavier reserves and only US$28.8b revenue and US$502.6m earnings by 2029 as a real risk, compared with the higher consensus path. Those estimates were set before this news, so you may see those views shift meaningfully from here.
Explore 5 other CarMax fair value estimates, including one that suggests as much as 57% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CarMax research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CarMax. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CarMax's overall financial health at a glance.
Looking For More Investment Ideas Beyond CarMax?
Once you have formed a view on CarMax, it can help to cross check that thinking against opportunities in completely different corners of the market using the Simply Wall St Screener.
- If you want potential upside with a strict focus on financial resilience, filter for sturdier balance sheets and supportive cash flows through our list of solid balance sheet and fundamentals (24 results).
- For readers hunting for mispriced quality, compare CarMax's set up with companies that pair strong fundamentals with more grounded valuations using this curated 42 high quality undervalued stocks.
- Income focused investors who care about consistency as much as yield can scan a hand picked pool of higher payout opportunities through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com