


EN
Computershare And 2 Other Australian Dividend Stocks To Watch
High inflation in the United States has pushed central banks to keep interest rates higher for longer, which has put reliable income back in the spotlight for many Australians. Regular dividends paying more than 3% can help smooth out the ride when markets feel jumpy. This article walks through three higher yielding Australian dividend stocks from our quality screen that income focused investors may want to keep on their radar.
The three stocks highlighted here offer a compelling starting point if you want exposure to dividend powerhouses with yields above 3% that are covered, growing and relatively stable. However, if you want the standouts, these 5 dividend aristocrats stocks are the most outstanding.
Computershare (ASX:CPU)
Overview: Computershare runs share registries and corporate trust services that help listed companies manage shareholder records, dividends and employee share plans worldwide.
Operations: The group generates most revenue from Issuer Services at about US$1.3b and Corporate Trust at about US$1b across primarily US and UK markets.
Market Cap: A$24.9b
Computershare fits the Dividend Powerhouses theme through its role in keeping dividend flows running smoothly, while its own payout track record and earnings engine give income investors plenty to think about.
"Margin income declined by 5.4% during the half, although Computershare subsequently increased its FY26 margin-income guidance to approximately US$740 million due to higher-than-expected client balances."
What really matters for dividend focused investors is how one evolving revenue lever shapes future cash generation and payout headroom.
That shifting margin income lever is only the starting point, and the full narrative for Computershare shows how Computershare’s broader cash engine and risks could reshape its dividend profile.

BHP Group (ASX:BHP)
Overview: BHP Group is a global resources company that mines iron ore, coal, copper and other minerals used in steel and electrification, with iron ore and steelmaking coal helping fund its dividend profile.
Operations: BHP generates most revenue from Copper at about US$29b, Iron Ore at about US$24b and Coal at about US$6b, with China its largest customer market.
Market Cap: A$292.9b
For income seekers, BHP Group matters because its iron ore and metallurgical coal cash engines sit behind a sizeable, policy driven dividend. Copper and potash projects aim to keep that payout supported over time.
"A strong pipeline of copper and potash projects positions BHP Group to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to influence future revenues."
What really counts for dividend investors is how one unresolved execution and cost pressure ultimately flows through to cash generation and payout headroom.
That execution risk is only half the story, and the full narrative for BHP Group shows how BHP Group’s capital choices and cost discipline could reshape its long term income appeal.

Monadelphous Group (ASX:MND)
Overview: Monadelphous Group provides engineering construction and, crucially for income investors, recurring maintenance and industrial services for large resources and energy clients.
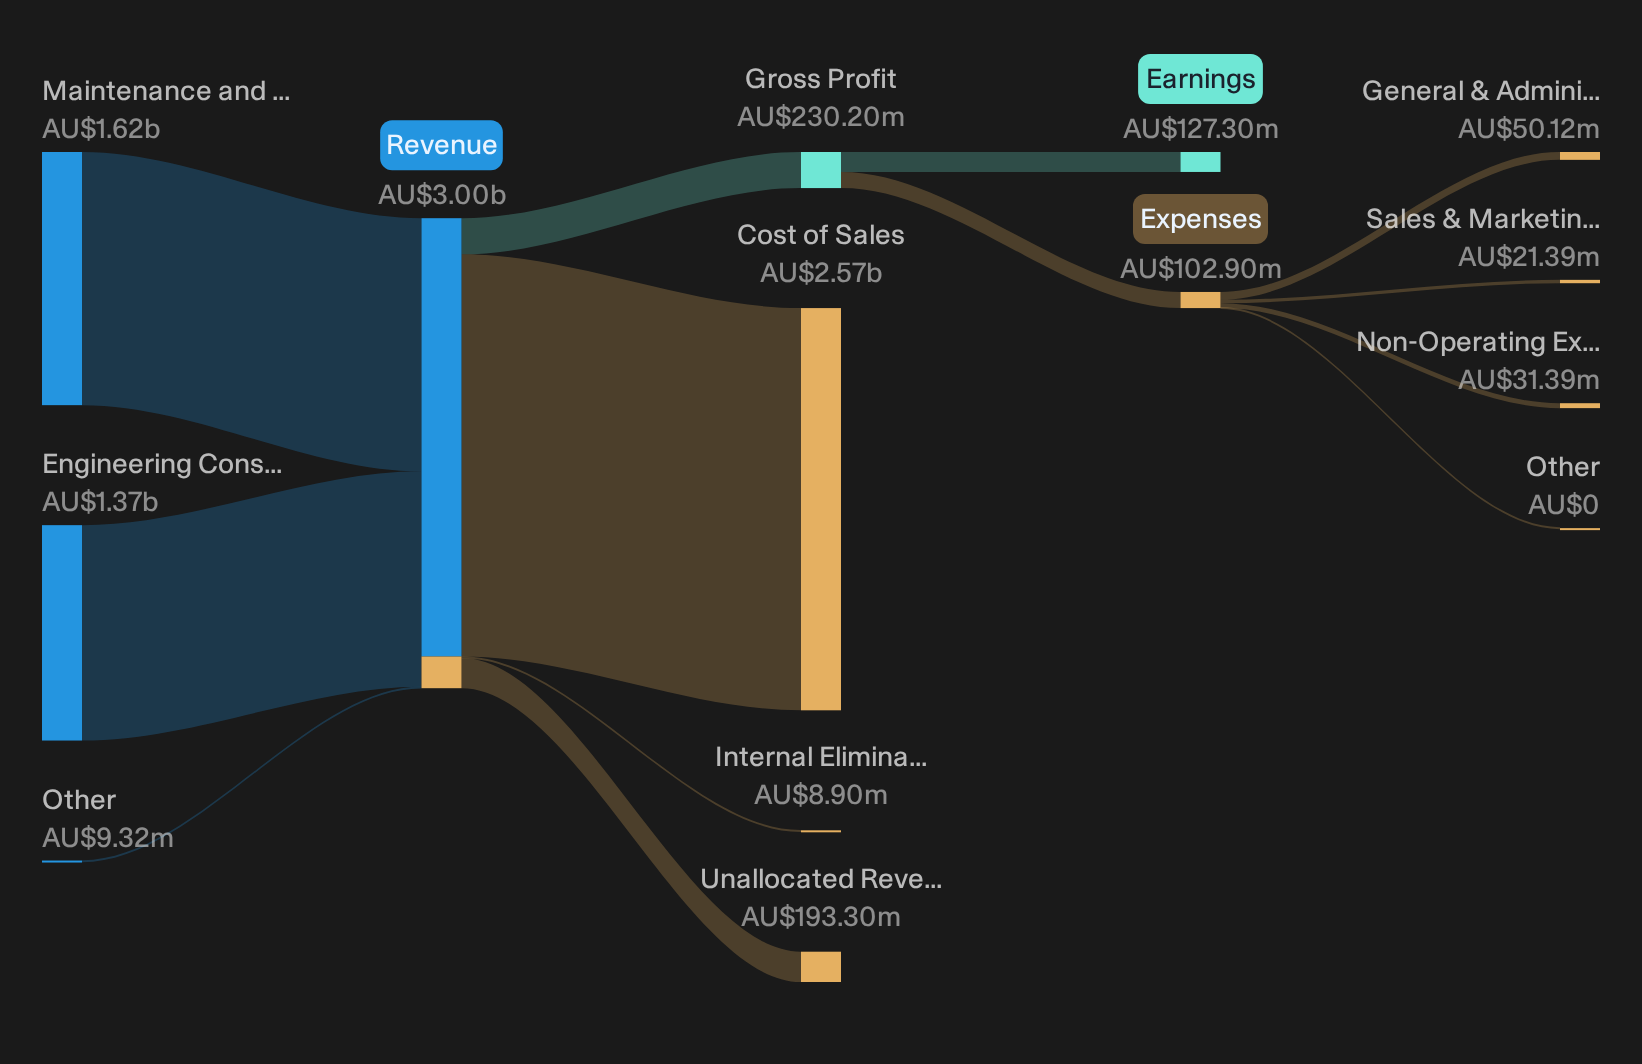
Operations: Monadelphous Group generates about A$1.6b from Maintenance and Industrial Services and A$1.4b from Engineering Construction, mostly across A$2.7b of Australian revenue.
Market Cap: A$2.9b
Monadelphous Group matters for the Dividend Powerhouses theme because its long term maintenance and industrial service contracts supply the kind of recurring cashflow that can help support covered, stable payouts above 3% through changing project cycles.
"Accelerating investment in decarbonisation and renewable energy infrastructure is now translating into tangible contract wins and a growing pipeline for Monadelphous Group, supported by more than A$2.7b of new awards and the build out of high voltage services. Sustained demand for construction and maintenance of critical minerals, energy and infrastructure assets, reflected in record Maintenance and Industrial Services revenue of A$1.61b and over A$1.6b of new iron ore and related work, supports a thick order book that can underpin future revenue and EBITDA for Monadelphous Group."
What really shapes Monadelphous Group’s dividend appeal over the next few years is how one subtle shift in contract mix filters through margins.
That contract shift is the real story, and the full narrative for Monadelphous Group unpacks how margins, capital discipline and payout capacity could be quietly decoupling from headline revenue.
Seeking Alternatives Before The Crowd?
Fresh ideas do not stay under the radar for long. Strong balance sheets and rising momentum can get caught quickly. Scan these curated lists while it matters and act now.
- Spot sturdier portfolios by zeroing in on companies with robust finances using this curated list of solid balance sheet and fundamentals (12 results) before the market fully prices in their resilience.
- Review 53 AI infrastructure stocks that could benefit as data demand and computing capacity keep building faster than many investors are watching.
- Target cash flow resilience by assessing 6 resilient stocks with low risk scores that screen well on stability metrics while attention is still skewed toward higher octane trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com