


EN
Bank of Communications (SEHK:3328) Trades At A 45% Discount As Q3 Profit Improves
Bank of Communications (SEHK:3328) is back in focus after reporting third quarter and nine month 2026 results, with higher net interest income and net income than a year earlier drawing fresh attention to the stock.
The earnings release has landed on a rising share price, with Bank of Communications now at HK$8.68 and supported by a 30 day share price return of 5.79% and a 90 day gain of 19.81%. Short term momentum sits on top of a much stronger backdrop, with the year to date share price return at 32.32%. Over longer horizons, the 1 year total shareholder return stands at 28.50%, while the 5 year total shareholder return is 156.97%. This suggests that investors have been steadily reassessing both growth prospects and risk around the bank over time.
Scan how Bank of Communications compares with other banks showing strong momentum and balance sheet strength using our curated list of solid balance sheet and fundamentals (192 results) today.
After this strong run and a HK$8.68 share price, the gap between where Bank of Communications trades and where valuation estimates cluster now matters more than the recent chart. So where does fair value really sit within that range?
Preferred P/E of 7x: Is it justified for Bank of Communications?
Valuation comes back to a simple question. Is paying 7x P/E for Bank of Communications at HK$8.68 reasonable when you compare it with the rest of the banking sector and its own fair ratio estimate?
The P/E multiple links what you pay today to the profit that the bank currently generates. For lenders, this is a common yardstick because earnings already reflect credit costs, funding conditions, and fee income in a single number that is easy to compare across peers.
Bank of Communications trades on a 7x P/E, which is higher than the Hong Kong Banks industry average of 5x. That suggests the market is willing to pay a premium relative to the wider sector for its earnings stream. At the same time, the 7x P/E is below the peer average of 8.3x and in line with the estimated fair P/E of 7x, which points to a level that the market could realistically move toward if sentiment or fundamentals change.
Explore the SWS fair ratio for Bank of Communications.
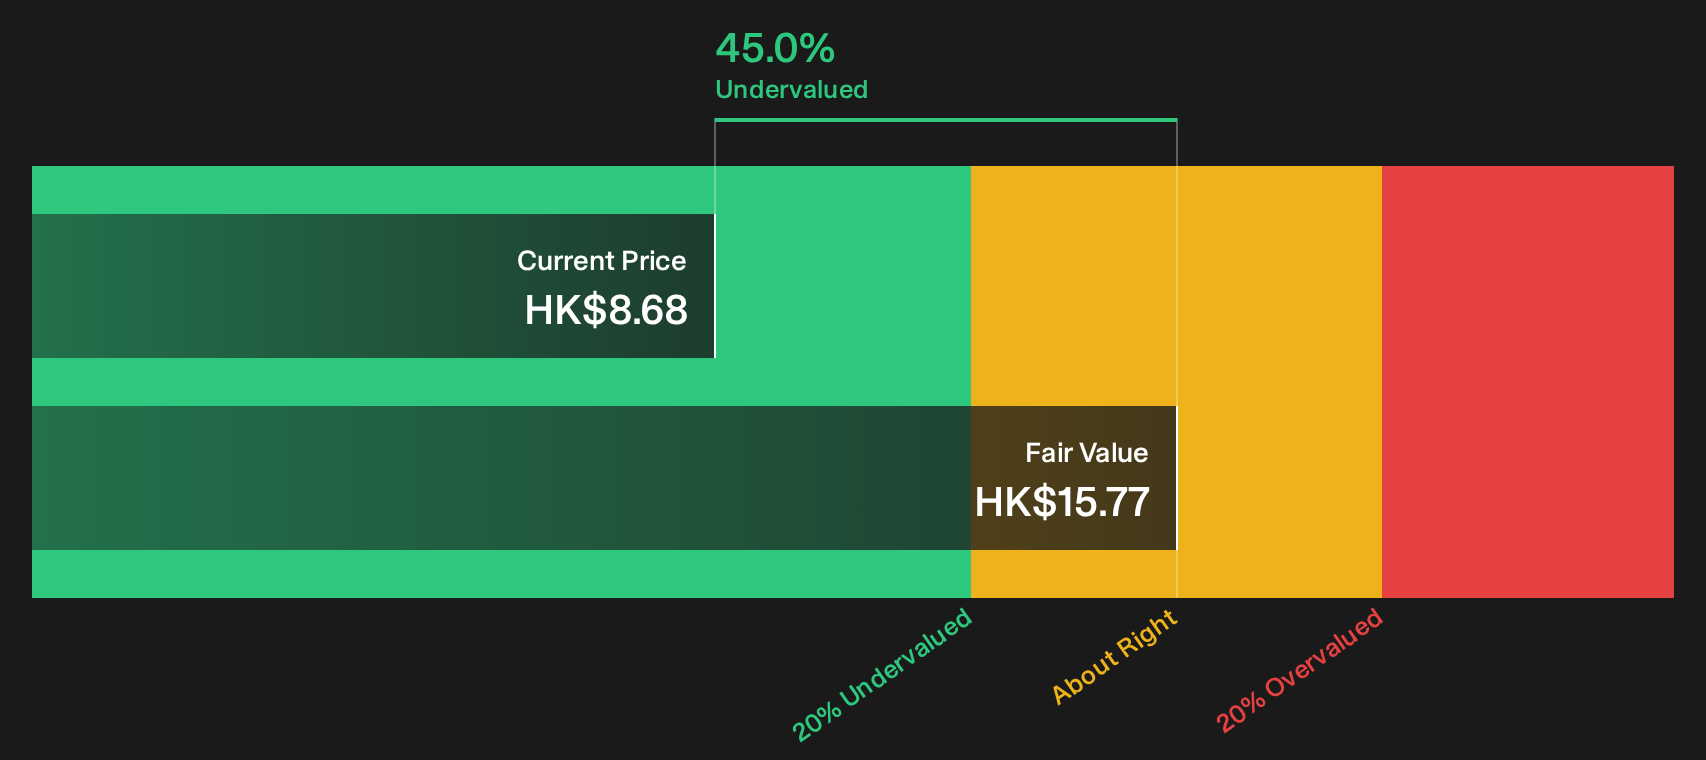
On top of this, the SWS DCF model flags a very different picture to the multiples. Bank of Communications is trading at HK$8.68 while the model estimates a future cash flow value of HK$15.77, which implies a wide gap between price and that cash flow based fair value. The approach projects future free cash flows and discounts them back to today using a chosen rate, which gives a single present value number in HK$ terms.
A DCF framework tends to matter most for established banks with meaningful earnings, such as Bank of Communications, because a large portion of their value is tied to relatively steady interest income and fee streams. Here, the model output suggests the market price assigns a lower value to those future cash flows than the DCF workup does, even though revenue and earnings forecasts in the statements remain moderate rather than aggressive.
Look into how the SWS DCF model arrives at its fair value.
Result: Price-to-earnings of 7x (ABOUT RIGHT)
Still, the Bank of Communications story can change quickly if credit costs rise or if funding conditions tighten and put pressure on both earnings quality and investor confidence.
Find out about the key risks to this Bank of Communications narrative.
Another View On Bank of Communications: Cash Flows Tell A Different Story
The P/E points to Bank of Communications trading roughly in line with its fair ratio estimate, yet the SWS DCF model presents a very different picture. At HK$8.68 against a future cash flow value estimate of HK$15.77, the shares screen as significantly undervalued on a cash flow basis.
This gap matters because it compares current earnings multiples with long term cash generation. If profit growth stays moderate and forecasts prove accurate, an important question is which lens deserves more weight when you think about valuation risk versus potential upside for Bank of Communications.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of Communications for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 228 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bank of Communications so far. If you want to move quickly and decide where you stand, start by weighing both sides of the story through 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Bank of Communications?
Bank of Communications gives you a useful reference point. The next smart move is to widen your watchlist and pressure test fresh ideas side by side.
- Target income resilience by checking out yield focused opportunities in the 230 dividend fortresses that can complement more growth oriented holdings in your portfolio.
- Hunt for quality at a discount by scanning the 591 high quality undiscovered gems and spotting companies the crowd has not fully focused on yet.
- Prioritise capital preservation first and then returns by reviewing the 214 resilient stocks with low risk scores before the best options move further out of reach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com