


EN
How a Slowdown in Commercial Bookings Is Rocking Palantir Stock
Palantir Technologies (PLTR) stock is under pressure despite another blowout quarterly performance, as investors zeroed in on a sharp slowdown in U.S. commercial bookings. The artificial intelligence (AI) software company reported third-quarter revenue of $2.31 billion, up 96% year-over-year (YOY), while U.S. commercial revenue surged 148% YOY to $984 million and surpassed U.S. government revenue for the first time. Yet U.S. commercial total contract value (TCV) rose just 11% YOY to $1.46 billion, a steep deceleration from the 153% growth recorded in the prior quarter.
The slowdown has raised concerns about whether Palantir can sustain the extraordinary growth rates embedded in its premium valuation. While management attributed the weaker bookings growth partly to customers signing shorter-duration contracts, investors are watching closely to see whether those contracts translate into faster renewals and larger deals down the road. The cautious reaction is notable because Palantir also raised its full-year 2026 revenue guidance to a range of $8.53 billion to $8.534 billion and expects U.S. commercial revenue to grow at least 143%.
It remains to be seen whether the commercial bookings slowdown is merely a temporary consequence of changing contract structures or an early indication that Palantir’s explosive AI-driven growth is beginning to moderate. With expectations for PLTR stock exceptionally high, even a modest deceleration in metrics can trigger significant selling pressure.
About Palantir Stock
Palantir is a software and data analytics company that develops platforms designed to integrate, manage, and secure complex datasets across government and commercial clients. Headquartered in Aventura, Florida, Palantir has grown from its roots in government intelligence into a broader enterprise-tech play. It specializes in big‑data analytics and AI platforms — including Gotham, Foundry, Apollo, and its Artificial Intelligence Platform (AIP) — for both government and enterprise clients. Palantir has a market capitalization of around $372 billion, placing it among the largest software and analytics companies globally.
PLTR stock has come under significant pressure as investors reassess the sustainability of the company’s extraordinary growth. Shares have declined about 8% over the past 52 weeks and are down 10% year-to-date (YTD), while the recent selloff has been much sharper, with the stock slumping 13% over the past five trading sessions. PLTR stock closed at $160.38 on Nov. 6, well below its 52-week high of $212.94.
The latest weakness intensified after Palantir’s Q3 results highlighted a sharp deceleration in U.S. commercial bookings. Although Q3 revenue surged and U.S. commercial revenue jumped, U.S. commercial total contract value came in below expectations. For a stock priced for exceptionally strong growth, the slowdown has raised concerns that the pace of future commercial expansion may not be as explosive as investors had anticipated. Meanwhile, the fact that Palantir’s remaining deal value grew only 4% sequentially has added to those concerns, even as it remained up 79% YOY.
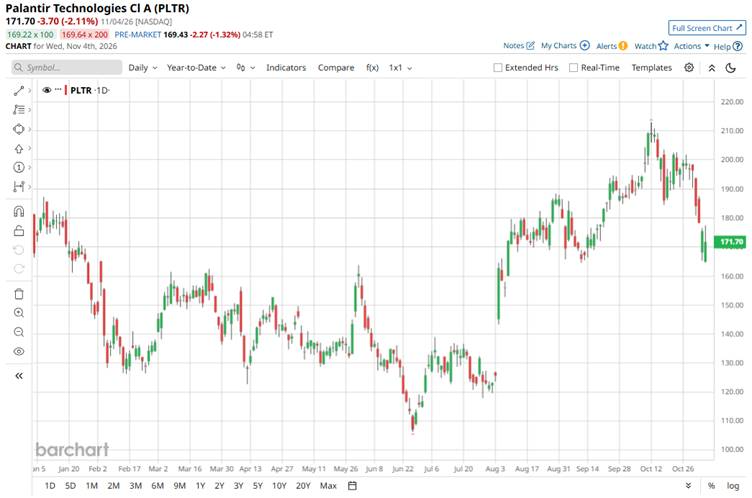
Even after the pullback, Palantir continues to command a premium multiple that leaves little room for disappointment. The stock has increasingly been viewed as a beneficiary of the AI boom, and investors have become more demanding as expectations have risen. PLTR stock currently trades at a substantial premium over peers at 131.4 times forward earnings.
Revenue Soars, But Bookings Growth Slows Sharply
Palantir released its Q3 2026 results on Nov. 2, with revenue jumping 96% YOY to $2.31 billion, marking the first quarter in which Palantir’s quarterly revenue surpassed $2 billion.
The company’s U.S. business remained the primary growth engine. U.S. revenue increased 119% to $1.94 billion. Within that, U.S. commercial revenue surged 148% to $984 million. Importantly, U.S. commercial revenue also exceeded U.S. government revenue for the first time, with the latter rising 96% to $953 million.
Profitability also improved dramatically. Adjusted operating income rose to $1.43 billion, while the adjusted operating margin expanded to 62%. Net income attributable to common stockholders increased to $1.13 billion, while adjusted EPS was $0.44.
Cash generation was similarly strong. Cash flow from operations increased to $1.21 billion, while adjusted free cash flow climbed to $1.22 billion.
However, the most important weakness was in bookings. Palantir closed $2.92 billion of TCV, up just 6% YOY, compared with a 151% YOY increase to $2.76 billion in Q3 2025. U.S. commercial TCV rose only 11% to $1.46 billion, versus a massive 342% increase to $1.31 billion a year earlier. U.S. commercial remaining deal value was $6.52 billion, up 79% YOY but only 4% sequentially.
Despite the bookings slowdown, management raised its full-year 2026 outlook. Palantir now expects Q4 revenue of $2.649 billion to $2.653 billion and adjusted operating income of about $1.64 billion. For full-year 2026, management increased its revenue guidance to $8.53 billion to $8.534 billion. The company also raised its U.S. commercial revenue outlook to more than $3.55 billion, representing at least 143% growth, and increased adjusted operating income guidance to $5.245 billion to $5.249 billion. Adjusted free cash flow is expected at $4.8 billion to $5 billion.
Meanwhile, analysts expect EPS to climb 108% YOY to $1.31 in fiscal 2026, then rise another 43% to $1.88 in fiscal 2027.
What Do Analysts Expect for Palantir Stock?
On Nov. 4, Barclays analyst Anthony Valentini reiterated an “Overweight” rating on Palantir and raised his price target to $273 from $265, signaling that Barclays remains bullish on the AI software company despite the recent selloff following Q3 earnings. Last month, JPMorgan analyst Brian Essex also initiated coverage with an “Overweight” rating and a $262 price target.
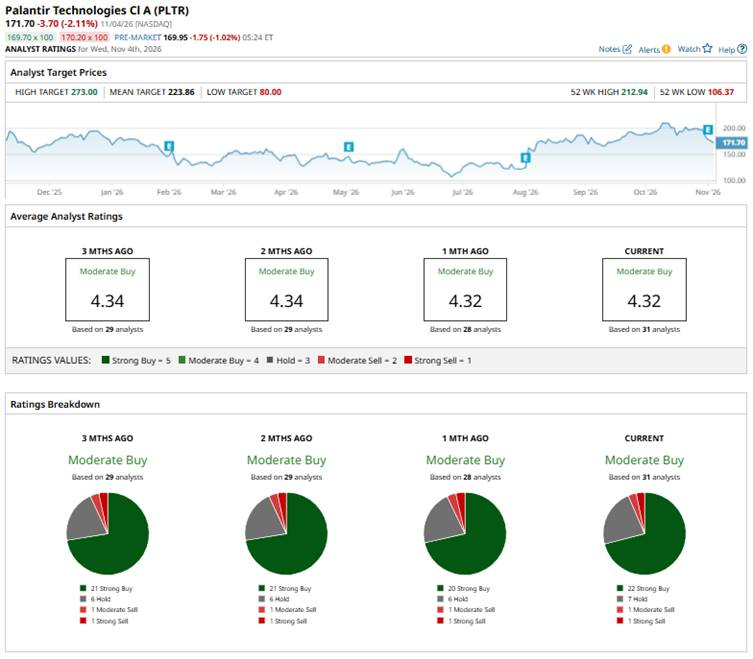
PLTR stock has a consensus “Moderate Buy” rating overall. Of the 31 analysts covering the stock, 22 advise a “Strong Buy,” seven suggest a “Hold” rating, one analyst has a “Moderate Sell” rating, and one has a “Strong Sell" rating. While the average price target of $223.86 indicates potential upside of 39% from here, the Street-high target of $273 signals that Palantir stock could climb as much as 70% from current levels.
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.