


EN
How Investors May Respond To Rightmove Stock (LSE:RMV) EPS Guidance Raised
- Rightmove updated its guidance, raising its 2026 underlying earnings per share growth target to at least 7% while keeping revenue and operating profit outlook unchanged in the face of weaker UK housing activity and softer advertiser demand.
- The business plans to return more than £400m to shareholders between July 2026 and July 2027, even as higher mortgage rates, lower buyer demand and reduced new home construction weigh on transaction volumes and advertiser spending.
- We will now look at how Rightmove's investment narrative could shift, given higher EPS guidance alongside cautious revenue expectations.
Rightmove Investment Narrative Recap
To stay invested in Rightmove, you need to believe that its dominant UK property portal position and product depth can offset a sluggish housing cycle. The upgraded 2026 EPS growth target to at least 7% points to tighter cost control and capital returns supporting per share outcomes, even as transaction volumes and advertiser budgets feel pressure.
The key short term swing factor remains how estate agents and developers respond to tough conditions. If advertiser churn stays contained and upgrades into higher value packages continue, the near term story stays intact. The biggest risk is that prolonged weakness in New Homes and cautious agents start to cap ARPA progress.
The most relevant announcement here is the plan to return more than £400m to shareholders between July 2026 and July 2027. Set against modest revenue guidance of 6% to 7% growth in 2026 and expectations that 2027 revenue growth will be similar to 2026, this signals confidence in cash generation capacity.
For you, that capital return sits alongside the raised EPS growth outlook and creates a clear execution test. Rightmove now needs to keep ARPA moving, hold on to agent and developer customers despite affordability pressures, and prevent higher people and contractor spend from eroding margins while delivering on those buyback and dividend ambitions.
Rightmove Consensus Expectations In Numbers
Analysts currently frame the Rightmove story around steady, mid single digit growth. The consensus view points to revenue rising at about 6.9% a year over the next three years, with earnings expected to reach £236.5 million by 2029 from £218.4 million today. That implies an earnings increase of roughly £18.1 million by the 2029 forecast year, even as profit margins are expected to ease from 49.7% to 44.1%.
Based on those projections, the stock would be trading on a P/E of 21.7x 2029 earnings, compared with 17.8x today and above the 18.7x multiple cited for the wider GB Interactive Media and Services industry. Consensus also includes a small expected decline in the share count of about 0.78% per year, which would quietly support earnings per share even if headline profit growth remains moderate.
Rightmove's narrative projects £536.8 million of revenue and £236.5 million of earnings by 2029. This is based on 6.9% yearly revenue growth and an earnings increase of about £18.1 million from £218.4 million today.
Uncover why Rightmove's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
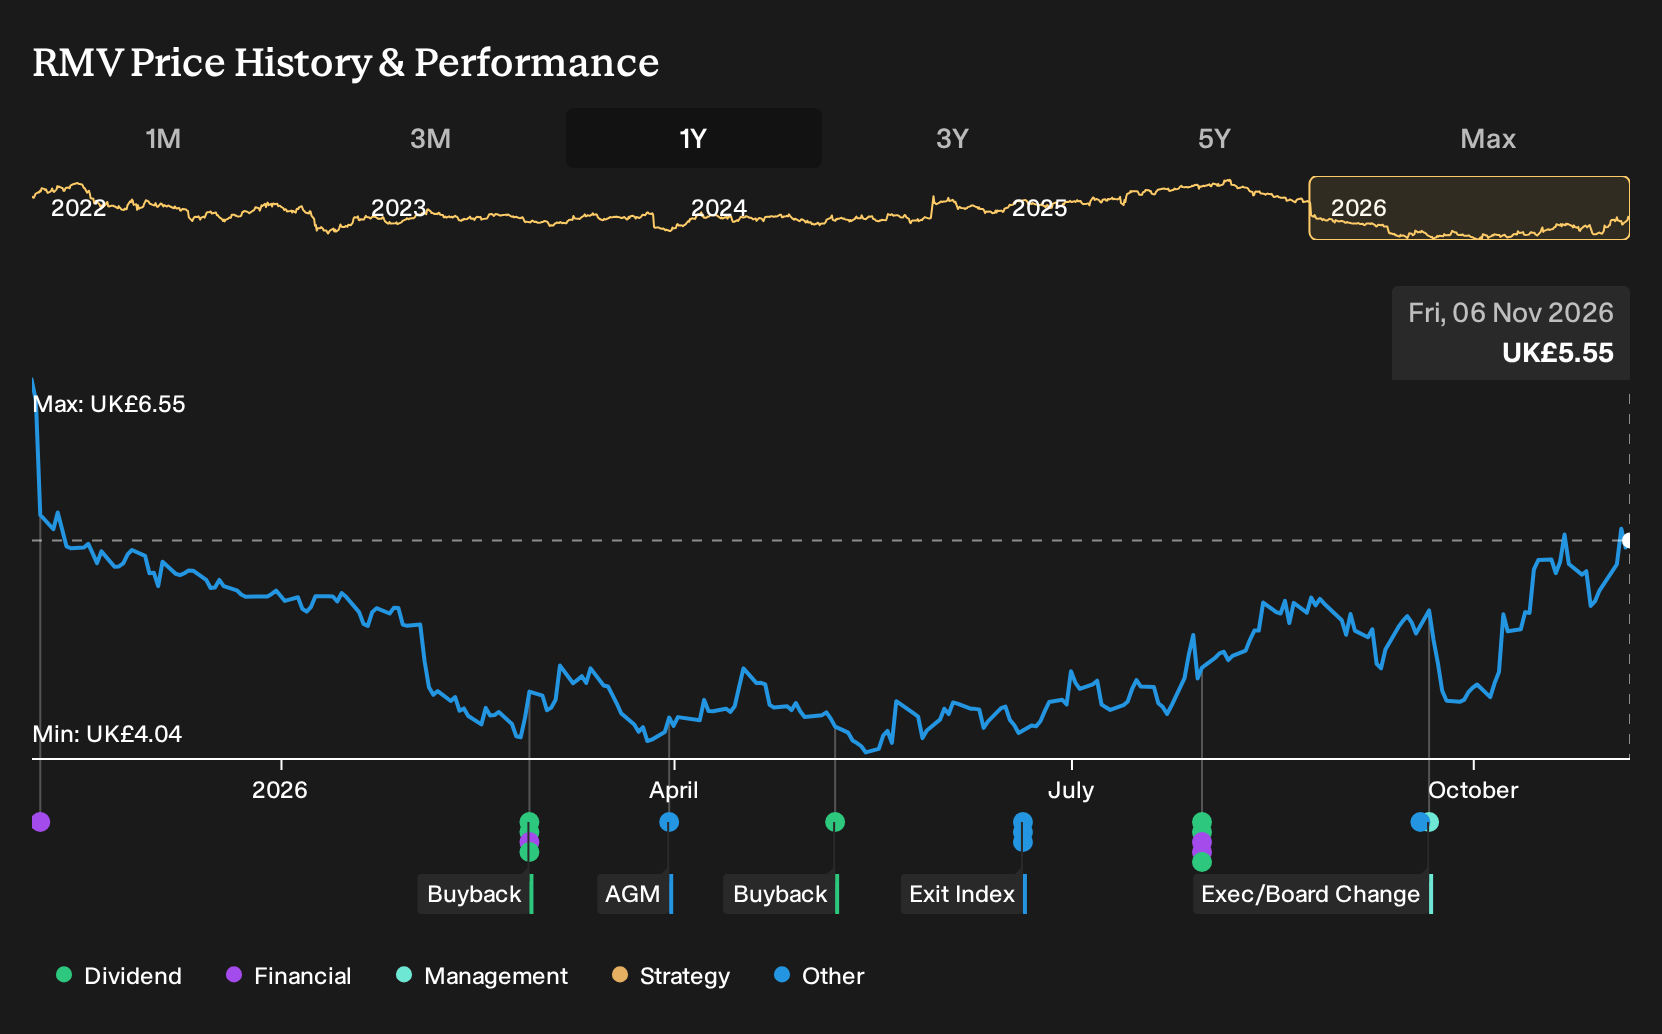
Exploring Other Perspectives
One contrasting angle focuses on rising costs rather than ARPA resilience. The lowest Rightmove analysts already pencilled in earnings of about £229.5 million on roughly £535.4 million of revenue by 2029, with margins easing to 42.9%. That is a much tougher story than consensus, and this fresh guidance could push those views to shift again.
Explore 4 other Rightmove fair value estimates, including one that suggests as much as 36% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Rightmove research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rightmove. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rightmove's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rightmove?
If Rightmove's refreshed guidance has sharpened your focus on quality and resilience, it can help to widen the lens and scan other companies with strong fundamentals. The Simply Wall St Screener gives you a structured way to quickly filter for different styles, whether you lean toward defensiveness, potential mispricing, or income.
- If you want resilience to be front and center, start with companies that screen as sturdier and less volatile through our 4 resilient stocks with low risk scores.
- If your priority is finding opportunities where quality and pricing may not fully align, use the screener that highlights 15 high quality undervalued stocks to see which businesses currently look mispriced on fundamentals.
- If your watchlist leans more toward income ideas, focus on companies offering higher yields and stronger payout profiles by reviewing our curated set of 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com