


EN
Wabtec (WAB) Stock Looks Reasonably Priced On Cash Flow
Westinghouse Air Brake Technologies has delivered a strong multi year share price story, which naturally raises a question for anyone looking at the stock today. With the focus now on its cash generation, the issue is whether the current valuation lines up with the cash flows the business is expected to produce.
- Over the past 5 years the share price has gained about 195.0%, so a lot of future cash flow is now being priced into Wabtec.
- The roughly US$390 million services agreement with Transnet Engineering may support more predictable cash inflows and influence how investors think about the timing and durability of the company's cash flows.
- Prefer to judge Westinghouse Air Brake Technologies on earnings? See what Westinghouse Air Brake Technologies's 34.2x P/E says about the price.
The stock's next move may depend on whether the current price is supported by the intrinsic value suggested by its cash flows under a Discounted Cash Flow (DCF) view.
If you want to test the same cash flow question you are asking of Westinghouse Air Brake Technologies across a wider field, compare it with 42 high quality undervalued stocks.
Is Westinghouse Air Brake Technologies Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here uses a 2 Stage Free Cash Flow to Equity approach that focuses on what cash is left for shareholders after expenses, reinvestment, and debt. For Westinghouse Air Brake Technologies, the latest twelve month free cash flow sits around $1.82b, with analyst and internal projections pointing to free cash flows that grow in a steady, rather than explosive, pattern over the coming decade.
This profile lines up with a mature industrial business where a lot of the value comes from consistency rather than big step changes. The roughly US$390 million long term services agreement with Transnet Engineering fits that story because it adds visibility to future cash generation that the DCF is already trying to capture. On that basis, the model suggests Westinghouse Air Brake Technologies' expected cash flows are broadly in line with the current $278.48 share price, so the market is already pricing in a fair amount of this growth path. Find out what Westinghouse Air Brake Technologies could be worth using our Discounted Cash Flow (DCF) estimate.
The Westinghouse Air Brake Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Westinghouse Air Brake Technologies valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the share price to sit meaningfully above or below where it is today on the Community page. Each narrative ties its number to a clear view on how Westinghouse Air Brake Technologies' future growth, profitability and risks could shift, which gives you a reference point to revisit as fresh information comes through.
One of the top community narratives on Westinghouse Air Brake Technologies: 16% undervalued
"Rapid growth in Digital Intelligence offerings, with sales up around 76% in Q1 2026 and around 89% in Q2 2026 helped by Inspection Technologies and Frauscher…"
Discover why this Narrative puts Westinghouse Air Brake Technologies at 16% undervalued.
One more Westinghouse Air Brake Technologies signal to check before you move on
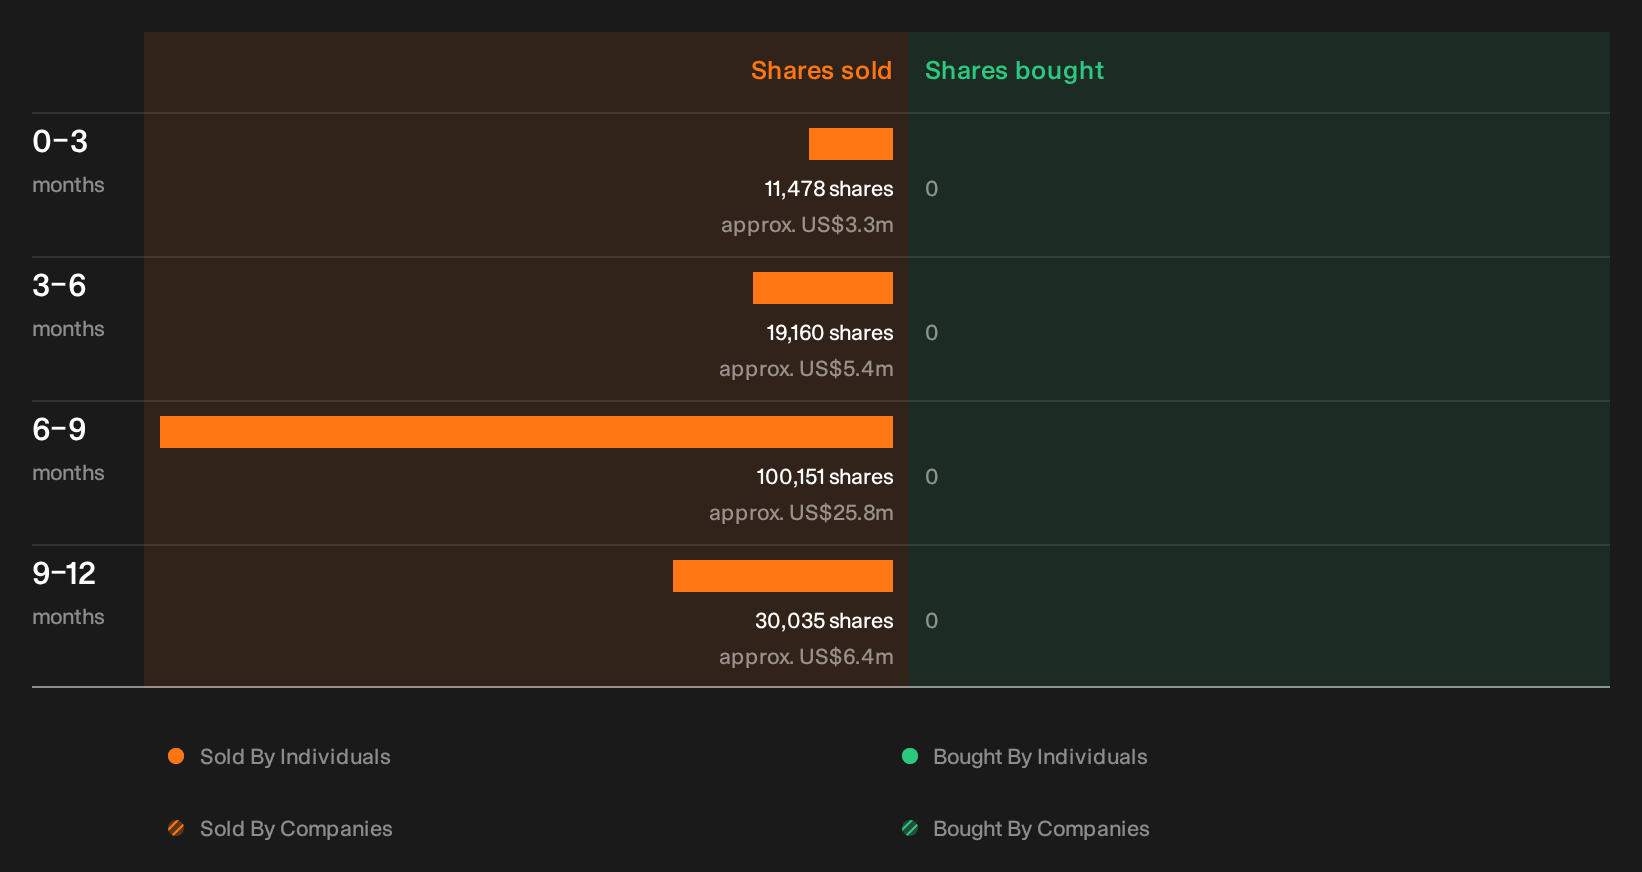
Before you lean too heavily on the cash flow story for Westinghouse Air Brake Technologies, it is worth looking at the recent insider share sales our checks have surfaced, who sold, how much, and what it might suggest. See the recent insider selling flagged for Westinghouse Air Brake Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com