


EN
Wallenius Wilhelmsen (OB:WAWI) Could Be 3% Undervalued After Q3 Earnings
Wallenius Wilhelmsen (OB:WAWI) has just reported new figures. Third quarter 2026 sales were US$1,401 million, net income was US$192 million and earnings per share were US$0.45.
The latest figures landed after a busy spell for Wallenius Wilhelmsen. In late October the company announced two three year shipping and logistics contracts valued at more than US$1b and expanded its dual fuel vessel renewal program. Despite the 1 day share price return declining 1.23% to NOK160.1 and the 7 day share price return falling 5.27%, momentum over longer horizons has been strong, with a 90 day share price return of 8.47%, a year to date share price return of 59.30% and a 1 year total shareholder return of 109.12% pointing to investors rewarding the longer term story more than the latest quarter.
Scan how Wallenius Wilhelmsen compares with other transport focused plays by reviewing our curated list of list of solid balance sheet and fundamentals (192 results)
Wallenius Wilhelmsen now mixes softer earnings with hefty contracts and a powerful 1 year share run. Does that recent strength still leave enough upside for new buyers once the valuation is stripped back?
Most Popular Narrative: 3% Undervalued
On the most widely followed view, Wallenius Wilhelmsen’s fair value sits at NOK165.48, only slightly above the NOK160.10 last close. This frames today’s price as only modestly below that estimate.
The main factor that has to go right is that Wallenius Wilhelmsen sustains high utilization and pricing in a tight RoRo market and lifts logistics cash EBITDA margins toward the 10% goal by the end of 2027, despite fuel cost and bunker surcharge timing risks.
See why 51 investors see Wallenius Wilhelmsen as 3% undervalued.
Result: Fair Value of NOK165.48 (UNDERVALUED)
Still, the story for Wallenius Wilhelmsen can change quickly if fuel costs stay volatile or if the enlarged global car carrier fleet pulls freight rates lower.
Find out about the key risks to this Wallenius Wilhelmsen narrative.
Another Take On Wallenius Wilhelmsen’s Valuation
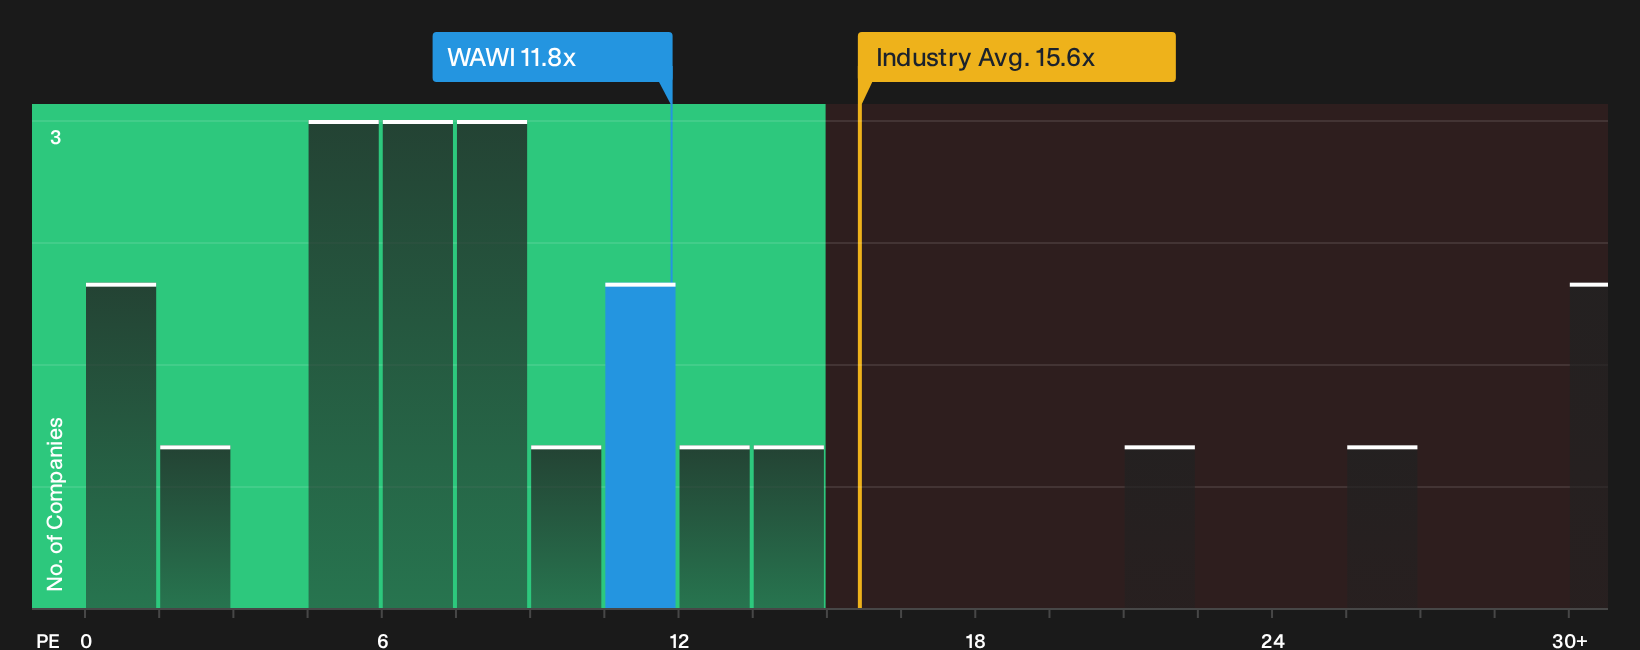
That fair value of NOK165.48 comes from analyst forecasts. If you look at the simple P/E instead, Wallenius Wilhelmsen screens differently. The stock trades at 11.8x earnings, which is higher than peer companies on 7.2x, yet slightly below its own fair ratio estimate of 11.9x. That mix suggests less of a clear bargain and more of a judgment call on future earnings strength. Which signal do you trust more when expectations cool or reset?
See what the numbers say about this price in our valuation breakdown, then compare it with your own expectations for the business, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Wallenius Wilhelmsen so far, with both worries and bright spots in the latest data, mean you are better off stress testing the numbers yourself and weighing the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Wallenius Wilhelmsen?
If Wallenius Wilhelmsen helped sharpen your thinking, do not stop there. Put that momentum to work by lining up a few fresh ideas today.
- Target steadier potential returns by reviewing a curated set of 214 resilient stocks with low risk scores that aim to keep downside swings in check.
- Hunt for mispriced quality and compare Wallenius Wilhelmsen with a broader pool of 227 high quality undervalued stocks that may warrant a deeper look.
- Spot tomorrow's potential compounders early by scanning a focused group of 591 high quality undiscovered gems before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com