


EN
Companies Like Softfront Holdings (TSE:2321) Can Afford To Invest In Growth
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
Given this risk, we thought we'd take a look at whether Softfront Holdings (TSE:2321) shareholders should be worried about its cash burn. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
Does Softfront Holdings Have A Long Cash Runway?
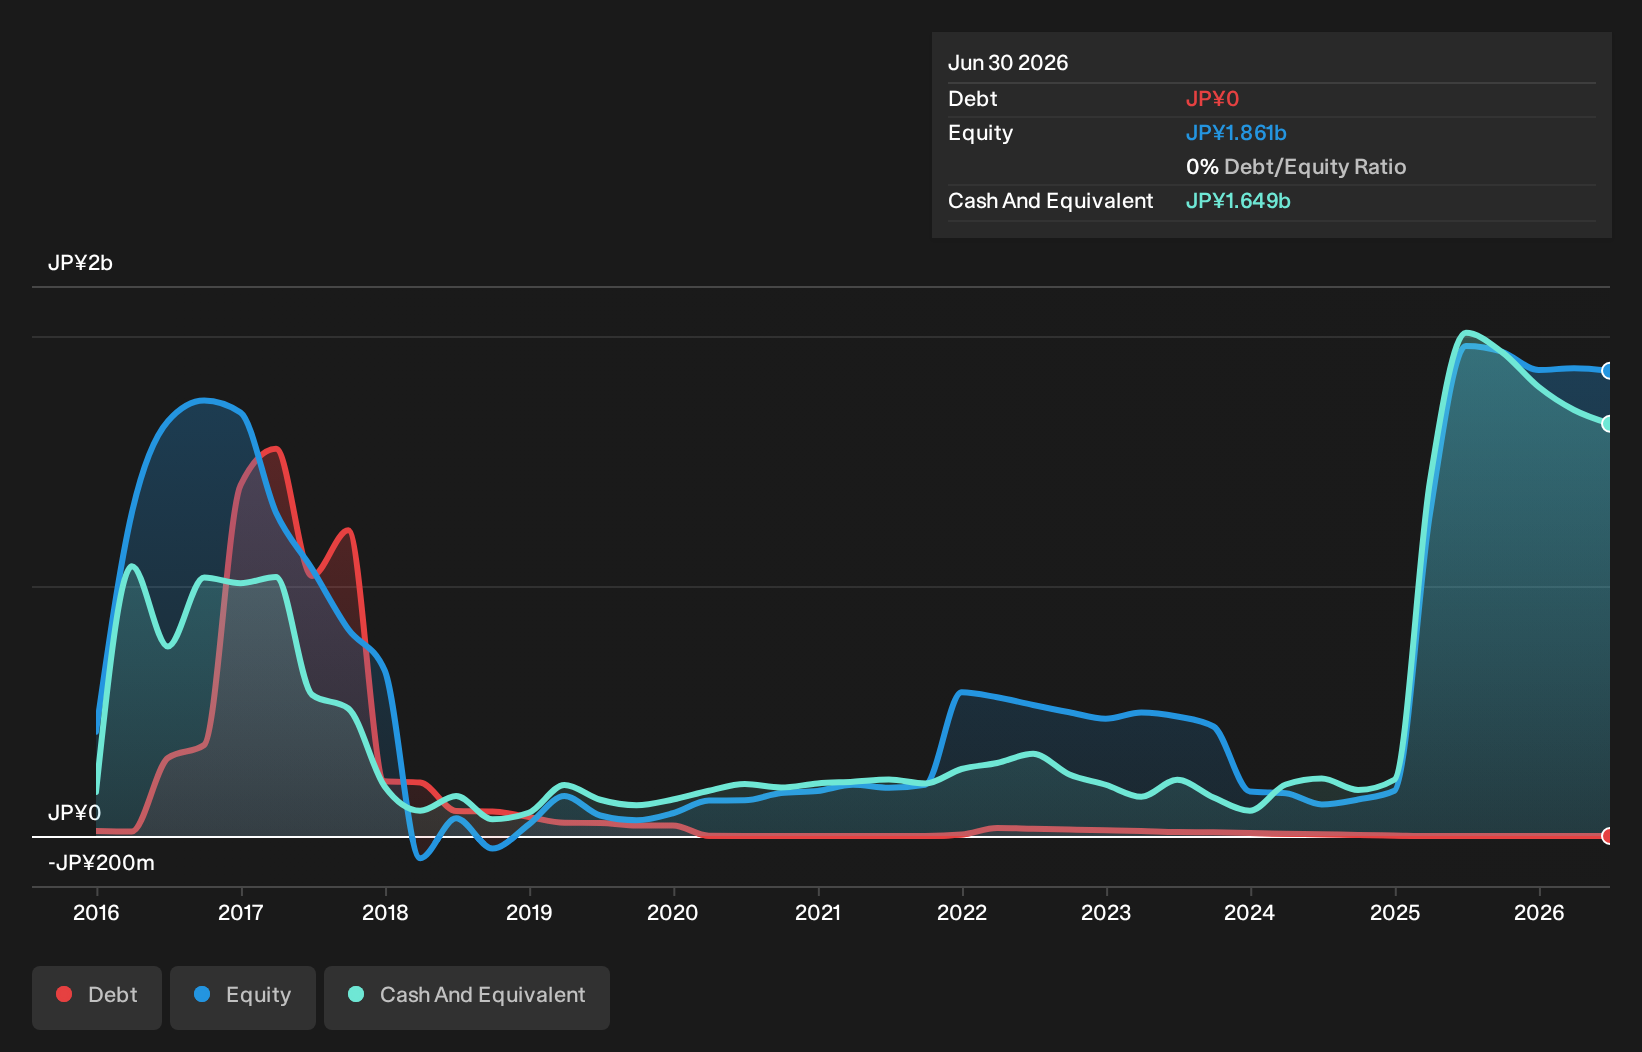
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, Softfront Holdings had JP¥1.6b in cash, and was debt-free. Importantly, its cash burn was JP¥283m over the trailing twelve months. Therefore, from June 2026 it had 5.8 years of cash runway. Even though this is but one measure of the company's cash burn, the thought of such a long cash runway warms our bellies in a comforting way. You can see how its cash balance has changed over time in the image below.
See our latest analysis for Softfront Holdings
Is Softfront Holdings' Revenue Growing?
Given that Softfront Holdings actually had positive free cash flow last year, before burning cash this year, we'll focus on its operating revenue to get a measure of the business trajectory. Although it's hardly brilliant growth, it's good to see the company grew revenue by 15% in the last year. In reality, this article only makes a short study of the company's growth data. You can take a look at how Softfront Holdings has developed its business over time by checking this visualization of its revenue and earnings history.
How Hard Would It Be For Softfront Holdings To Raise More Cash For Growth?
While Softfront Holdings is showing solid revenue growth, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Many companies end up issuing new shares to fund future growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Softfront Holdings' cash burn of JP¥283m is about 4.6% of its JP¥6.2b market capitalisation. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
Is Softfront Holdings' Cash Burn A Worry?
As you can probably tell by now, we're not too worried about Softfront Holdings' cash burn. For example, we think its cash runway suggests that the company is on a good path. Its revenue growth wasn't quite as good, but was still rather encouraging! Taking all the factors in this report into account, we're not at all worried about its cash burn, as the business appears well capitalized to spend as needs be. On another note, Softfront Holdings has 3 warning signs (and 2 which are concerning) we think you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.