


EN
Learn Why The Bull Case For National Vision Holdings (EYE) Could Change Following Flagship Store Opening
- National Vision Holdings recently opened a flagship America's Best store adjacent to Avalon in Alpharetta, Georgia, combining clinical care, eyewear, technology, education and personalized service into one connected experience.
- The concept turns the America's Best format into a testbed for a more integrated digital and in-store eyecare journey that could inform how National Vision Holdings configures future locations and allocates capital.
- This development provides new context for understanding how National Vision Holdings' investment narrative is influenced by a customer-centric flagship format and an omnichannel focus.
Scan how National Vision Holdings’ flagship move fits into a wider retail-health theme by sizing it up against hand-picked peers in the list of solid balance sheet and fundamentals (24 results).
National Vision Holdings Investment Narrative Recap
To own National Vision Holdings, you need to believe the retailer can keep attracting value focused shoppers while making eyecare more convenient for insured customers. The flagship store tests whether a more connected exam to eyewear journey can support this effort. The key near term swing factor remains execution on omnichannel tools and patient volume, rather than a single location.
The biggest operational risk still comes from online only eyewear players and any strain on optometrist availability that could limit exam capacity. The Alpharetta flagship does not remove those issues. It may offer useful learnings on doctor productivity, assortment mix and managed care conversion, but the financial impact near term looks modest.
With no other fresh announcements listed alongside the flagship opening, the most relevant reference point remains the earlier focus on omnichannel marketing and CRM investments. Those tools aim to make it easier to reach higher income and mid funnel customers, then keep them engaged across digital and stores. The new America's Best format is a real world test of that playbook.
For you as a shareholder, the link to catalysts is practical. If National Vision Holdings can use this site to refine remote exam usage, premium frame mix and insured patient throughput, that can inform store optimization and future openings. The risk is straightforward. If e commerce rivals or managed care dynamics pressure traffic, a concept store on its own does not fix the wider brick and mortar exposure.
Analysts currently frame National Vision Holdings' trajectory around revenues of US$2.4b and earnings of US$108.1m by 2029. This ties back to an assumed 5.1% yearly revenue growth rate and an earnings increase of about US$57.8m from US$50.3m today.
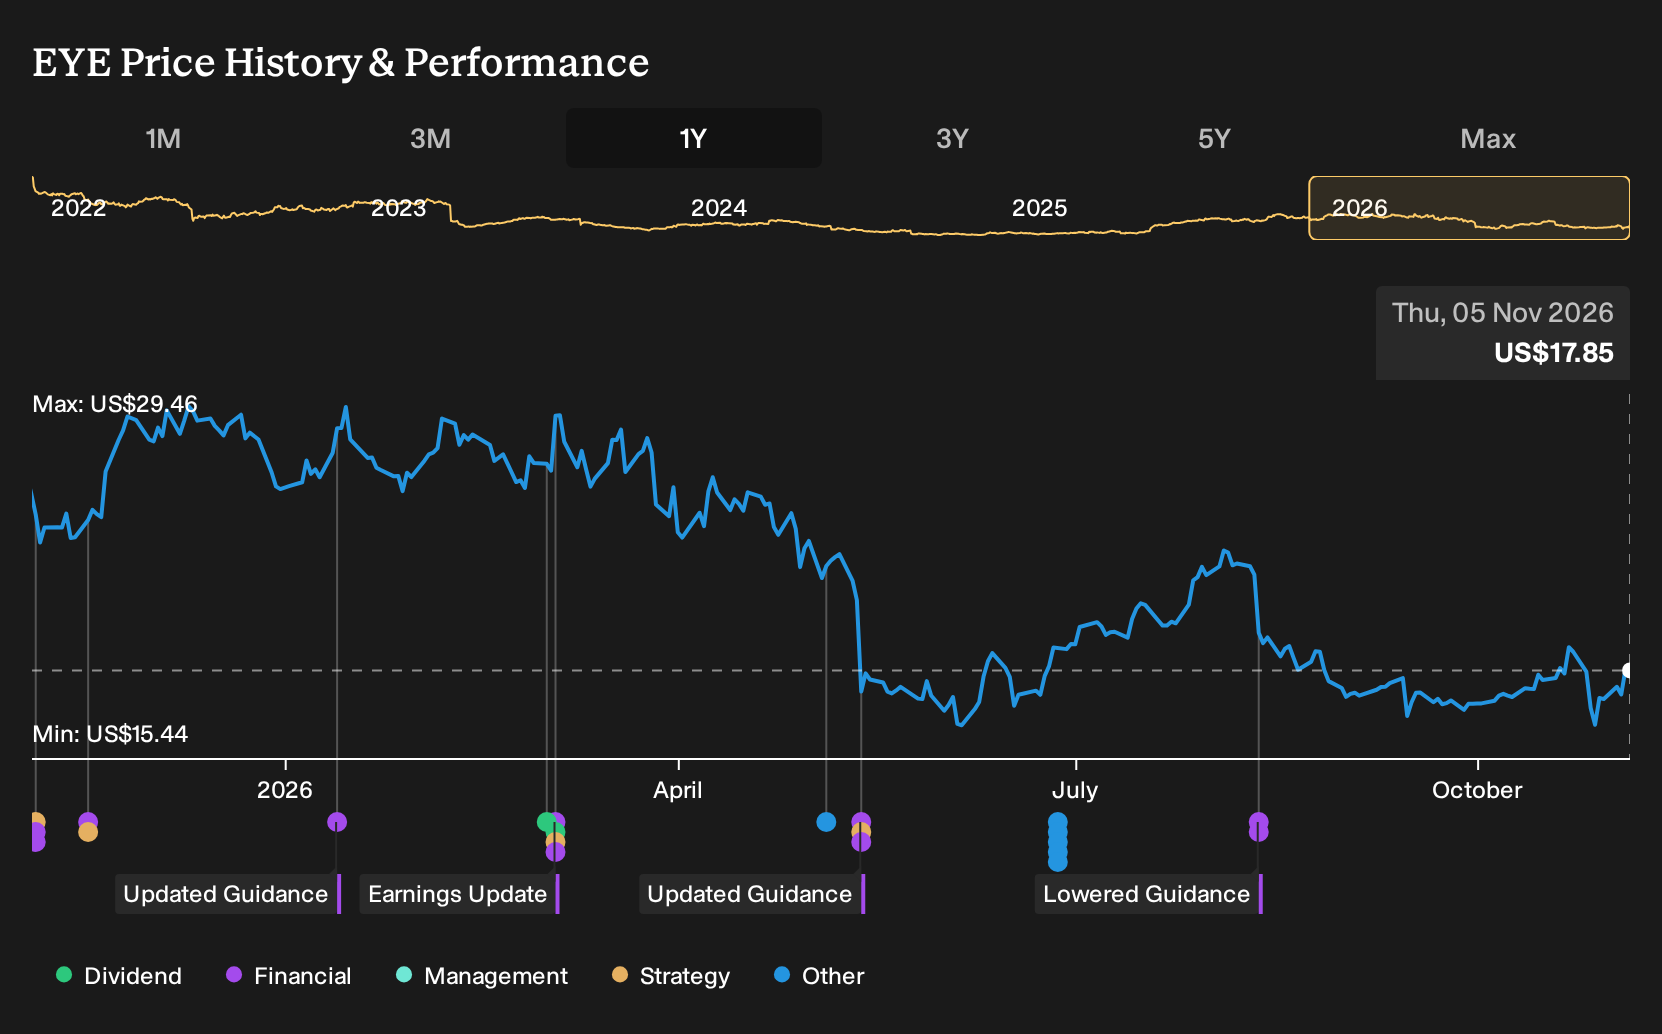
Uncover how National Vision Holdings' fair value indicates a 54% potential upside to its current price that could narrow quickly as expectations reset.
Exploring Other Perspectives
One bullish twist on National Vision Holdings centers on premium products rather than e-commerce risk. The most optimistic analysts were assuming revenue of about US$2.4b and earnings of roughly US$109.7m by 2029, before this flagship store news. If the new format accelerates that premium mix story, those forecasts and opinions could shift meaningfully.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your National Vision Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for National Vision Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Vision Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond National Vision Holdings?
If the National Vision Holdings story has sharpened your thinking, use that momentum to scan a wider field of opportunities with the Simply Wall St Screener. You can filter for the traits that matter most to you, whether that is resilience, income, or unloved quality.
- For a focus on resilience and balance sheet strength, start with a curated 32 resilient stocks with low risk scores to help you narrow down sturdier candidates.
- If you want potential mispricing plus quality fundamentals, check out a targeted 42 high quality undervalued stocks that brings together strong cash flows and cleaner finances.
- For investors who like spotting earlier stage opportunities backed by robust numbers, scan a 21 high quality undiscovered gems that might not yet be crowded with attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com