


EN
Did Record Results Just Shift Wheaton Precious Metals Stock Investment Narrative?
- Wheaton Precious Metals reported third quarter 2026 sales of US$771.73 million and net income of US$410.25 million, alongside an 18% increase in its fourth quarter cash dividend to US$0.195 per share, and reaffirmed production guidance backed by progress on projects such as Koné, Copper World and Jervois.
- The streaming group’s record year to date performance, larger contribution from assets like Antamina and Peñasquito, and decision to lift the dividend highlight a focus on converting higher metal prices and rising delivery volumes into cash returns while funding an expanded pipeline of long life, low cost streams.
- This analysis considers how Wheaton Precious Metals' investment narrative is affected by record cash generation and an 18% dividend increase.
Wheaton Precious Metals Investment Narrative Recap
For Wheaton Precious Metals, the key belief is that its streaming portfolio converts metal prices and delivery growth into durable cash flow without the capital intensity of owning mines. The latest quarter supports that idea, with US$771.73 million in sales and US$410.25 million in net income. The near term swing factor remains consistent delivery from key partners and the broader pricing backdrop for gold and silver.
The biggest risk still sits with deal quality and competition for new streams, especially after recent multi billion dollar commitments. Record nine month earnings of US$1.54 billion help absorb that, but do not remove exposure to weaker counterpart performance or less favorable terms on future agreements.
The 18% increase in the fourth quarter dividend to US$0.195 per share is the announcement that ties this earnings report together most clearly. It links Wheaton Precious Metals’ record year to date results, including US$2.60 billion in sales and higher earnings per share, directly to cash being returned to shareholders.
For catalysts, that higher payout, together with the Dividend Reinvestment Plan, keeps attention on the business’ ability to sustain strong operating cash generation while continuing to fund projects such as Koné, Copper World and Jervois. The main execution question is whether the current portfolio can maintain this balance if commodity prices or counterpart delivery schedules soften.
Wheaton Precious Metals' analyst narrative indicates forecast revenue of US$4.1b and earnings of US$2.3b by 2029, based on assumptions of 8.6% yearly revenue growth and an earnings increase of about US$200m from current earnings of US$2.1b.
Uncover why Wheaton Precious Metals' fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view of Wheaton Precious Metals focuses on tax pressure rather than production risk. The most cautious analysts were already assuming around US$4.2b of 2029 revenue and US$2.3b of earnings before this record quarter and dividend lift. That is a much more restrained story. Use it as a reminder to compare several narratives before you decide what this new information could mean.
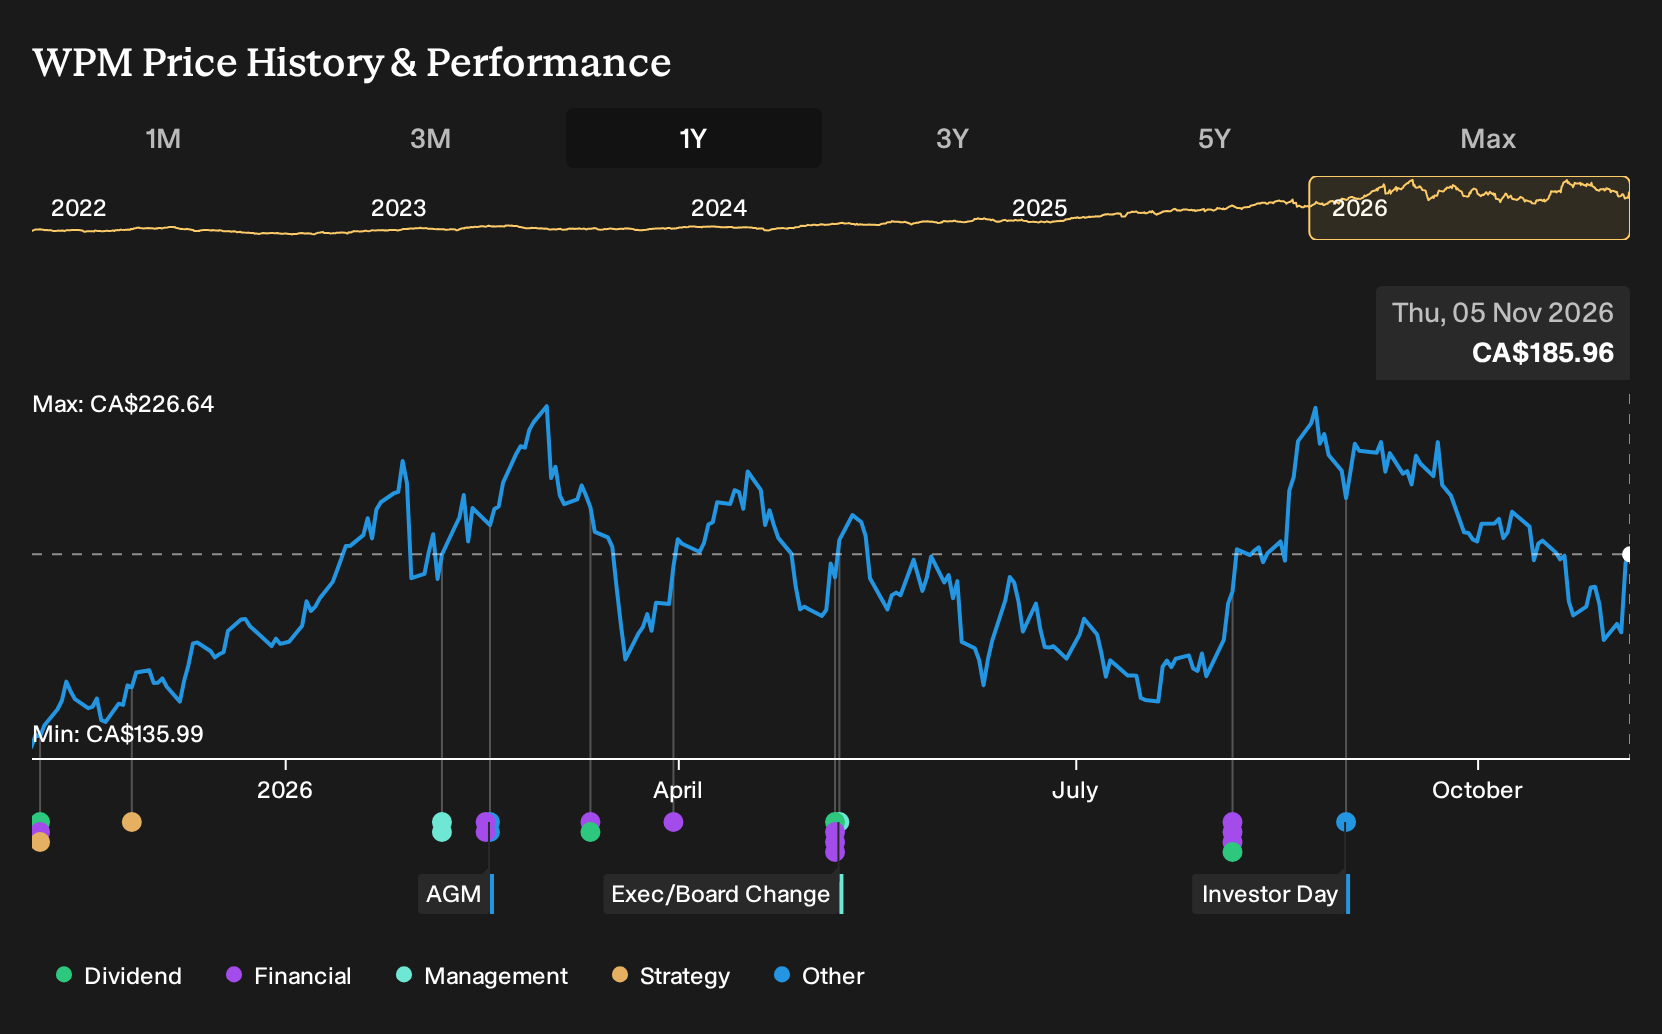
Explore 5 other Wheaton Precious Metals fair value estimates, including one that suggests it could be worth just CA$185.70.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Wheaton Precious Metals research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wheaton Precious Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wheaton Precious Metals' overall financial health at a glance.
Looking for more investment ideas beyond Wheaton Precious Metals?
If Wheaton Precious Metals has sharpened your interest in metals and income streams, use this as a springboard to widen your opportunity set with the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, review a curated set of potentially attractively priced businesses through the 6 high quality undervalued stocks.
- If portfolio resilience matters most to you, scan companies that pair sturdier balance sheets with solid fundamentals using the list of solid balance sheet and fundamentals (5 results).
- For those hunting for under followed potential, consider a selection of lesser known stocks with strong underlying metrics via the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com