


EN
Raised Outlook Could Be A Game Changer For Toast Stock (TOST)
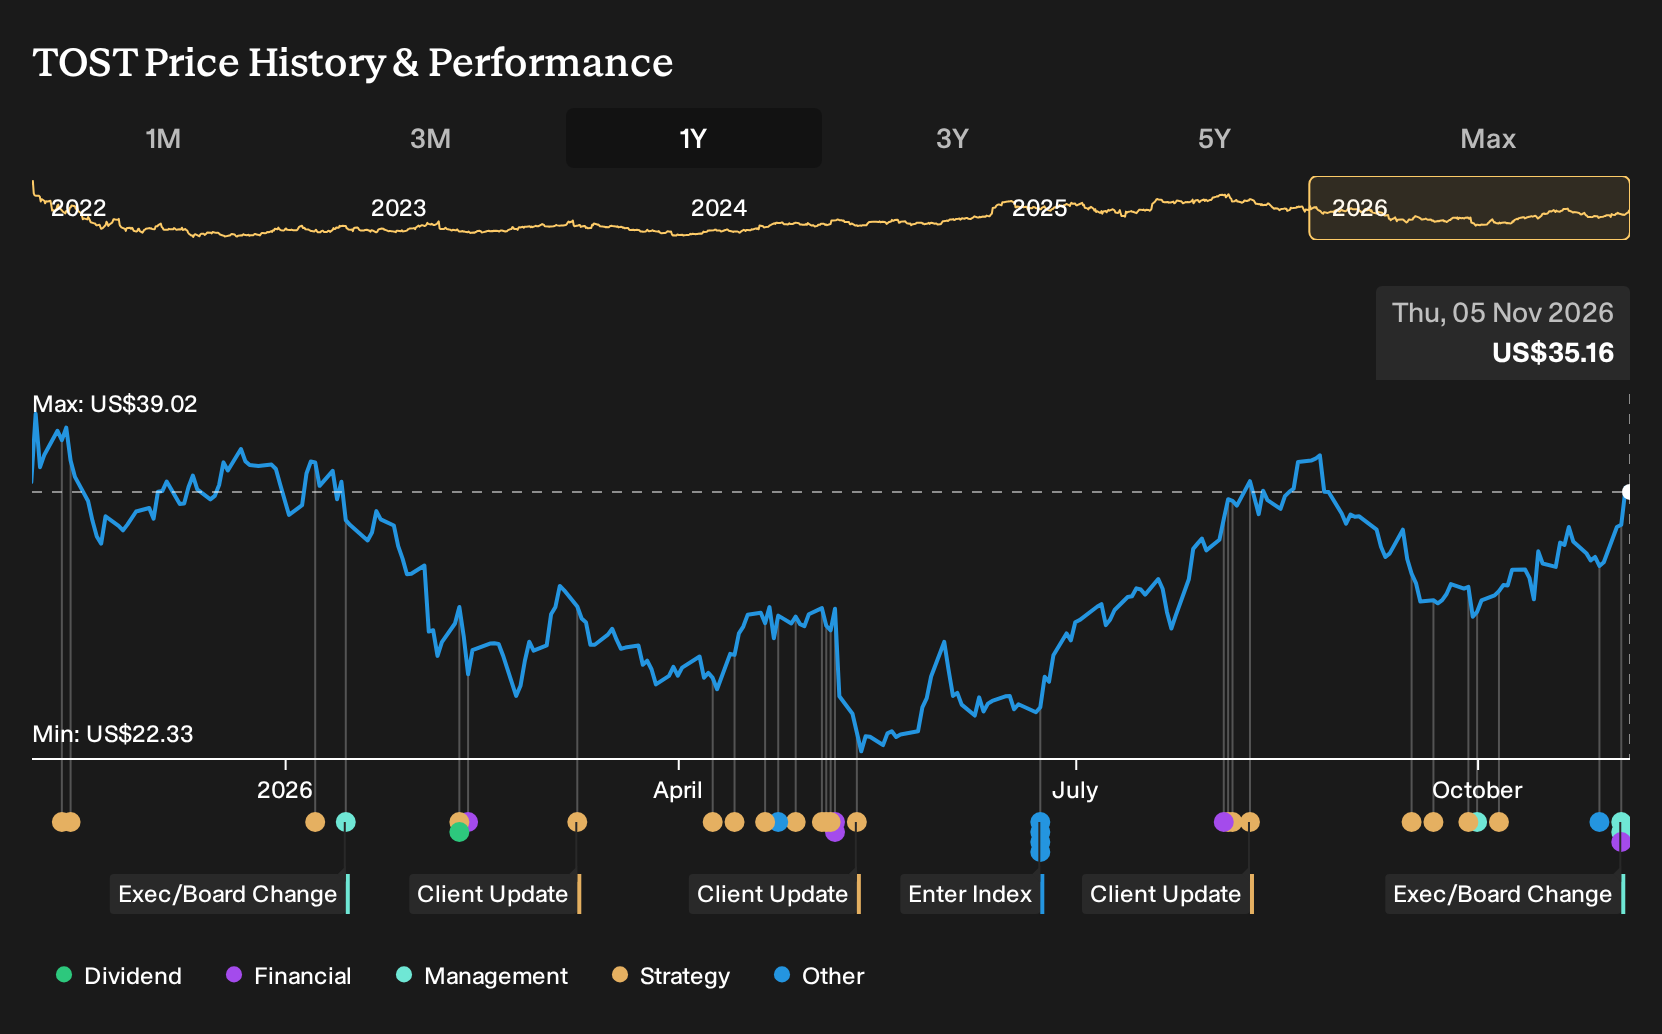
- Toast reported third quarter 2026 results with revenue of US$1.981b and net income of US$169m, raised its full year adjusted EBITDA outlook, added about 8,500 net new locations to reach roughly 189,000, and signed a systemwide enterprise technology agreement with Ruby Tuesday.
- Alongside higher recurring gross profit and SaaS ARR, Toast is leaning into AI products such as Toast IQ Grow and Toast IQ Team. This signals a heavier tilt toward software and data driven services that can matter for how investors think about the durability of its restaurant platform.
- We will now look at how Toast's raised full year outlook and AI focus could influence the longer term investment narrative.
Scan how Toast's AI driven restaurant tools compare with other potential breakout platforms by checking a curated set of 53 AI infrastructure stocks built to power the next wave of digital operations.
Toast Investment Narrative Recap
To own Toast, you need to believe it can keep turning its restaurant footprint and data into durable software, payments and lending earnings while keeping spending on sales, hardware and AI in check. The most important short term catalyst remains execution on its AI suite and monetization of its 189,000 locations. The latest Q3 beat and higher adjusted EBITDA outlook directly support that near term story.
The biggest near term risk is rising cost and complexity as Toast pushes deeper into enterprise, international and AI tools while hardware and legal exposure stay in the mix. The Federal Trade Commission lawsuit on contract practices is meaningful. Management says it is prepared to litigate, which could add expense and distraction if the process drags.
The Ruby Tuesday enterprise win is the announcement that most clearly ties to the current Toast narrative. A full systemwide rollout of Toast Go 3 handhelds, Flex 3 terminals, kitchen display systems and integrated payments shows how Toast is trying to deepen wallet share in chains, not just sign single store deployments. That is exactly where investors often look for proof that AI and software add ons can ride on top of a larger platform footprint.
Operationally, Ruby Tuesday gives another test case for Toast’s hardware economics and service model at scale, as well as a live environment for its AI tools and data layer. The more Toast can show smooth execution and stable unit economics in these chain rollouts, the more credible its longer term catalysts in enterprise and international segments look, even alongside ongoing hardware and legal risks.
Toast's current analyst storyline points to revenues of US$11.2b and earnings of US$1.2b by 2029, built on a projected 18.0% yearly revenue growth rate and an earnings step up of about US$714m from US$486.0m today to the 2029 consensus figure.
Uncover why Toast's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts framed Toast around one catalyst that contrasts with the consensus story. They focused on AI driven agentic services that could shift Toast toward higher value workflows like marketing and payroll. Before this Ruby Tuesday deal and the latest Q3 print, that group was already penciling in US$12.3b of revenue and US$1.3b of earnings by 2029. Those projections sit above the base case and show how far views can stretch. Treat this news as a chance to compare those older forecasts with your own expectations and explore how opinions might change.
Explore 6 other Toast fair value estimates, including one that suggests potential upside of as much as 32% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Toast research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Toast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toast's overall financial health at a glance.
Looking for more investment ideas beyond Toast?
If Toast has sharpened your thinking on what makes a compelling business case, you can use that same checklist across the wider market. A focused screener can help you filter for the mix of financial strength, income potential, or value profile that best matches your approach.
- If capital preservation and steadier profiles matter to you, start with a basket of 32 resilient stocks with low risk scores that score well on resilience and risk metrics.
- If balance sheet strength is your first filter, narrow the field to a list of solid balance sheet and fundamentals (24 results) so you can concentrate on companies with cleaner finances before focusing on anything else.
- If you prefer under followed ideas with room for the story to develop, scan through a curated set of 21 high quality undiscovered gems that pair quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com