


EN
What National Australia Bank Shares Weak Profit Means For Shareholders
- National Australia Bank reported full year 2026 results with net interest income of A$18,494 million and net income of A$6,143 million, alongside lower earnings per share and higher credit impairment and restructuring related costs.
- The bank paired weaker profit and increased loan loss provisions with an affirmed final dividend of A$0.85 per share, highlighting a tension between supporting shareholders and absorbing higher credit risk and expense pressures.
- This article examines how National Australia Bank's investment narrative is affected by weaker profit driven by higher credit impairment charges.
National Australia Bank Investment Narrative Recap
To stay invested in National Australia Bank, you need to be comfortable with a simple trade off. Management is leaning into a higher credit risk backdrop while still running a sizeable franchise built on business lending, deposits and a heavy spend on technology platforms. The latest result shows net income at A$6,143 million with weaker earnings per share and higher credit impairment, which keeps asset quality and cost control firmly in focus.
The key short term catalyst is whether credit losses and expenses settle into something more predictable so the existing digital and business banking projects can show through in profit. The biggest risk right now is that rising impairments and restructuring outlay keep net margins under pressure for longer, which could limit flexibility on growth and capital deployment.
The dividend affirmation at A$0.85 per share for the final period is the announcement that matters most here. It sits alongside higher credit provisions and restructuring charges, so it gives you a live test of how confident National Australia Bank is in its capital position while earnings are under pressure. For income focused holders, that combination will probably be front of mind.
This payout also interacts directly with the bank’s existing risks. If asset quality in business lending or consumer portfolios weakens further, or if expenses stay elevated as systems and workforce changes are rolled out, management may have less room to keep distributing capital at the same pace. That makes future updates on provisions, costs and restructuring progress critical catalysts to watch against the current dividend settings.
Analyst Scenario For National Australia Bank
Consensus expectations sketch a very specific path for National Australia Bank. Analysts are working off forecast revenue growth of 5.0% a year over the next three years and current earnings of about A$6.1b, with a view that profit margins could shift from 29.3% today to 33.4% by 2029 if execution lines up with the current plan around technology, deposits and business lending focus.
On those assumptions, the analyst group expects National Australia Bank's earnings to reach about A$8.1b by 2029, which is an increase of roughly A$2.0b from earnings today. That change implies a step up of around one third in profit over the period, so the projected improvement in margins does a lot of the heavy lifting in the story rather than only relying on volume or balance sheet expansion.
National Australia Bank's narrative projects revenues of about A$24.2b and earnings of about A$8.1b by 2029. This assumes 5.0% yearly revenue growth and an earnings increase of roughly A$2.0b from current earnings of about A$6.1b.
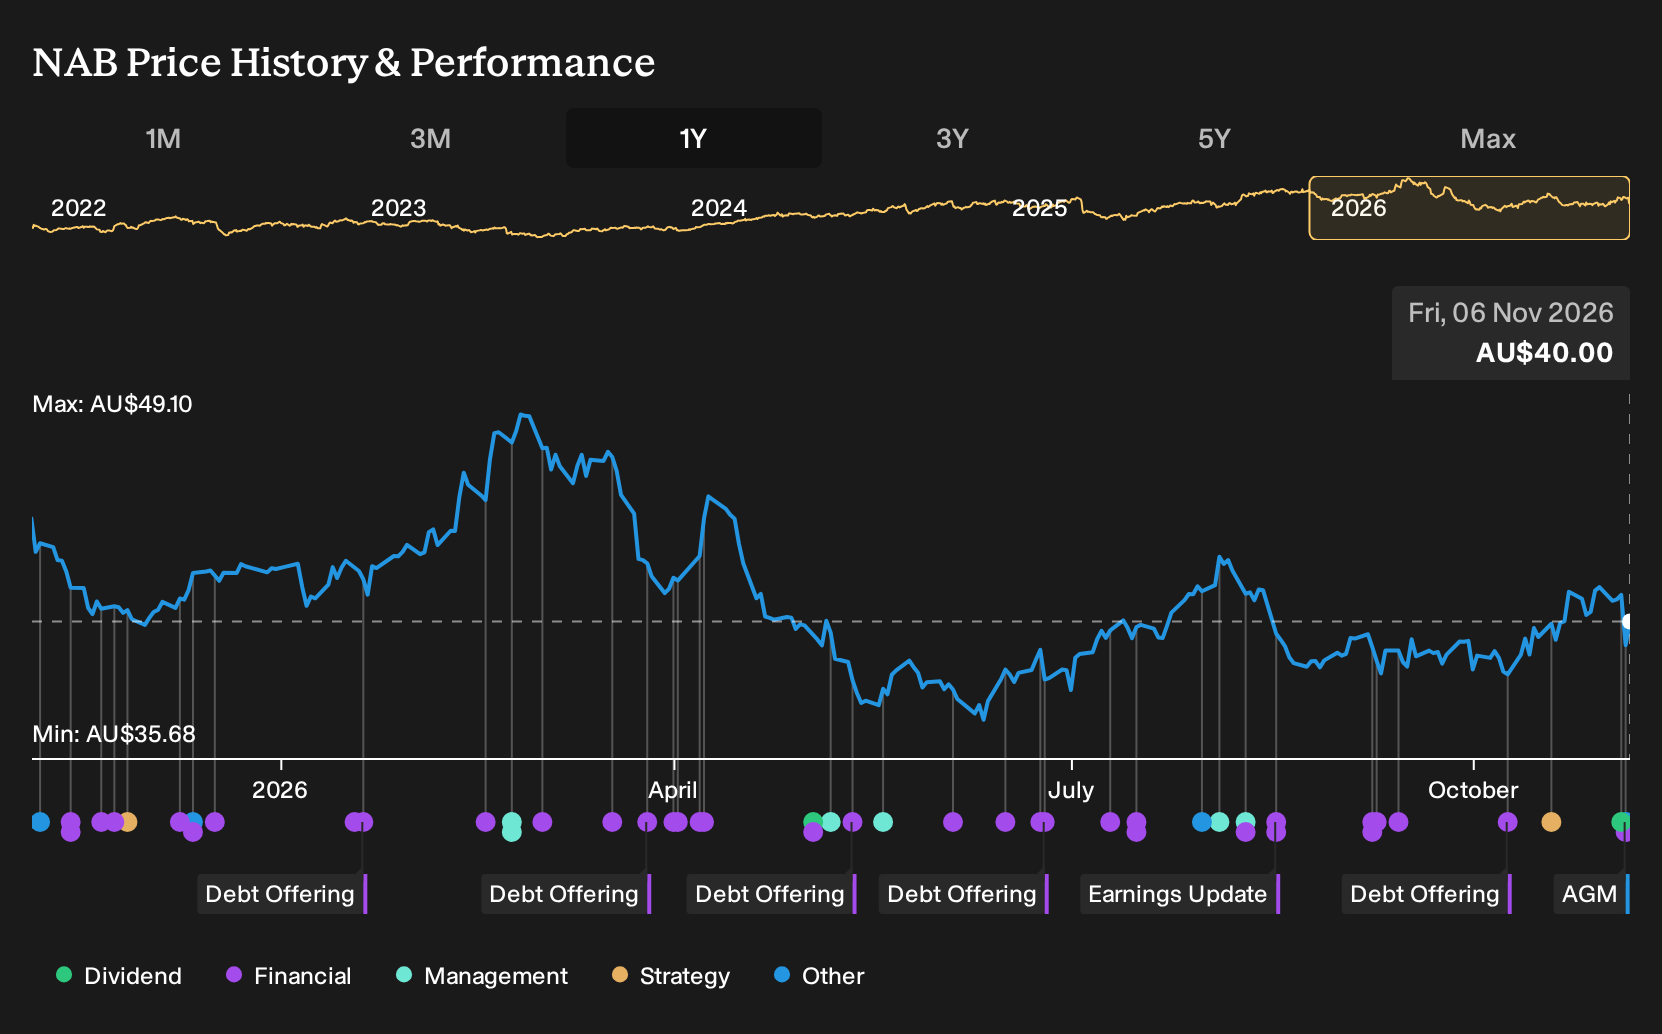
The valuation discussion then links these operating targets to what investors are currently willing to pay. The market price is A$39.25, while the analyst consensus target sits at A$38.46, only 2.1% lower. That narrow gap signals that, on average, analysts see the stock as broadly aligned with their implied fair value today, with the forward P/E on the 2029 earnings sitting at 18.5x compared with an estimated 19.8x on current earnings and 13.7x for the wider Australian banks sector.
Price targets around that A$38.46 average still span a wide band, from A$29.00 at the cautious end to A$48.50 at the more optimistic end. For you as a holder or potential investor, the useful exercise is to stress test the moving parts behind those numbers. That means asking whether a shift to A$24.2b of revenue, A$8.1b of earnings and a lower P/E multiple of 18.5x in 2029 feels reasonable given your view on credit risk, cost inflation and the pace of digital execution at National Australia Bank.
Uncover why National Australia Bank's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
You can see how differently people read the same facts. The most cautious analysts worry that National Australia Bank’s higher technology and restructuring costs crowd out earnings, even before this profit drop and A$6,143 million net income update. They were already pencilling in about A$23.9b of 2029 revenue and A$8.0b of earnings. That more pessimistic A$29.00 price view could shift again once this latest credit impairment spike and dividend affirmation are fully worked through, so it is worth comparing several narratives rather than relying on a single story.
Explore 4 other National Australia Bank fair value estimates, including one that suggests it could be worth just A$38.46.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your National Australia Bank research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Australia Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Australia Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond National Australia Bank?
If National Australia Bank is already on your radar, it can help to compare its risk, income profile and balance sheet strength with other listed businesses. The Simply Wall St Screener lets you quickly filter the market so you can line up alternatives that fit your own risk appetite and return goals.
- For investors who care most about resilient balance sheets and sturdier fundamentals, start with this list of solid balance sheet and fundamentals (12 results) that meet tighter financial quality filters.
- If you want ideas that the market may be overlooking, use the curated 14 high quality undiscovered gems as a source of fresh watchlist candidates.
- Income focused readers who want to compare National Australia Bank’s yield to other payout focused stocks can review this 5 dividend fortresses built around higher distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com