


EN
What Costain Group Doubters Got Wrong Before A 77% Rally
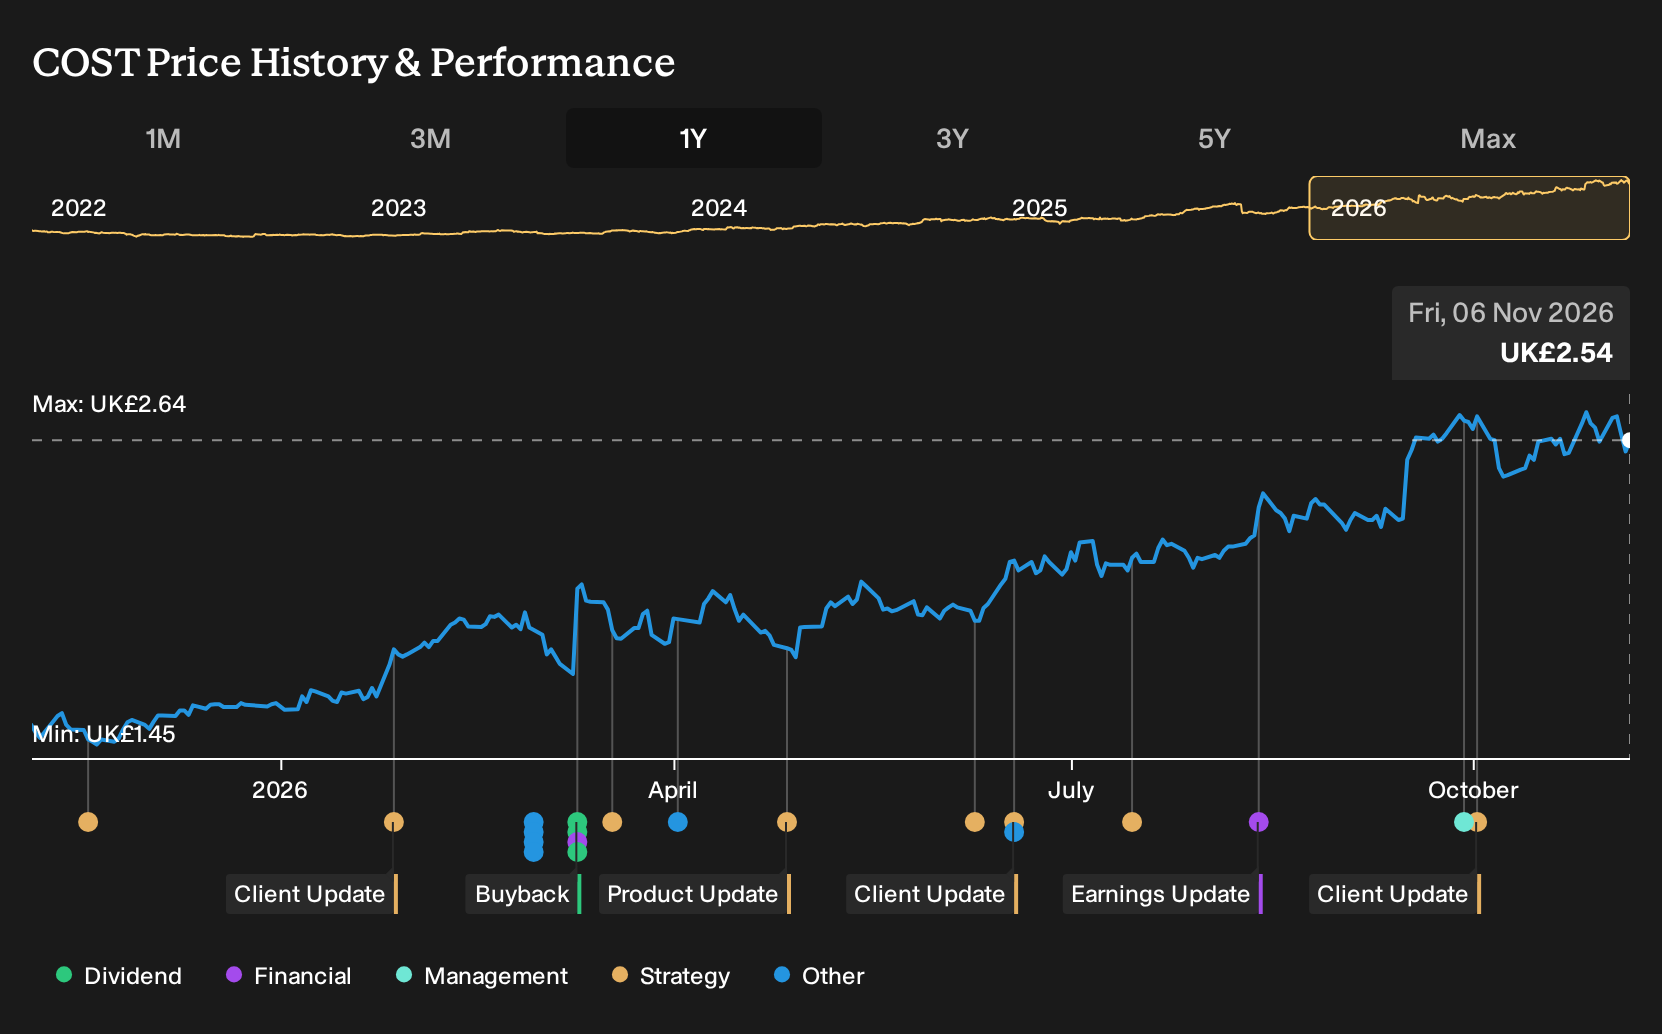
Costain Group entered the period with investors arguing over whether government backed low carbon work and digital consulting would reshape its earnings power, or whether rising UK regulatory and labour costs would squeeze fixed contracts. Investors who held Costain Group over the past year are up 76.5%, including dividends. If you were weighing a fresh position back in November 2025, what exactly did you need to believe about those contracts and margins?
Costain Group has already moved. See which of 15 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On Costain Group
The shares cost £1.49 at the start of the period, and Costain Group sat between two very different stories about what came next.
On the upbeat side, the optimistic narrative pointed to a fair value of £1.82, a price implied by expectations rather than a hard fact, built on revenue rising 8.1% a year and profit margins reaching 3.3% as higher margin consultancy and digital work took a bigger role.
The cautious narrative anchored on a fair value of £1.15 and assumed revenue growth of 3.3%, with a key concern that fixed price work and rising UK regulatory and labour costs could justify only an 8.1x future P/E.
What The Results Changed For Costain Group
The key fresh fact for Costain Group was the H1 2026 report. Revenue was £543.1m against £525.4m in H1 2025 and net income was £14.9m against £14.2m, with net margin reported at 2.7% in both periods. That combination supported the optimistic story on top line progress yet left the higher margin ambition unproven, so the evidence cut both ways.
The lesson is simple. When a thesis hangs on richer margins rather than just higher sales, keep checking reported net margin against the original forecast before upgrading the story.
What Costain Group's One Year Rally Now Asks You To Believe
Costain Group trades at £2.54 after a 76.5% gain over the past year. The selected Narrative sees its Fair Value below that level and argues that much of the record £7b forward work and stronger balance sheet is already reflected in the price.
The question for a fresh buyer is what has to keep going right. The specific hurdle is whether Costain Group can turn that large pipeline into delivery at or above the guided 4% operating margin without contract or cost surprises eroding profitability.
"The main thing that has to go right is that Costain Group turns its record £7b forward work and growing positions in water, energy, nuclear and aviation into delivery at or above the guided 4% operating margin while keeping contract risk tightly controlled."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 15% below our estimate - builds a dispersed legal platform that attracts senior lawyers leaving partnerships.
- Company 2 - 31% below our estimate - channels savings demand into fee based access to renewable energy and infrastructure.
- Company 3 - 28% below our estimate - runs a single tech platform processing investment inflows for advisers and individuals.
Those are three of them. See all 9 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com