


EN
Ingredion (INGR) Stock Looks Undervalued While Earnings Pressure Clouds The View
Ingredion shares closed at US$97.42, and after a mixed stretch for both the price and the business, many investors are asking whether that tag still lines up with what the company is earning today.
- Over the past 5 years the stock has delivered a total return of 13.0%, which puts real weight on the question of whether current earnings can support where the price has ended up.
- Recent profit pressure from higher manufacturing and input costs, along with progress on integrating a major acquisition, can shape expectations for how much of Ingredion's revenue eventually turns into earnings for shareholders.
- The analysts covering Ingredion have run their own numbers. See what analysts think Ingredion's shares could be worth.
The issue now is whether the current share price is justified by Ingredion's earnings profile when you line it up against the Fair Ratio benchmark.
If you want to stress test this same earnings question beyond Ingredion, compare it with other companies from our 42 high quality undervalued stocks list.
Does Ingredion Look Undervalued on Earnings?
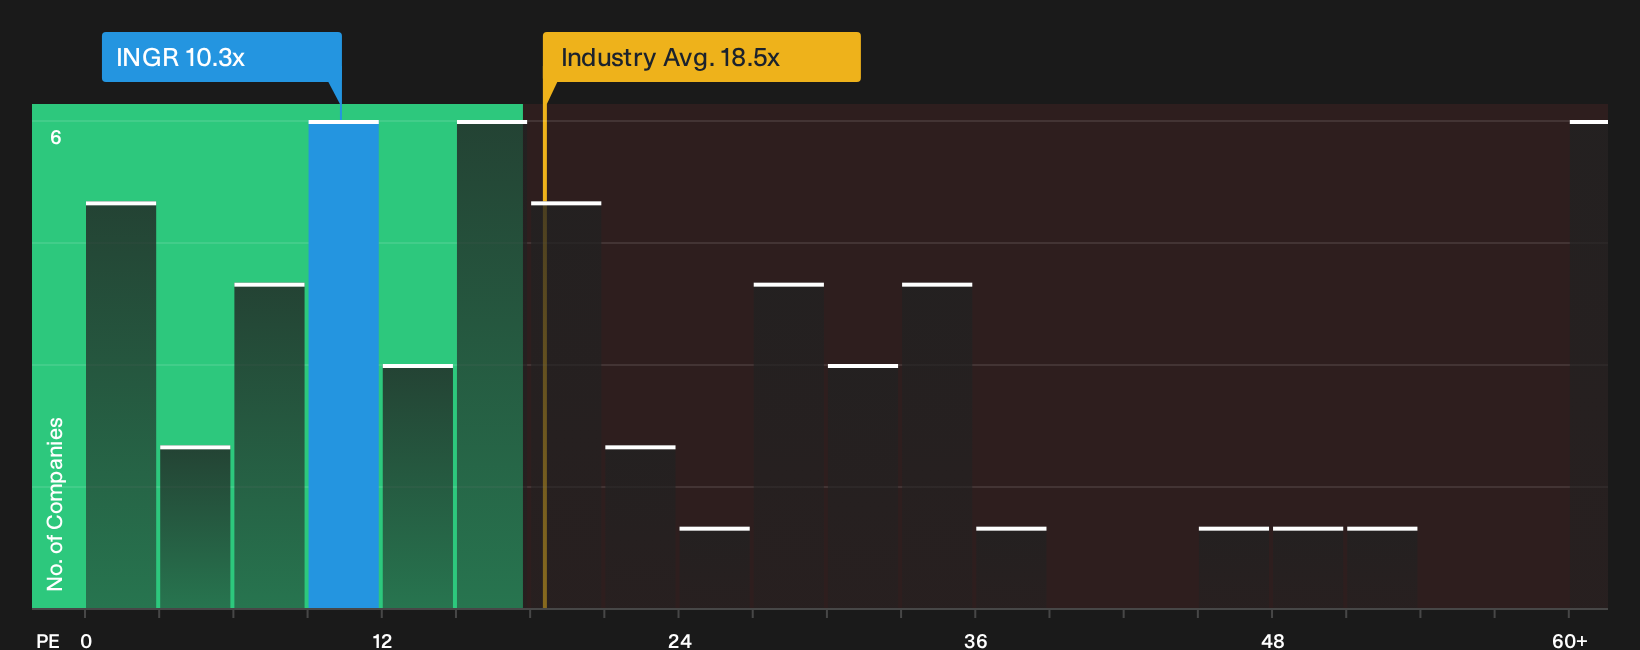
The P/E ratio suits Ingredion because earnings remain a key anchor for how investors assess the business. At roughly 10.3x earnings, the stock trades at a lower multiple than both the Food industry average of about 18.5x and the peer group near 13.8x. That gap tells you the market currently attaches a lower price tag to each dollar of Ingredion earnings than to many similar businesses.
Because the Fair Ratio model blends factors like growth prospects, profitability profile, sector norms and company size, it points to a higher P/E than where Ingredion trades today. This signals the shares screen as undervalued on this metric. The recent cut to full year 2026 EPS guidance, after higher manufacturing and input costs, helps explain why the stock may still trade at a discount, yet the multiple remains below both the industry and this tailored benchmark. Explore the numbers behind Ingredion's P/E valuation.
The Ingredion Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Ingredion leaves off by explaining which growth, margin and earnings paths would need to occur for the stock to be worth materially more or less than today’s price. Each narrative links its number to a clear view on how Ingredion's expansion, profitability and key risks might evolve, giving you something concrete to revisit as fresh information comes through the Community page.
The community is split on Ingredion, with one camp seeing meaningful upside from the specialty shift while the other argues expectations already look full.
Bull case: 20% undervalued
"Continued mix shift toward Texture & Healthful Solutions, which has delivered nine consecutive quarters of net sales volume growth and an 18.7% operating margin…"
Discover why this Narrative puts Ingredion at 20% undervalued.
Bear case: 10% overvalued
"If management successfully integrates Tate & Lyle, delivers the expected synergies, and maintains its strong ROIC and free cash flow generation, the company could deserve a meaningfully higher valuation over the next 3 to 5 years…"
Explore why this Narrative puts Ingredion at 10% overvalued.
One more lens on Ingredion that sits beyond today’s P/E check
Price and current earnings only tell part of the story, because professional models already map out where Ingredion could be a few years from now and offer a clear comparison to today’s setup. Explore where analysts expect Ingredion to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com