


EN
Do Senior Hires Change The Bull Case For Houlihan Lokey Stock (HLI)?
- Houlihan Lokey recently added three senior Managing Directors across Capital Solutions, Business Services, and Power, Utilities & Renewables, expanding sector coverage in New York and London while reinforcing equity and M&A advisory capabilities.
- The hires bring more than 30 years of combined investment banking experience across power, infrastructure, and professional services, which speaks directly to Houlihan Lokey’s push to deepen fee rich advisory lines while it continues to seek acquisitions worldwide.
- We will look at how Houlihan Lokey’s investment narrative is shaped by these senior hires and expanding global advisory reach.
Compare Houlihan Lokey's advisory-focused model with other fee-rich financial specialists by scanning our hand picked list of 21 high quality undiscovered gems that could be flying under most investors' radar.
Houlihan Lokey Investment Narrative Recap
To stay comfortable as a shareholder in Houlihan Lokey, you need to believe the advisory engine converts its record pipelines into closed, higher fee deals at a pace that keeps up with rising costs. The trio of senior hires in Capital Solutions, Business Services, and Power, Utilities & Renewables supports that conviction by deepening sector coverage where complex transactions are more common.
The near term swing factor is whether muted sponsor activity and softer non US deal growth ease enough for larger transactions to complete. The biggest risk is that volume remains skewed to smaller mandates while compensation and non compensation expenses, including technology investment, keep climbing, which would pressure margins and leave recent earnings progress vulnerable.
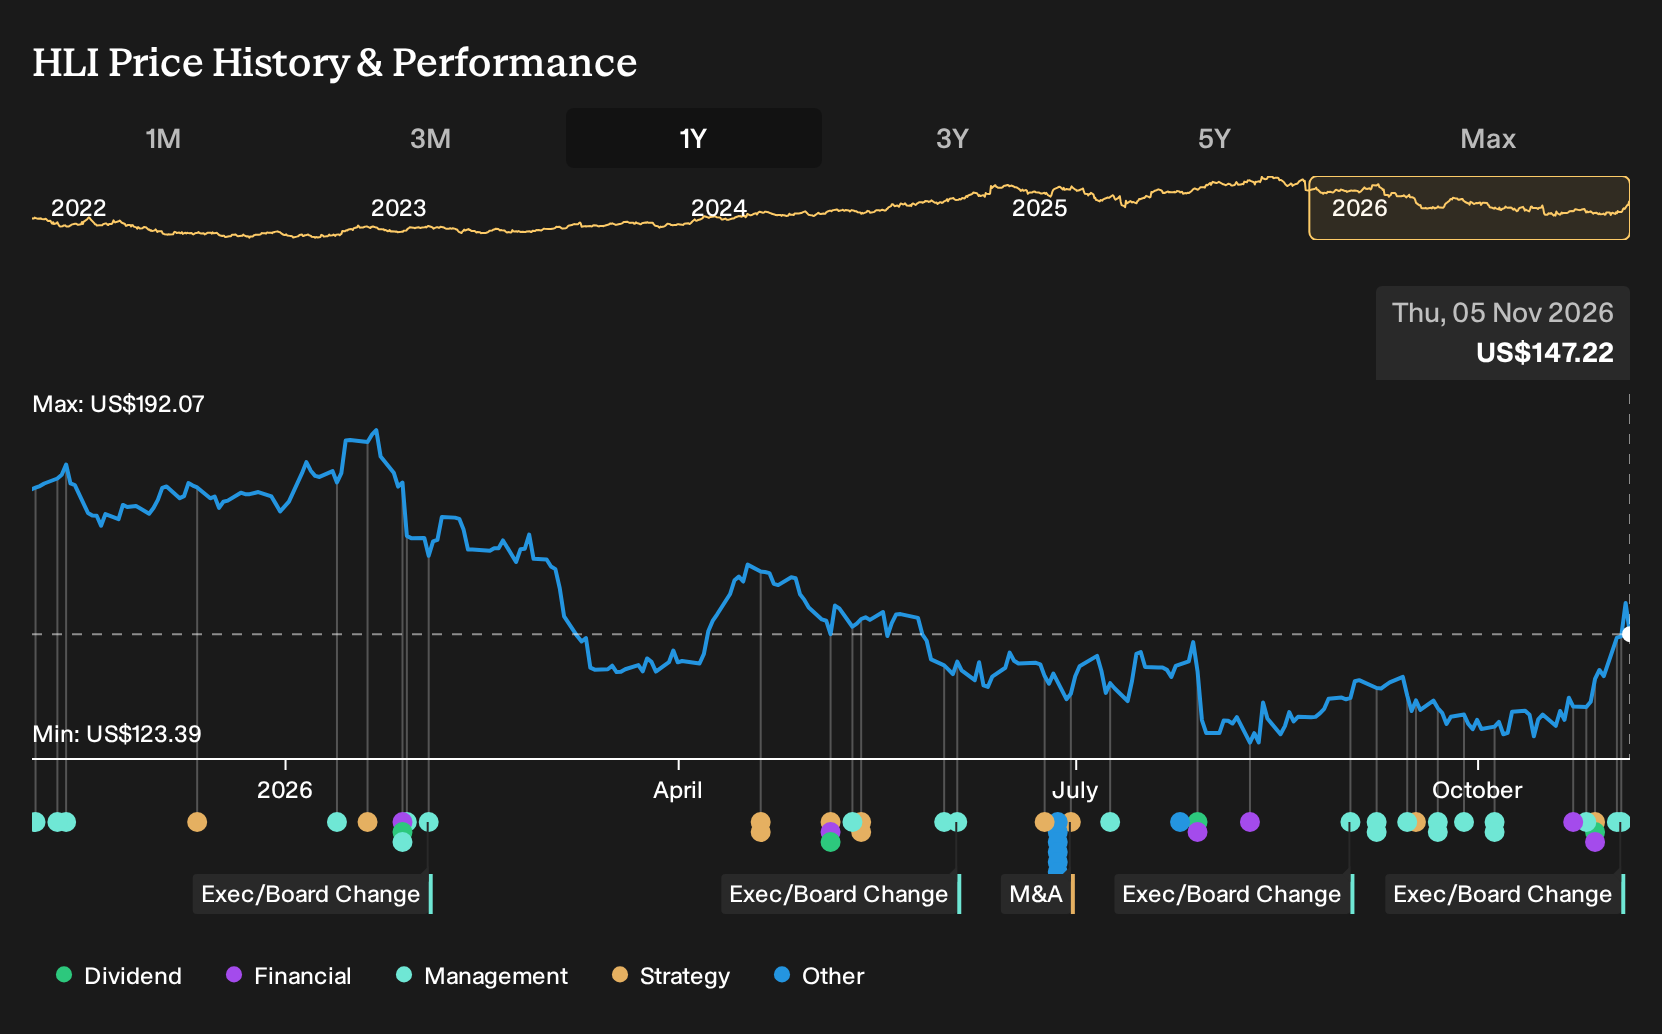
The regular quarterly dividend of US$0.70 per share announced for December 2026 is the most relevant signal related to these hires and the broader operating story. A consistent cash payout suggests management currently views the earnings base as solid enough to support ongoing shareholder distributions even as Corporate Finance revenue has been under pressure from delayed larger fee deals.
For you, that dividend sits alongside the core catalysts of a growing Capital Solutions franchise and continued investment in data and AI tools such as DataBank. If the expanded senior bench translates into more complex M&A, restructuring, and capital markets assignments, it could help offset deal timing risk and give the dividend more support, while a weaker fee environment would keep the payout ratio and cost base under closer scrutiny.
Houlihan Lokey’s current analyst script points to revenues of US$3.6b and earnings of US$579.3 million by 2029, based on a forecast 11.9% yearly revenue growth rate and an earnings increase of about US$175.6 million from the US$403.7 million the firm is generating today.
Uncover why Houlihan Lokey's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Houlihan Lokey leans hard into the risk that AI driven fee pressure in valuation services bites deeper. The most cautious analysts were pencilling in roughly US$3.4b of revenue and US$591.9 million of earnings by 2029 before these new senior hires, which sets a tighter, more pessimistic bar. That gap with the consensus path shows how far opinions can stretch. Use this news as a prompt to compare both narratives and decide which assumptions feel closer to your own.
Explore 2 other Houlihan Lokey fair value estimates, including one that suggests it could be worth just $160.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Houlihan Lokey research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Houlihan Lokey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Houlihan Lokey's overall financial health at a glance.
Looking For More Ideas Beyond Houlihan Lokey?
If this update on Houlihan Lokey has sharpened your thinking, use that momentum to widen your watchlist. Different business models and balance sheets respond very differently to the same macro backdrop, so it can help to compare Houlihan Lokey with a mix of income, quality, and value focused opportunities surfaced by the Simply Wall St Screener.
- For investors who want reliable balance sheets and fundamentals that can better absorb shocks, start with this curated list of solid balance sheet and fundamentals (24 results) and see which businesses match your risk appetite.
- If capital preservation comes first and you care about steadier profiles over big swings, scan a focused set of 32 resilient stocks with low risk scores that may suit a more cautious approach.
- Readers who prefer misunderstood quality with room for a re rate can comb through a targeted pool of 21 high quality undiscovered gems and source fresh ideas for deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com