


EN
Laureate Education (LAUR) Could Be 19% Undervalued On Earnings And The UCAL Deal
Laureate Education (LAUR) has drawn fresh attention after reaffirming its 2026 revenue outlook, reporting higher third quarter earnings, and expanding its Peruvian footprint through the acquisition of UCAL in Metropolitan Lima.
Despite reaffirmed 2026 guidance and the UCAL deal, Laureate Education’s share price has pulled back, with a 30 day share price return down 12.97% and a 90 day return down 13.17%. Even so, total shareholder return over five years is up 277.94%, suggesting long term holders have still seen strong gains while short term momentum has cooled.
Scan other education focused opportunities with operating trends similar to Laureate Education in our curated 21 high quality undiscovered gems list.
Laureate Education is reporting stronger earnings and reaffirmed guidance while the share price has slipped double digits in recent months. Is the recent pullback about the business, or simply shifting sentiment around the stock, and what does that imply for value?
Most Popular Narrative: 19% Undervalued
At a last close of $33.29 against a widely followed fair value estimate of $41.21, Laureate Education is framed as meaningfully undervalued. That gap depends on how the online and campus expansion story develops over time.
The main thing that has to go right is that Laureate Education continues to scale high margin online offerings, execute its multiyear campus buildout, and embed AI tools across marketing and student delivery while still achieving the targeted margin expansion.
See why 21 investors see Laureate Education as 19% undervalued.
Result: Fair Value of $41.21 (UNDERVALUED)
Still, the Laureate Education story could be challenged if new campuses underperform on enrollment or if earnings growth continues to trail revenue, which could pressure margins and cash generation.
Find out about the key risks to this Laureate Education narrative.
Another View: Laureate Education On Earnings Multiples
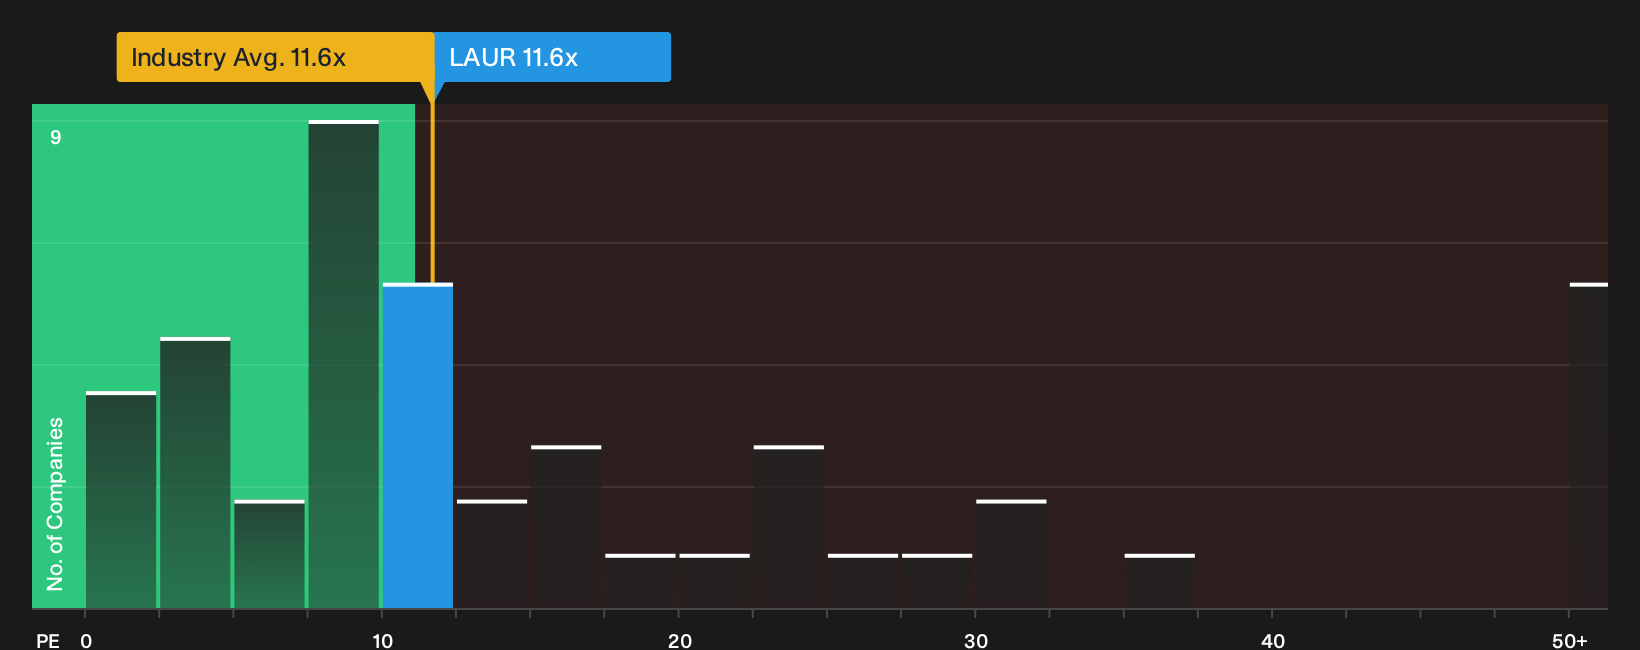
The story looks different when you shift from fair value estimates to plain P/E math. Laureate Education trades on an 11.6x P/E, slightly above a peer group at 11.4x but below the broader US Consumer Services average of 12.2x, while the fair ratio sits higher at 15.8x.
That mix points to a stock that screens a bit expensive versus close peers, yet still looks cheaper than where the fair ratio suggests the multiple could move over time. This raises a simple question for investors: is that gap signaling extra risk or a potential opportunity?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Laureate Education is mixed, so move quickly and review the underlying drivers yourself, then weigh up the 3 key rewards.
Looking for more Laureate Education style investment ideas?
If Laureate Education has sharpened your focus on quality and value, do not stop here. Broaden your watchlist with a few carefully filtered sets of stocks built from hard numbers, not hype.
- Target potential mispricings by scanning a curated field of companies that currently screen as 42 high quality undervalued stocks.
- Prioritize resilience by combing through a list of solid balance sheet and fundamentals (24 results) that can help support operations through tougher conditions.
- Lean toward consistency by reviewing a group of 6 dividend fortresses that could appeal if reliable income is part of your plan.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com