


EN
Okta (OKTA) Could Be 10% Below Fair Value As S&P 500 Entry Reshapes Flows
Okta (OKTA) just moved into the S&P 500 and related large cap indices while exiting several mid cap and small cap benchmarks, a reshuffle that directly affects index-tracking fund flows.
The rally in Okta over the past year has been strong, with a year-to-date share price return of 104.64% and a 1-year total shareholder return of 99.32%. However, momentum has recently cooled as the 7-day share price return declined 22.85% and the 1-day move fell 10.41% after a broader selloff in AI-related software names.
Scan how other identity and AI software stocks are reacting to the same index and ETF flows by running through our curated list of 41 AI small caps.
After a 1-year total return near 100% and a sharp pullback tied to AI software selling and index reshuffling, the key tension for Okta now is simple. Is meaningful upside still ahead, or was most of it already captured on the way into the S&P 500?
Most Popular Narrative: 13% Overvalued
Okta closed at $171.16, while the most followed valuation story on Simply Wall St pegs fair value at $151. That gap frames the current debate around whether recent index inclusion and AI enthusiasm have taken the share price ahead of the underlying narrative.
For a long time, the market criticized Todd McKinnon because Okta, despite having an excellent technical solution, failed to become profitable. With the Q1 FY2027 results, that discussion appears to be over.
The question is no longer whether Okta can become profitable. The new question is whether Todd can unlock the next market: Identity and Access Management (IAM) for AI Agents.
See why 105 investors see Okta as 13% overvalued.
Result: Fair Value of $151 (OVERVALUED)
Still, the Okta story can break if AI agent demand disappoints or if new identity products fail to support the current 21% profit margin assumptions.
Find out about the key risks to this Okta narrative.
Another View: Cash Flows Point in a Different Direction
While the popular Simply Wall St narrative tags Okta as 13% overvalued at $171.16 against a $151 fair value, the SWS DCF model tells a different story. On that cash flow view, Okta trades about 9.5% below an estimated value of $189.19. Which lens should carry more weight for you right now?
Look into how the SWS DCF model arrives at its fair value.
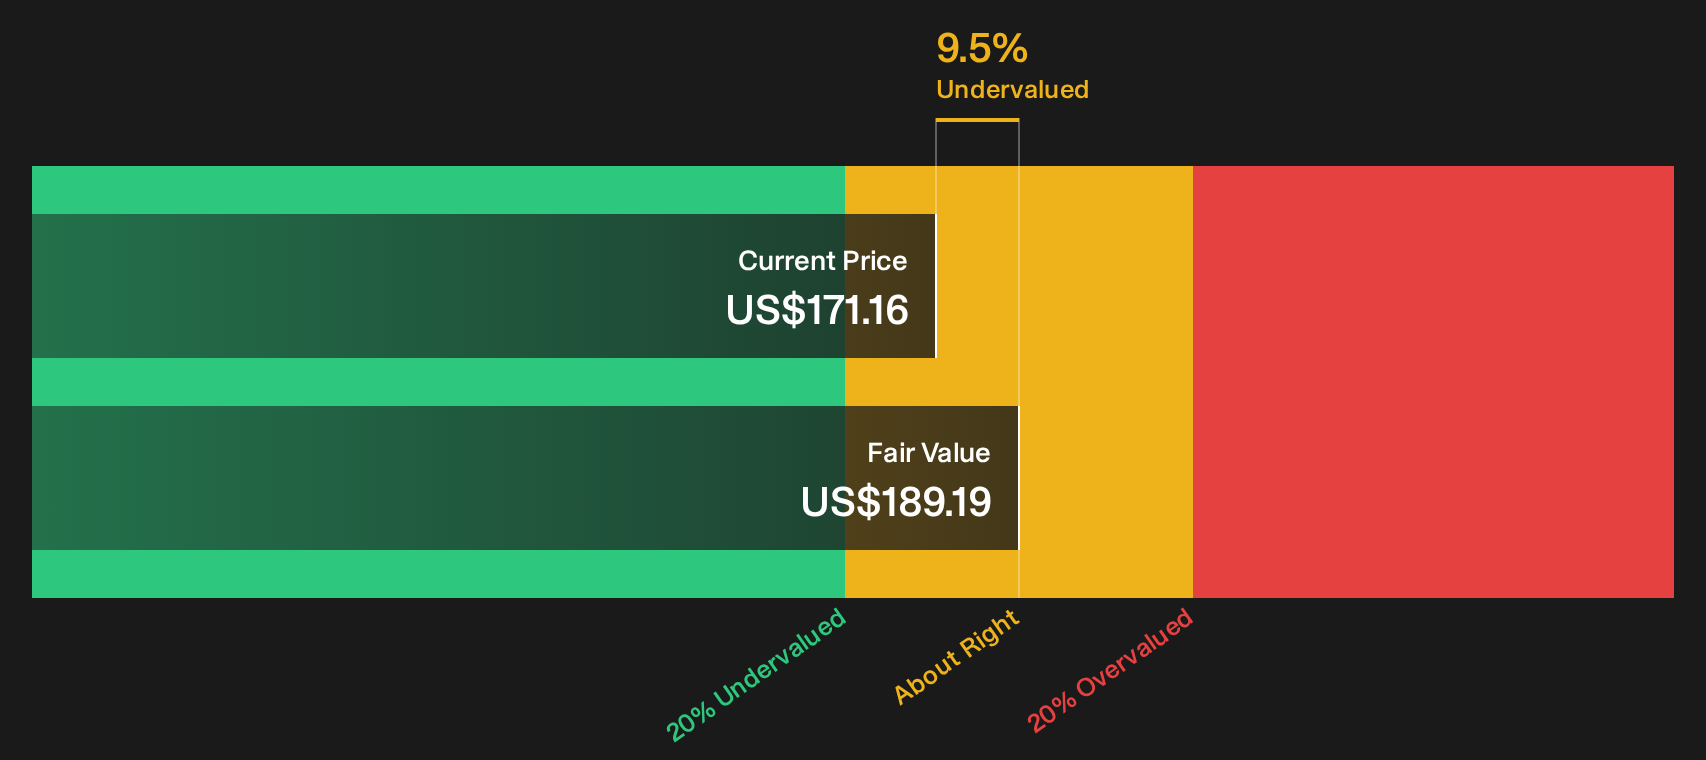
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Okta for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether the recent pullback resets Okta or simply cools an overheated run, given both flagged risks and clear upside drivers, it makes sense to review the full balance of 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Okta?
If Okta has your attention, do not stop there. Broader context from other opportunities can sharpen your portfolio decisions and highlight what you might be missing.
- Upgrade the quality bar in your portfolio by focusing on companies with resilient finances through our list of solid balance sheet and fundamentals (24 results).
- Hunt for strong businesses priced below their estimated value by checking the 42 high quality undervalued stocks.
- Prioritise stability and consistency by reviewing a curated set of 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com